





Market Brief FTSE roars higher for second straight session
A summary of news and snapshot of moves ahead of the US session.
Share this:

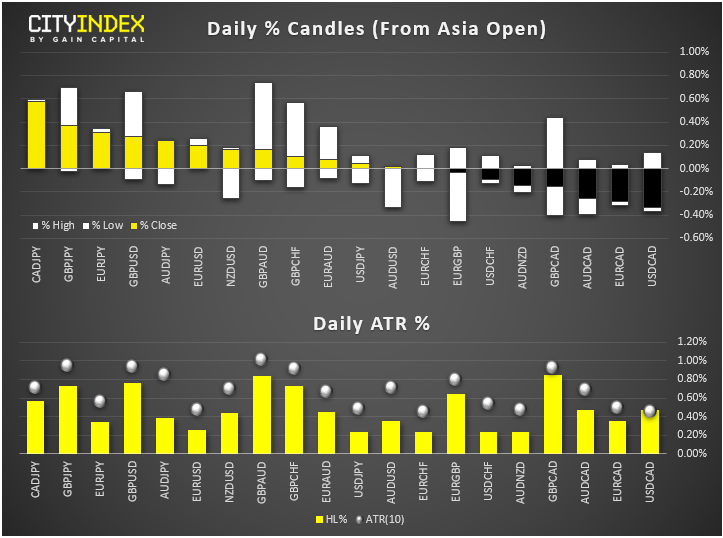
- Market update at just after midday in London: In FX, CAD lead commodity dollars higher while JPY and USD were the weakest. Stocks were higher in Europe, led by the FTSE, after a lacklustre session in Asia overnight and a flat close on Wall Street on Friday. Oil was higher, so too were copper and silver prices. Gold was flat as a weaker dollar and ongoing “risk-on” trade provided conflicting forces.
View our guide on how to interpret the FX Dashboard
- Sentiment towards risk assets remained positive after the US and China managed to strike a phase one trade deal and as voters in the UK delivered a surprisingly large support for PM Boris Johnson’s Conservatives - this has likely paved the way for the Brexit Withdrawal Agreement to be finally passed through parliament, ending months of uncertainty.
- Data recap: Today’s economic data releases show a mixed real economy. China’ retail sales (+8% y/y) and industrial production (+6.2% y/y) both topped expectations, while surveyed purchasing managers among manufacturers in UK (47.4), France (50.3), Germany (43.4), and Eurozone (45.9) reported deteriorating economic activity in the sector. However, these were offset by better than expected services PMIs from France (52.4), Germany (52.0) and Eurozone (52.4), although the UK PMI (49.0) was weaker.
- GBP: Despite the soft UK PMI data, the pound refused to give back any meaningful chunk of its election-linked gains. Investors realise the PMI data reflects sentiment before the outcome of the election was announced. UK data may well improve in the months ahead given the clearing of the dark Brexit clouds that had brought a gloomy feeling among businesses and households.
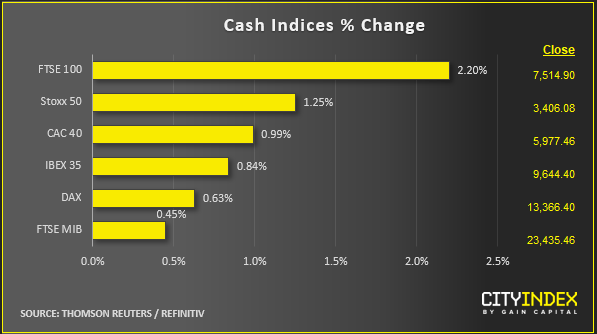
- Stocks: UK markets have jumped higher for the second session. This comes after Boris Johnson’s big election victory alleviating some Brexit-related uncertainty. It looks like we are not the only ones bullish on the FTSE as outlined in the Week Ahead report on Friday. Goldman Sachs said it was particularly bullish on UK homebuilders and banks that have struggled recently. “Clarity on the UK’s terms of exit from the EU should unlock pent-up business investment; the reversal of a decade of fiscal consolidation should provide a fillip to domestic demand; and a pick-up in global growth should underpin a recovery in net exports,” the bank said in a note.
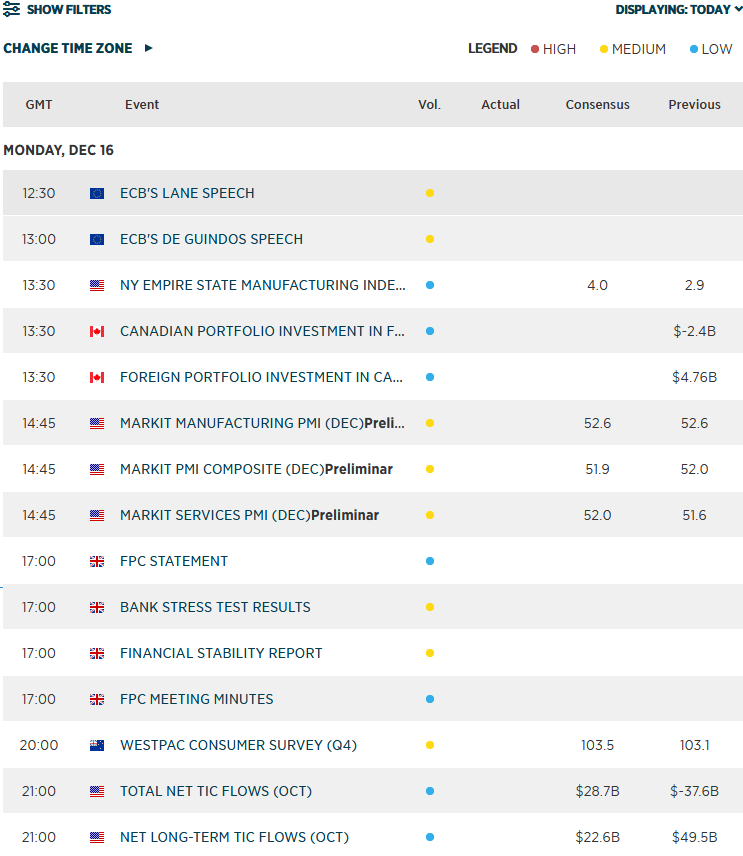
- Coming up:
- Market update at just after midday in London: In FX, CAD lead commodity dollars higher while JPY and USD were the weakest. Stocks were higher in Europe, led by the FTSE, after a lacklustre session in Asia overnight and a flat close on Wall Street on Friday. Oil was higher, so too were copper and silver prices. Gold was flat as a weaker dollar and ongoing “risk-on” trade provided conflicting forces.
View our guide on how to interpret the FX Dashboard
- Sentiment towards risk assets remained positive after the US and China managed to strike a phase one trade deal and as voters in the UK delivered a surprisingly large support for PM Boris Johnson’s Conservatives - this has likely paved the way for the Brexit Withdrawal Agreement to be finally passed through parliament, ending months of uncertainty.
- Data recap: Today’s economic data releases show a mixed real economy. China’ retail sales (+8% y/y) and industrial production (+6.2% y/y) both topped expectations, while surveyed purchasing managers among manufacturers in UK (47.4), France (50.3), Germany (43.4), and Eurozone (45.9) reported deteriorating economic activity in the sector. However, these were offset by better than expected services PMIs from France (52.4), Germany (52.0) and Eurozone (52.4), although the UK PMI (49.0) was weaker.
- GBP: Despite the soft UK PMI data, the pound refused to give back any meaningful chunk of its election-linked gains. Investors realise the PMI data reflects sentiment before the outcome of the election was announced. UK data may well improve in the months ahead given the clearing of the dark Brexit clouds that had brought a gloomy feeling among businesses and households.
- Stocks: UK markets have jumped higher for the second session. This comes after Boris Johnson’s big election victory alleviating some Brexit-related uncertainty. It looks like we are not the only ones bullish on the FTSE as outlined in the Week Ahead report on Friday. Goldman Sachs said it was particularly bullish on UK homebuilders and banks that have struggled recently. “Clarity on the UK’s terms of exit from the EU should unlock pent-up business investment; the reversal of a decade of fiscal consolidation should provide a fillip to domestic demand; and a pick-up in global growth should underpin a recovery in net exports,” the bank said in a note.
- Coming up:
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.
AUD/USD Q4 Outlook: RBA and Fed Hikes Set the Tone
AUD/USD enters Q4 with RBA and Fed hikes in focus as sticky inflation, rising unemployment and US dollar strength shape the Australian dollar.

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.