






Market Brief Risk On Extends As US Considers Tariff Rollback
A summary of news and snapshot of moves from today’s Asia session.
Share this:

FX Brief:
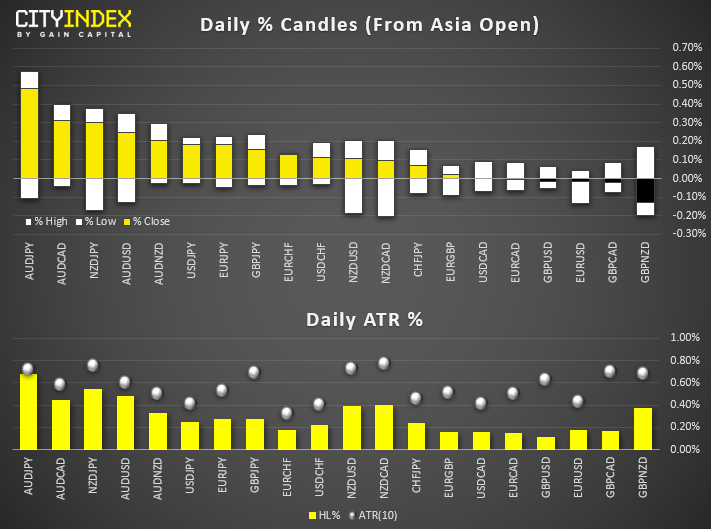
- AUD is today’s strongest major after RBA held rates. AUD/JPY is the biggest mover of the session and its daily range has spanned 95% of its 10-day ATR – given it remains beneath key resistance, we may need another catalyst for risk-on to break higher.
Reports that US was considering remove tariffs on $120 billion of Chinese goods was also supportive for AUD and NZD pairs. - Trade optimism saw the yuan appreciate further, taking USD/CNH to a 60-day low.
- DXY nudged its way to a 4-day high after yesterday’s rebound from key support.
- GBP/USD is stuck at yesterday’s, with potential for further downside given Friday’s bearish pinbar and Monday’s bearish engulfing candle.
Equity Brief:
- Risk on mode has continued to prevail in key Asia stock markets that has recorded modest gains between 0.15% to 0.70% except for Japan’s Nikkei 225 that has surged by 2%, more of a “catch-up play” due to a holiday closure yesterday.
- Continued bout of U.S-China trade deal optimism news flow seems to be the catalyst as a media report has cited that the White House is considering rolling back the 01 Sep tariffs imposed on $112 billon of Chinese imports, one of the sticking points that China has requested before any trade deal is being finalised.
- Also, China central bank PBOC has continued to provide liquidity by cutting its medium-term lending facility (MLF) by 5 bps to 3.25%, the first cut since early 2016. Perhaps such liquidity injection has managed to offset the expected negative reaction from China’s weak services sector activities. The Caixin China Services PMI has slipped unexpectedly to 51.1 in Oct (versus consensus forecast of 52.8) from 51.3 recorded in Sep; the weakest pace of growth in the services sector since Feb 2019.
- Technology sector has led the gains in the Hong Kong stock market for today where AAC Technologies, a supplier of Apple has surged by 3.5% to hit a 6-month high of HKD 53.30; the stock has rallied by 60% from its Aug 2019 low of 32.85.
- The performance of Australia’s ASX 200 was tepid due to a dent in overall sentiment by Westpac Banking Corp, one of the “Big 4” banks that plummeted as much as -5.1% to A$26.46 after a trading halt was lifted from yesterday, the biggest drop since Nov 2018. Westpac had completed a discounted A$2 billion equity placement where the issue price was at A$25.32 per share which was a significant 9% discount to its closing price on last Fri, 01 Nov.
- Oversea-Chinese Banking Corp (OCBC), a major component stock in the Singapore’s Strait Times Index (STI) has shed by -0.36% so far after it has reported a fall of 6% on its Q3 profit due to a one-off charge for Indonesian unit.
Up Next:
- UK manufacturing PMI is expected to contract at the slower rate of 49.7, versus 49.5 prior.
- ISM Non-manufacturing could shed further light on whether the US is headed for recession. The manufacturing counterpart has contracted for three consecutive months, yet services remains expansionary. Given we saw manufacturing’s contraction slow this month, it could leave potential for a positive surprise. USD pairs and US indices are markets to track around this release.

Matt Simpson and Kelvin Wong both contributed to this article
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.
View our guide on how to interpret the FX Dashboard
FX Brief:
- AUD is today’s strongest major after RBA held rates. AUD/JPY is the biggest mover of the session and its daily range has spanned 95% of its 10-day ATR – given it remains beneath key resistance, we may need another catalyst for risk-on to break higher.
Reports that US was considering remove tariffs on $120 billion of Chinese goods was also supportive for AUD and NZD pairs. - Trade optimism saw the yuan appreciate further, taking USD/CNH to a 60-day low.
- DXY nudged its way to a 4-day high after yesterday’s rebound from key support.
- GBP/USD is stuck at yesterday’s, with potential for further downside given Friday’s bearish pinbar and Monday’s bearish engulfing candle.
Equity Brief:
- Risk on mode has continued to prevail in key Asia stock markets that has recorded modest gains between 0.15% to 0.70% except for Japan’s Nikkei 225 that has surged by 2%, more of a “catch-up play” due to a holiday closure yesterday.
- Continued bout of U.S-China trade deal optimism news flow seems to be the catalyst as a media report has cited that the White House is considering rolling back the 01 Sep tariffs imposed on $112 billon of Chinese imports, one of the sticking points that China has requested before any trade deal is being finalised.
- Also, China central bank PBOC has continued to provide liquidity by cutting its medium-term lending facility (MLF) by 5 bps to 3.25%, the first cut since early 2016. Perhaps such liquidity injection has managed to offset the expected negative reaction from China’s weak services sector activities. The Caixin China Services PMI has slipped unexpectedly to 51.1 in Oct (versus consensus forecast of 52.8) from 51.3 recorded in Sep; the weakest pace of growth in the services sector since Feb 2019.
- Technology sector has led the gains in the Hong Kong stock market for today where AAC Technologies, a supplier of Apple has surged by 3.5% to hit a 6-month high of HKD 53.30; the stock has rallied by 60% from its Aug 2019 low of 32.85.
- The performance of Australia’s ASX 200 was tepid due to a dent in overall sentiment by Westpac Banking Corp, one of the “Big 4” banks that plummeted as much as -5.1% to A$26.46 after a trading halt was lifted from yesterday, the biggest drop since Nov 2018. Westpac had completed a discounted A$2 billion equity placement where the issue price was at A$25.32 per share which was a significant 9% discount to its closing price on last Fri, 01 Nov.
- Oversea-Chinese Banking Corp (OCBC), a major component stock in the Singapore’s Strait Times Index (STI) has shed by -0.36% so far after it has reported a fall of 6% on its Q3 profit due to a one-off charge for Indonesian unit.
Up Next:
- UK manufacturing PMI is expected to contract at the slower rate of 49.7, versus 49.5 prior.
- ISM Non-manufacturing could shed further light on whether the US is headed for recession. The manufacturing counterpart has contracted for three consecutive months, yet services remains expansionary. Given we saw manufacturing’s contraction slow this month, it could leave potential for a positive surprise. USD pairs and US indices are markets to track around this release.
Matt Simpson and Kelvin Wong both contributed to this article
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.

Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.


AUD/USD Q4 Outlook: RBA and Fed Hikes Set the Tone
AUD/USD enters Q4 with RBA and Fed hikes in focus as sticky inflation, rising unemployment and US dollar strength shape the Australian dollar.


USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.