



Nasdaq 100 Forecast: Stocks pause with inflation data and peace talks in focus
U.S. stock indices are pointing to a broadly flat open on Friday, as investors pause after strong gains earlier in the week and await key inflation data, while continuing to monitor geopolitical developments in the Middle East.
Share this:
US futures
Dow futures 0.02%, S&P futures 0.06% & Nasdaq futures 0.13%
In Europe
FTSE 0.60% & DAX 0.96%
- US stocks hold steady but are set for strong weekly gains
- US CPI data is expected to rise to 3.3% YoY
- US-Iran peace talks could take place this weekend
- Oil falls sharply across the week, even as the Strait remains effectively closed

US stocks hold steady but are set for strong weekly gains
U.S. stock indices are pointing to a broadly flat open on Friday, as investors pause after strong gains earlier in the week and await key inflation data, while continuing to monitor geopolitical developments in the Middle East.
The announcement of a temporary ceasefire between the U.S. and Iran earlier this week helped drive a sharp improvement in risk sentiment, putting the S&P 500 and Nasdaq on track for their strongest weekly performances since November, while the Dow is set for its best week since June. That rally was largely driven by a sharp drop in oil prices and a corresponding easing in stagflation concerns.
However, momentum is now stalling somewhat as markets reassess the durability of the two-week truce. There are increasing signs that the agreement remains fragile, with ongoing military activity in Lebanon and continued disruption to shipping flows through the Strait of Hormuz. This suggests that while risk appetite has improved, investors are not yet fully pricing in a sustained de-escalation.
Attention now turns to U.S. CPI data for March, which is expected to show inflation rising to 3.3% year-on-year. A stronger-than-expected reading could challenge the recent improvement in sentiment by reinforcing the view that inflation remains sticky. Notably, markets are no longer pricing in any rate cuts from the Federal Reserve in 2026, a significant shift from earlier expectations prior to the escalation in geopolitical tensions.
In parallel, diplomatic developments remain in focus. Talks between Washington and Tehran could begin as early as this weekend, although prospects for progress remain uncertain. Benjamin Netanyahu has indicated openness to direct negotiations with Lebanon, but the continuation of military operations highlights the complexity of the situation. As such, markets are likely to remain highly sensitive to headlines, with sentiment vulnerable to any signs of renewed escalation.
Corporate Movers
Nike is under pressure after being downgraded to neutral by Piper Sandler, with concerns centred on slowing demand and margin pressures in a more challenging consumer environment.
TSMC is moving higher in premarket trading after reporting first-quarter revenue ahead of expectations, reinforcing the view that demand linked to AI and advanced computing remains resilient despite broader macro uncertainty.
Meanwhile, DocuSign is falling after Citigroup cut its rating to neutral, pointing to valuation concerns and a more competitive growth outlook in the digital services space.
Nasdaq 100 forecast – technical analysis
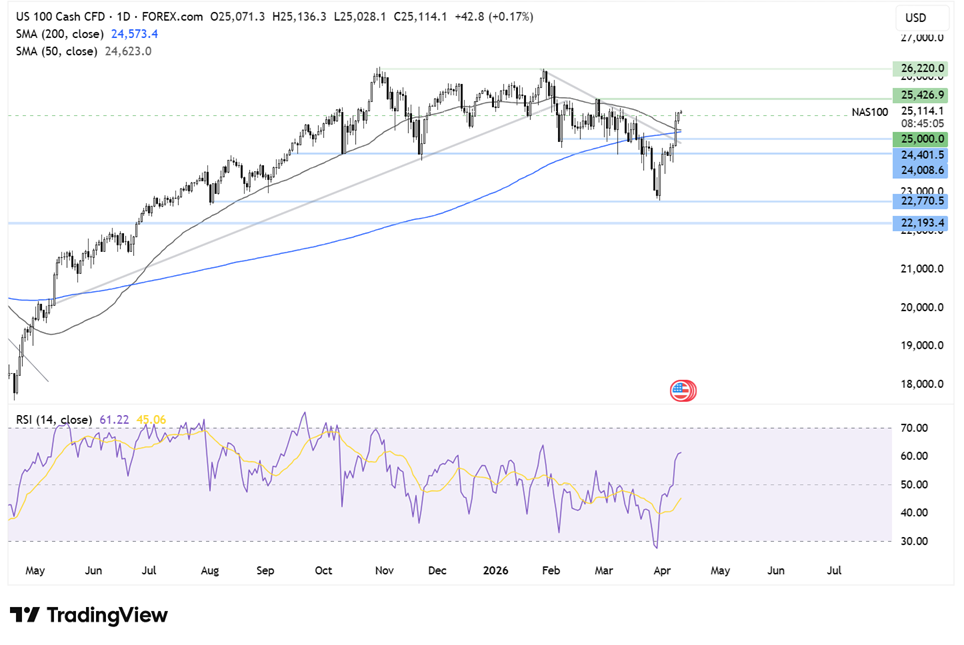
The Nasdaq rebounded from the 22780 March low, rising above the falling trendline resistance, the 200 and 50 SMA, to 25000.
Buyers supported by the RSIs above 50 will look to extend gains towards 25,440, the late February high, ahead of 26,220, the record high.
Immediate support is at 24,600, the confluence of the 50 and 200 SMA, and at 24,350, the horizontal support and falling trendline. Below here 24,000 comes into focus ahead of 22,780, the 2026 low.
FX Markets -USD flat, EUR/USD steady
The U.S. dollar is broadly steady on Friday but remains on track for a weekly decline of around 1.3%, which would mark its largest drop since January. The move reflects a combination of safe-haven outflows following the ceasefire announcement and a pullback in U.S. Treasury yields. However, the dollar’s downside appears to be limited for now, as investors remain cautious ahead of key inflation data and ongoing geopolitical uncertainty. A stronger-than-expected CPI print could quickly revive support for the currency by reinforcing higher-for-longer rate expectations.
EUR/USD is extending its gains, rising around 1.4% over the week. The move has been supported not only by improved global risk sentiment but also by stronger domestic data, with German inflation rising to 2.8% year-on-year from 1.9%. This increase, driven largely by energy prices, may strengthen the case for a more cautious or even hawkish stance from the European Central Bank, particularly if inflation pressures prove persistent.
GBP/USD is also advancing, up roughly 1.7% on the week. Sterling is benefiting from broad dollar weakness as well as the decline in oil prices, which helps ease stagflation concerns for the UK economy. Given the UK’s reliance on imported energy, lower oil prices reduce pressure on both inflation and household incomes, supporting the currency in the near term.
Oil set for largest weekly decline since June
Oil prices are edging higher on Friday but are still set for their largest weekly decline since June, down approximately 10–12% after the ceasefire announcement pushed crude below $100 per barrel.
Despite this sharp correction, underlying supply risks remain significant. Shipping flows through the Strait of Hormuz are still running at only around 10% of normal levels, indicating that the physical disruption to global energy markets has not yet been resolved.
In addition, around 2.4 million barrels per day of refining capacity in the Gulf has reportedly been taken offline due to damage from drone and missile strikes. This highlights that, even with a ceasefire in place, the structural impact on supply chains could persist for some time.
As a result, while markets have partially priced in a normalisation scenario, a meaningful further decline in oil prices will depend on tangible progress in negotiations and, crucially, a reopening of the Strait of Hormuz. Until then, a geopolitical risk premium is likely to remain embedded in energy markets.
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Wall Street Split Widens Into Month-End 9 26 2026
Nasdaq strength contrasts with mounting Dow pressure as rising Treasury yields raise the stakes for stocks heading into the monthly close.

Equity Indices Q4, 2026 Outlook: Cracks Begin to Show
There's still an open door for a melt-up in the S&P 500 and Nasdaq but the Dow and Russell 2000 are looking more vulnerable, and until calm hits the Treasuries market there's a higher probability for volatility. The big question is whether that's a next quarter theme or not.


S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.