



S&P 500 Forecast: SPX muted despite a weak ADP payroll report
US stocks open in a muted fashion despite the ADP payroll report raising concerns over the labour market, and as investors continue to monitor trade talks ahead of the July 9 deadline.
Share this:
US futures
Dow futures -0.2% at 44412
S&P futures -0.04% at 6193
Nasdaq futures 0.04% at 22480
In Europe
FTSE -0.47% at 8745
DAX 0.04% at 23718
- US stocks are unchanged for a second session
- ADP payrolls fell by 33k, defying expectations of a 95k rise
- The Senate voted through Trump’s bill by 51-50
- Oil rises modestly with Iran in focus
ADP payrolls fell by 33k
US stocks open in a muted fashion despite the ADP payroll report raising concerns over the labour market, and as investors continue to monitor trade talks ahead of the July 9 deadline.
The ADP payroll showed that US private payrolls unexpectedly fell by 33,000 in June, and job gains in the previous month were smaller than initially thought. The data comes after Federal Reserve chair Jerome Powell said yesterday that a July rate cut isn't off the table.
With this in mind, the focus now turns to the more comprehensive nonfarm payroll report scheduled for release tomorrow, as the markets are closed on Friday for the Independence Day holiday. The data is expected to show that job growth cooled in June to 210,000 and that the unemployment rate ticked higher to 4.3%. A significantly weaker than expected report could add to July rate cut expectations.
Following today's data, the market increased its bets on a July rate cut to 27% from around 20% prior to the report.
Meanwhile, trade talks remain in focus after Trump said he is not looking to extend the July 9 deadline for imposing tariffs. He also expressed doubts over an agreement being reached with Japan; the one with India is expected to cross the line.
The US Senate also passed Trump's massive tax and spending bill on Tuesday by 51 to 50. It's fun seeing the package, which includes generous tax cuts, a reduction in social safety net programs, and higher military spending, which could add $ 3.3 trillion to national debt levels. Trump is keen for the bills passed by the House of Representatives to be signed quickly before the end of the week.
Corporate news
Tesla is opening 5% higher, recouping yesterday's 5% losses despite Q2 deliveries missing expectations. Tesla delivered 384,122 vehicles in the second quarter of 2025, falling short of consensus estimates of 390,100 units. This was also below the 443,956 deliveries reported in the same quarter last year.
JP Morgan and Bank of America, which includes Wells Fargo, rose after the announcement that they intend to raise their Q3 dividends following the Fed's annual stress test.
S&P 500 forecast – technical analysis
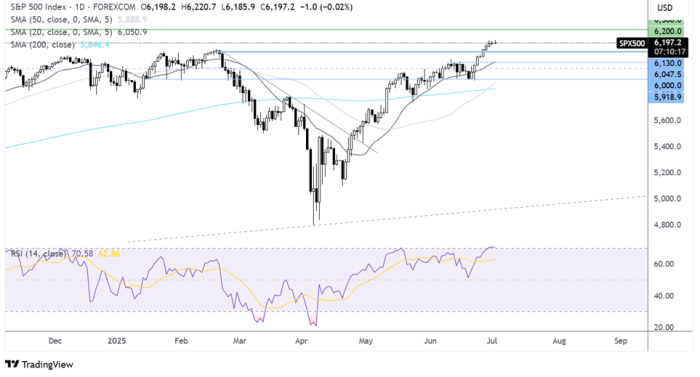
The S&P 500 extended gains to fresh record highs at 6220. The RSI is tipping into overbought territory, so there could be some consolidation around here. With blue skies above, 6250 and 6300 are the next levels to be watching for. Support can be seen at 6150, the February high, and below here 6050 and 6000. A break below 5930 is needed to create a lower low.
FX markets – USD rises, EUR/USD falls
The USD is rising after Trump’s bill passed the Senate vote and despite very weak ADP payroll data. The recent USD drop to multi-year lows was also looking a little overstretched technically.
The EUR/USD is falling amid a stronger USD and as investors continue to digest ECB President Lagarde’s remarks at the central bankers' forum. Lagarde noted that the region faces increased volatility in inflation. Yesterday's data showed that the CPI rose to 2%, the ECB’s target level.
GBP/USD is after PM Starmer doesn't rule out tax rises to pay for welfare concessions. The U-turn to pass welfare reforms means that money is no longer being saved, and the Chancellor’s margin has been slashed, making tax hikes more likely.
Oil rises with Iran in focus
Oil prices are rising on Wednesday after Iran suspended cooperation with the UN nuclear watchdog, and as the market expects more supply from OPEC+.
The market is pricing in some geopolitical risk premium after Iran stipulated that future inspections of its nuclear sites by the International Atomic Energy Agency must first be approved by Tehran's Supreme National Security Council. This is a sentiment-driven move, as the supply remains unaffected.
Meanwhile, planned increases by OPEC+ in the coming meeting could limit the upside in oil prices, particularly given the uncertainty surrounding Trump’s tariffs and the impact on demand.
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Wall Street Split Widens Into Month-End 9 26 2026
Nasdaq strength contrasts with mounting Dow pressure as rising Treasury yields raise the stakes for stocks heading into the monthly close.

Equity Indices Q4, 2026 Outlook: Cracks Begin to Show
There's still an open door for a melt-up in the S&P 500 and Nasdaq but the Dow and Russell 2000 are looking more vulnerable, and until calm hits the Treasuries market there's a higher probability for volatility. The big question is whether that's a next quarter theme or not.


S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.