



S&P 500 Forecast: SPX slips after a stellar Q2
U.S. futures are pointing to a slightly lower open on the final trading day of the month, quarter and first half of the year, as investors assess whether the AI-driven rally can extend into the third quarter and weigh the prospect of higher U.S. interest rates.
Share this:
US futures
Dow futures -0.29%, S&P futures -0.23% & Nasdaq futures -0.83%
In Europe
FTSE -0.56% & DAX -0.07%
- U.S futures fall after strong gains in Q2
- Chip stocks led the S&P 500 to jump 15% in Q2
- Nike falls despite beating forecasts
- Oil drops $45 across the quarter
U.S. Futures Muted After Strong Quarter as Focus Shifts to Jobs Data
U.S. futures are pointing to a slightly lower open on the final trading day of the month, quarter and first half of the year, as investors assess whether the AI-driven rally can extend into the third quarter and weigh the prospect of higher U.S. interest rates.
The S&P 500 posted its strongest quarterly performance since 2020, rising almost 15% in Q2, while the Nasdaq surged 27.5%, also marking its best quarter in four years. Chipmakers once again led the gains, with the Philadelphia Semiconductor Index soaring almost 88% over the quarter.
However, investors are becoming increasingly selective. While enthusiasm for AI remains intact, attention is shifting towards whether the enormous investment in AI infrastructure can generate earnings growth quickly enough to justify elevated valuations. At the same time, expectations that the Federal Reserve could tighten policy further are raising discount rates and creating a more challenging backdrop for high-growth stocks.
On the data front, ADP employment rose by 98,000 in June, down from 122,000 previously and below forecasts of 110,000, pointing to a modest cooling in private-sector hiring. However, annual pay growth remained resilient at 4.4% for workers staying in their jobs and edged higher to 6.6% for job changers, suggesting wage pressures remain elevated.
The figures follow yesterday's JOLTS report, which showed job openings unexpectedly increased, while consumer confidence also improved, reinforcing the view that the U.S. labour market remains resilient.
Attention now turns to Federal Reserve Chair Kevin Warsh's speech at the ECB Forum in Sintra. While Walsh is unlikely to provide explicit forward guidance, investors will be looking for his assessment of the economy and whether recent data have strengthened the case for further tightening.
Markets are currently pricing around a 65% probability of a 25-basis-point rate hike in September. Tomorrow's non-farm payroll report, brought forward because of Friday's Independence Day holiday, will be the week's key event for interest-rate expectations.
Corporate Movers
Nike is falling more than 3% despite reporting better-than-expected fiscal fourth-quarter earnings and revenue. Growth in the wholesale business and a one-off tariff-related benefit helped support results, but investors focused instead on weaker guidance and continued pressure in the direct-to-consumer business. Sales in Greater China fell 12%, reinforcing concerns that the turnaround in one of Nike's key markets remains some way off.
Constellation Brands is rising 1.5% after beating expectations in its first-quarter earnings report. The company posted earnings per share of $3.43 versus expectations of $3.20, while revenue also exceeded forecasts. Full-year guidance was maintained, suggesting management remains confident despite softer consumer spending.
Memory chip stocks are weaker at the start of the third quarter as investors continue to lock in profits following an exceptional Q2. SanDisk is down 3.5%, while Micron Technology is off 2.5% after both stocks more than tripled in value during the second quarter.
S&P 500 Forecast – Technical Analysis
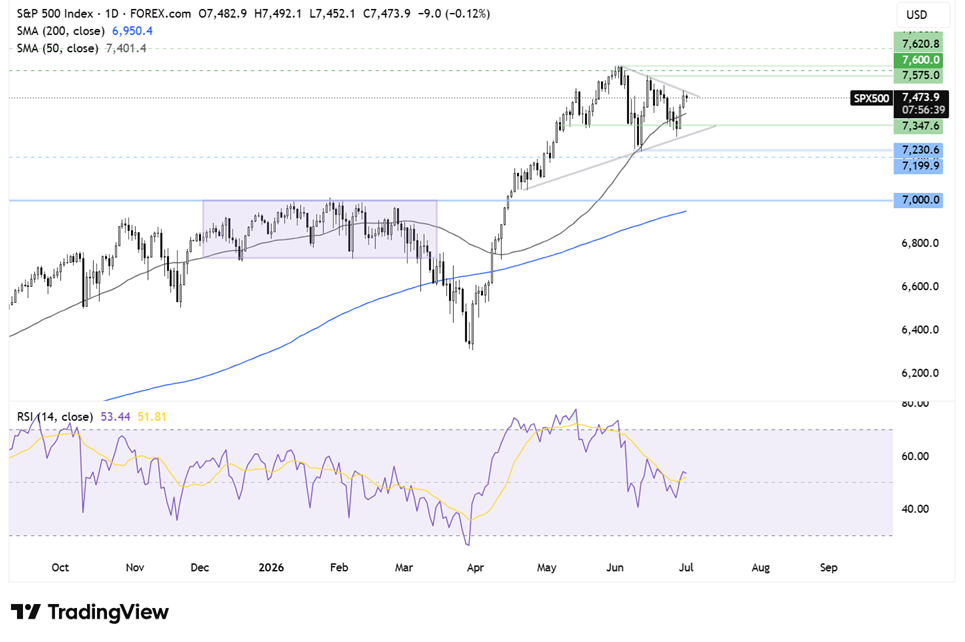
The S&P 500 continues to trade within a symmetrical triangle pattern.
The index recently rebounded from rising trendline support near 7,290 before reclaiming the 50-day SMA and testing resistance around 7,500 at the upper boundary of the pattern.
Should buyers break above 7,500, attention would turn to 7,575, the June high. A move above there would create a higher high and bring the record high at 7,620 into focus.
Immediate support lies at the 50-day SMA near 7,400, followed by horizontal support at 7,350 and rising trendline support at 7,290. A break below the trendline would complete a downside breakout from the triangle and expose the June low near 7,230.
FX Markets – USD Firms, Yen Remains on Intervention Watch
The U.S. dollar is strengthening, remaining close to a 13-month high as Treasury yields continue to rise. The 10-year Treasury yield has climbed to 4.47%, its strongest weekly rise in a month, supported by expectations that the Federal Reserve could raise interest rates again this year. Month-end positioning may also be providing additional support.
Markets are pricing around a 67% probability of a September rate hike.
EUR/USD is slipping after Eurozone inflation cooled by more than expected. Headline CPI eased to 2.8% year-on-year from 3.2%, below expectations of 3%, reducing expectations for a more aggressive ECB tightening cycle. Even so, markets still expect one further ECB rate hike before year-end. ECB President Christine Lagarde is due to speak later today at the Sintra Forum.
USD/JPY has climbed to a fresh 40-year high above 162.80, well beyond the levels that previously prompted intervention by Japanese authorities. The widening Fed-BOJ policy divergence continues to support the carry trade, although the risk of intervention is rising. With Friday's U.S. holiday likely to reduce market liquidity, conditions could become more favourable for official action. Bank of Japan Governor Kazuo Ueda is also due to speak later today at the Sintra Forum.
Oil Extends Quarterly Decline as Iran Talks Continue
Oil prices are down around 1% on Wednesday as negotiations between the U.S. and Iran continue in Doha and investors await U.S. inventory data.
Technical discussions are taking place with Pakistan acting as a mediator, following higher-level talks earlier this week.
Optimism that Middle Eastern supply will continue to normalise has helped Brent crude fall by around $45 during the second quarter, marking its largest quarterly decline since the global financial crisis in 2008. WTI has fallen by around $31 over the same period.
The sharp decline reflects the unwinding of the geopolitical risk premium as the ceasefire has held and shipping through the Strait of Hormuz has resumed. Unless negotiations deteriorate materially, the market is likely to remain focused on recovering supply and the pace of global demand rather than geopolitical disruption.
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Wall Street Split Widens Into Month-End 9 26 2026
Nasdaq strength contrasts with mounting Dow pressure as rising Treasury yields raise the stakes for stocks heading into the monthly close.

Equity Indices Q4, 2026 Outlook: Cracks Begin to Show
There's still an open door for a melt-up in the S&P 500 and Nasdaq but the Dow and Russell 2000 are looking more vulnerable, and until calm hits the Treasuries market there's a higher probability for volatility. The big question is whether that's a next quarter theme or not.


S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.