



S&P500 Forecast: SPX grinds higher with trade developments in focus
U.S. stocks point to a modestly higher open as investors pause for breath following a strong start to the week fueled by optimism surrounding the U.S.-China trade deal and cooler-than-expected inflation. US indices have rebounded strongly as the worst-case scenario for trade tariffs has passed and amid a de-escalating trade war with China.
Share this:
US futures
Dow futures 0.12% at 42184
S&P futures 0.18% at 5893
Nasdaq futures 0.24% at 21240
In Europe
FTSE -0.12% at 8597
DAX -0.25% at 23568
Stocks pause for breath after turning positive for the year
Cooling inflation & de-escalating trade tensions support stocks
Nvidia extends gains from yesterday after Saudi Arabia trade deal
Oil falls after 4-days of gains
S&P 500 turns positive for the year
U.S. stocks point to a modestly higher open as investors pause for breath following a strong start to the week fueled by optimism surrounding the US-China trade deal and cooler-than-expected inflation.
The S&P500 and the Nasdaq closed higher yesterday, while the Dow Jones bucked the trend with a lower close, dragged down by an 18% slump in UnitedHealth.
US indices have rebounded strongly as the worst-case scenario for trade tariffs has passed and amid a de-escalating trade war with China. S&P 500 is now trading positively for the year for the first time since February.
Whilst trade deal news has helped the recovery, trade tariffs are still higher than they were when Trump came into office. So far, data has held up well, with US inflation figures yesterday is showing that CPI cooled by more than expected to 2.3%. Whilst it could still take time for the impact of trade tariffs to show up in hard data, a de-escalation of trade tensions is certainly helpful for growth, making inflation less of an issue for the Fed.
The Fed is expected to cut rates by 25 basis points but may not do so until later in the year to give a clearer picture of the impact of tariffs on the economy.
There is no high-impacting US data today. Attention will be on Federal Reserve Chair Jerome Powell, who is due to speak tomorrow
Corporate news
Nvidia is adding to yesterday's gains of 5%, trading an additional 2% higher following deals in Saudi Arabia with the US. Nvidia chips will be used to build out data centers in the kingdom.
American Eagle Outfitters slumped 13% after the clothing retailer withdrew its outlook for the year after weaker than expected Q1 earnings.
S&P 500 forecast – technical analysis.
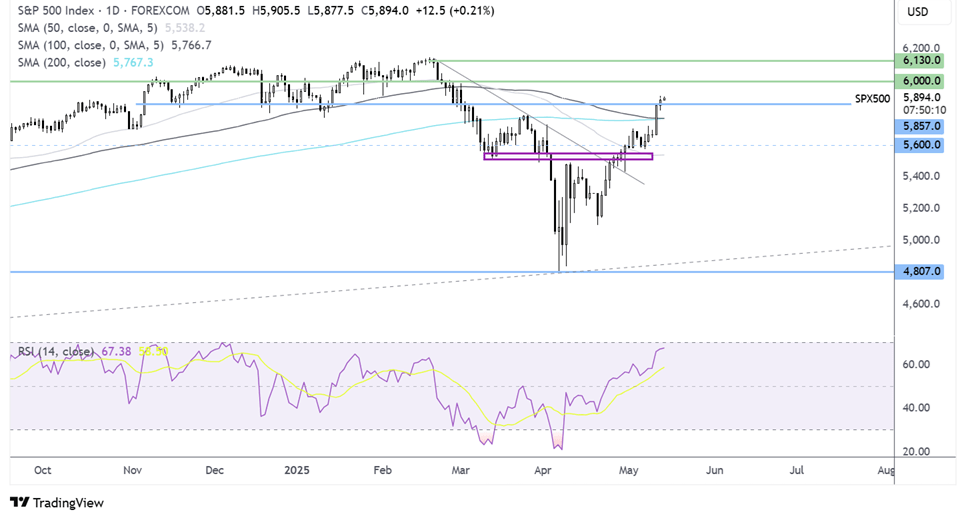
The S&P 500 recovered from the 4800 low, rising aggressively above the 200 SMA to current levels at 5900 turning positive on the year. The bullish engulfing candle, combined with the RSI above 50 and below 70, supports further upside. Buyers will look to extend gains towards 6000. Failure at 5900 could see the price fall back to test 5780, the 200 SMA.
FX markets – USD falls, EUR/USD rises
The USD is falling further, extending yesterday’s decline after cooler-than-expected CPI data cooled to its lowest level in four years. Trump once again criticized Powell for not cutting rates.
The EUR/USD is rising despite German inflation easing to 2.2%, a six-month low. ECB policymaker Villeroy de Galhau was optimistic that the ECB would cut rates again before the summer. However, the dovish ECB stance could limit the upside in EUR.
GBP/USD is rising for a second straight day, capitalising on a softer U.S. dollar and does not beat the market mood. BoE policymaker Catherine Mann feds but she voted to keep interest rates on hold last week after seeking a bigger 50 basis point cut in February because the labour market had been more resilient than she had expected. Yesterday's data showed that wage growth eased by less than expected to 5.6%, which is still high by historical standards.
Oil falls after 4 days of gains
Oil prices are slipping lower on Wednesday after four days of gains as investors eye a potential increase in US crude oil inventories.
The weekly EIA inventory report follows API numbers yesterday, which showed crude stockpiles were up by 4.3 million barrels in the week ending May 9, while gasoline ventures fell by 1.4 million barrels.
Meanwhile, the OPEC monthly report will also be released later today, detailing the supply and demand outlook.
Oil has had a solid rally over the past few days so some profit-taking is to be ex. However, gains from here may be limited giving the concerns surrounding demand.
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Wall Street Split Widens Into Month-End 9 26 2026
Nasdaq strength contrasts with mounting Dow pressure as rising Treasury yields raise the stakes for stocks heading into the monthly close.

Equity Indices Q4, 2026 Outlook: Cracks Begin to Show
There's still an open door for a melt-up in the S&P 500 and Nasdaq but the Dow and Russell 2000 are looking more vulnerable, and until calm hits the Treasuries market there's a higher probability for volatility. The big question is whether that's a next quarter theme or not.


S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.