



SPX Jumps, Yields Soften After CPI Data
Stocks are putting in a big move and 10-year Treasury Notes are showing the largest decline in yields since last August, just before stocks bottomed.
Share this:

SPX, Yields Talking Points:
- U.S. markets are putting in big moves on the morning after the release of U.S. CPI data for the month of December.
- Headline CPI printed at the expectation of 2.9% YoY but Core CPI came in a touch below the expectation, printing at 3.2% v/s the 3.3% that was expected. But – that did go in the direction of the PPI miss yesterday that gives hope for FOMC rate cuts later in the year.
- The move across markets has been intense so far, with 10-year yields dropping by 14 bps and SPX catching a strong bid to extend the rally from the election gap that finished earlier this week.
- The question now is whether the pullback in stocks is over or whether sellers come in ahead of a 6k re-test. I look into this below.
Bulls are back in a big way for U.S. equities, and this stands in stark contrast to the sell-off from last week.
This Monday saw SPX gap down to finish off the election gap and that’s around where support started to play-in at 5782. While yesterday’s daily candle finished red for the index, it also finished higher than the Monday close after that daily bar had gapped-higher, and that move was driven by the softer PPI readings that came out ahead of the bell yesterday.
But tension remained as can be seen by the intra-day pullback yesterday, and the wait was for CPI data that released this morning. While the data didn’t come in below the expectation as much as the PPI data a day prior, it also didn’t beat expectations and this fueled hope that we may, in fact, get rate cuts in at some point this year.
It’s still early, however, and the CPI data from this morning wasn’t exactly a major positive for rate cut hopes, as headline CPI printed at 2.9% on a year-over-year basis and that’s against last month’s 2.7% reading and the 2.4% level that printed in September. So, inflation is still pushing higher, even if the actual print didn’t come out above the expectation.
And Core CPI did come out softer than the expectation, but the delta was slight, with year-over-year CPI printing at 3.2% against the 3.3% expected and that was the same level that printed in Core CPI in August and September releases of last year. That then led to three consecutive months at 3.3% and then this month showed a slight decline.
To sum, the CPI release wasn’t a clear sign that inflation is slowing to the point where the Fed can push another cut in March and given the massive response that’s shown in both bonds and stocks, it seems as though there’s a short-cover move taking place. This, of course, can turn into the initial seeds of a rally but the big question now is whether buyers come in to defend higher-low supports to allow for that next test of the 6k handle that bulls haven’t been able to do much above yet.
The daily chart of SPX below is updated from yesterday’s webinar and there’s a couple levels of note for buyers to defend. A support hold in the 5881-5888 level would be construed as bullish, as buyers would not allow for a fill of today’s opening gap. Below that, 5827, or the top of the election gap, is another level where support holds would bring a bullish bias. And then below that, it’s the 5827-5842 zone that’s of note, as this goes from last week’s close to the bottom of today’s opening gap.
SPX, S&P 500 Four-Hour Chart
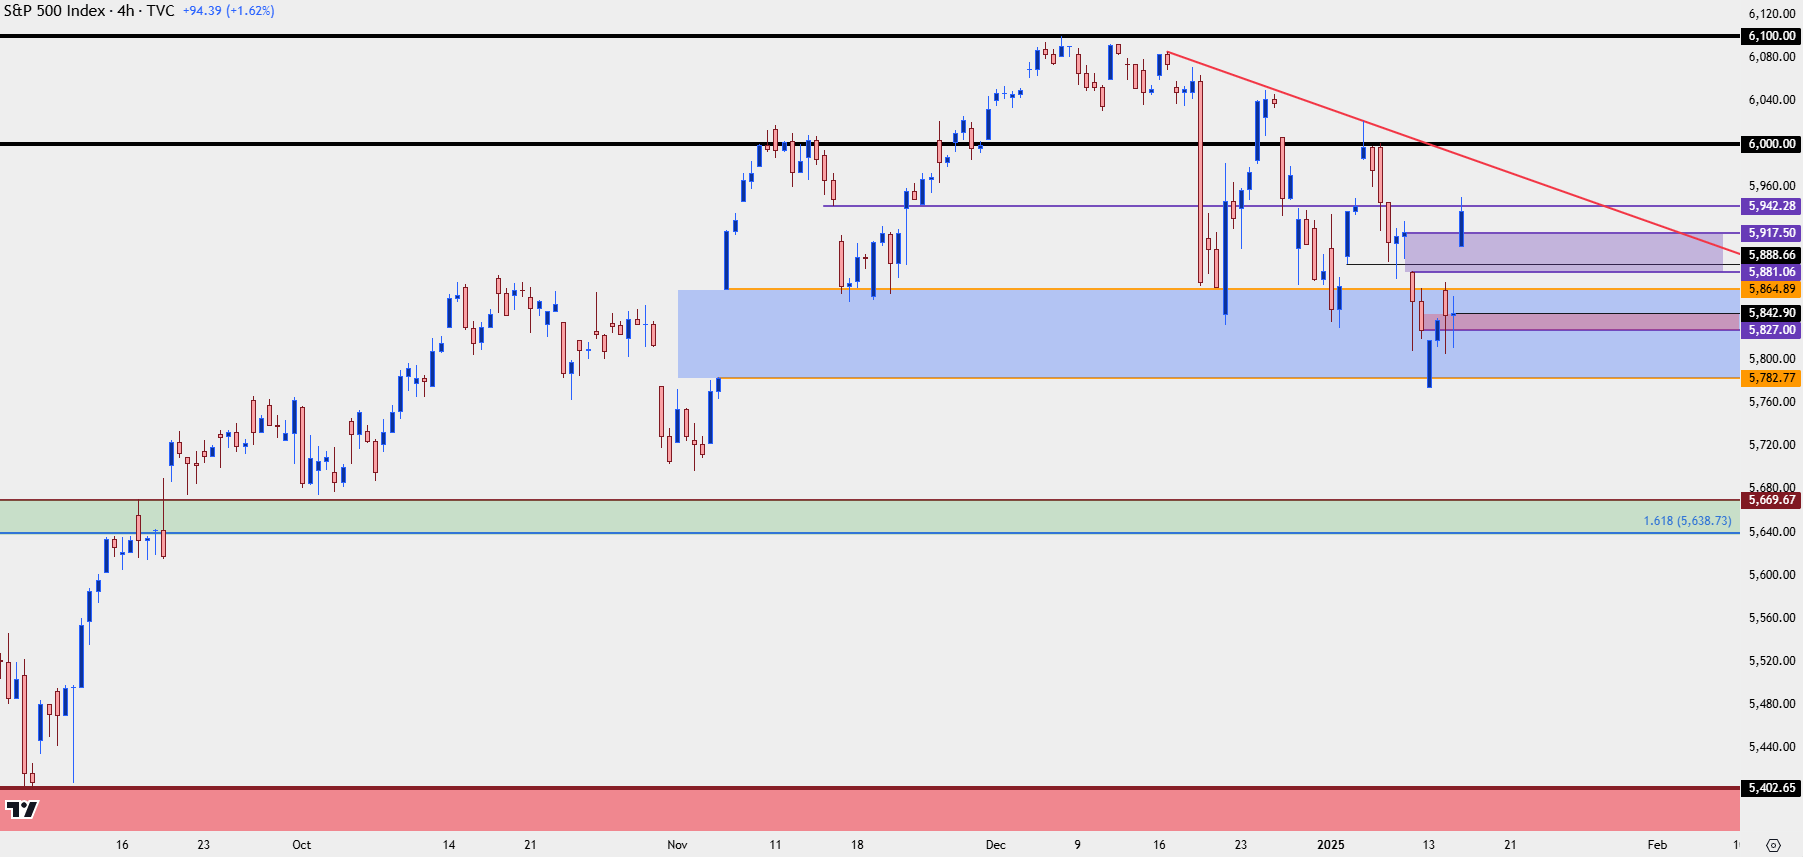 Chart prepared by James Stanley; data derived from Tradingview
SPX Bigger Picture
Bullish equities after a pullback was my top trade idea for 2025, and the election gap was the first zone of support that I was tracking which has already come into play.
But the big question now is whether that can last and I think the answer for that derives back to bonds, which I’ll look at in a moment. But – from the daily chart of SPX we had a fresh lower-low print to start this week and it’s not until we take out the prior lower-high, around the 6k level, that we can say that the trend on the daily has started to shift. Until then, this is a possible lower-high and bulls should remain cautious of possible reversal setups, unless one of the above support zones come into play.
SPX Daily Price Chart
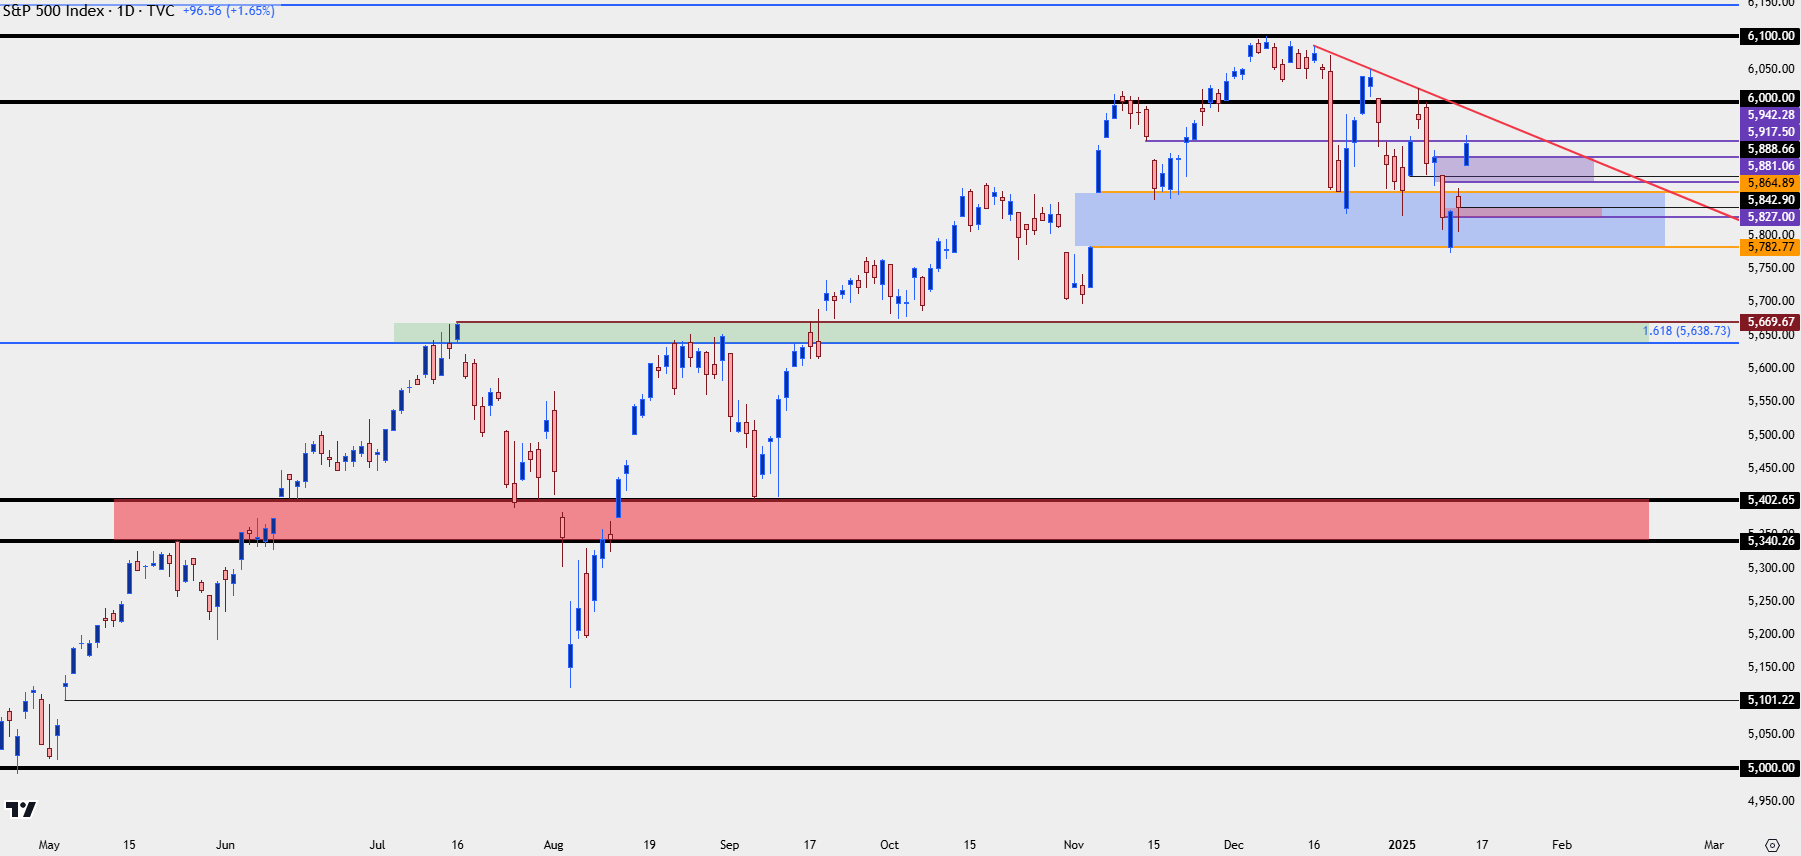 Chart prepared by James Stanley; data derived from Tradingview
Bonds
U.S. Treasury yields have been on a steep incline since the election. And I’ve read a number of possible reasons for that and perhaps some of them are true. But, what’s notable is the context with which this has taken place, as 10-year yields have risen by as much as 120 basis points since just before the Fed kicked off a rate cut cycle.
That’s helped to normalize the yield curve, and while many have already dismissed the traditional signaling of yield curve inversion to imply recession potential, it’s often after the curve has normalized that economic hardship may show.
Nonetheless, as the Fed has continued to cut rates, 10-year yields have continued their incline and last week saw yields tilt above 4.74%, which has been a waymark of sorts over the past year-and-change. There were retracements in equities in April of last year and leading into October of the year before, in both instances as 10-year yields were rising fast and to that level.
So far today we’re seeing a bit of pullback in that theme, but the big question is whether this morning’s CPI data, which, again, was pretty high with headline at 2.9% YoY – is fueling a rush of buying activity into Treasury notes? It seems more likely that this is a short-cover type of scenario after CPI didn’t increase at a blistering pace. And this seems tied to the move that’s showed in stocks.
So, whether either move can continue, the sell-off in bonds and stocks and the related rise in yields, will need to see follow-through confirmation.
Yield on 10-Year Treasury Notes
 Chart prepared by James Stanley; data derived from Tradingview
--- written by James Stanley, Senior Strategist
SPX, Yields Talking Points:
- U.S. markets are putting in big moves on the morning after the release of U.S. CPI data for the month of December.
- Headline CPI printed at the expectation of 2.9% YoY but Core CPI came in a touch below the expectation, printing at 3.2% v/s the 3.3% that was expected. But – that did go in the direction of the PPI miss yesterday that gives hope for FOMC rate cuts later in the year.
- The move across markets has been intense so far, with 10-year yields dropping by 14 bps and SPX catching a strong bid to extend the rally from the election gap that finished earlier this week.
- The question now is whether the pullback in stocks is over or whether sellers come in ahead of a 6k re-test. I look into this below.
Bulls are back in a big way for U.S. equities, and this stands in stark contrast to the sell-off from last week.
This Monday saw SPX gap down to finish off the election gap and that’s around where support started to play-in at 5782. While yesterday’s daily candle finished red for the index, it also finished higher than the Monday close after that daily bar had gapped-higher, and that move was driven by the softer PPI readings that came out ahead of the bell yesterday.
But tension remained as can be seen by the intra-day pullback yesterday, and the wait was for CPI data that released this morning. While the data didn’t come in below the expectation as much as the PPI data a day prior, it also didn’t beat expectations and this fueled hope that we may, in fact, get rate cuts in at some point this year.
It’s still early, however, and the CPI data from this morning wasn’t exactly a major positive for rate cut hopes, as headline CPI printed at 2.9% on a year-over-year basis and that’s against last month’s 2.7% reading and the 2.4% level that printed in September. So, inflation is still pushing higher, even if the actual print didn’t come out above the expectation.
And Core CPI did come out softer than the expectation, but the delta was slight, with year-over-year CPI printing at 3.2% against the 3.3% expected and that was the same level that printed in Core CPI in August and September releases of last year. That then led to three consecutive months at 3.3% and then this month showed a slight decline.
To sum, the CPI release wasn’t a clear sign that inflation is slowing to the point where the Fed can push another cut in March and given the massive response that’s shown in both bonds and stocks, it seems as though there’s a short-cover move taking place. This, of course, can turn into the initial seeds of a rally but the big question now is whether buyers come in to defend higher-low supports to allow for that next test of the 6k handle that bulls haven’t been able to do much above yet.
The daily chart of SPX below is updated from yesterday’s webinar and there’s a couple levels of note for buyers to defend. A support hold in the 5881-5888 level would be construed as bullish, as buyers would not allow for a fill of today’s opening gap. Below that, 5827, or the top of the election gap, is another level where support holds would bring a bullish bias. And then below that, it’s the 5827-5842 zone that’s of note, as this goes from last week’s close to the bottom of today’s opening gap.
SPX, S&P 500 Four-Hour Chart
Chart prepared by James Stanley; data derived from Tradingview
SPX Bigger Picture
Bullish equities after a pullback was my top trade idea for 2025, and the election gap was the first zone of support that I was tracking which has already come into play.
But the big question now is whether that can last and I think the answer for that derives back to bonds, which I’ll look at in a moment. But – from the daily chart of SPX we had a fresh lower-low print to start this week and it’s not until we take out the prior lower-high, around the 6k level, that we can say that the trend on the daily has started to shift. Until then, this is a possible lower-high and bulls should remain cautious of possible reversal setups, unless one of the above support zones come into play.
SPX Daily Price Chart
Chart prepared by James Stanley; data derived from Tradingview
Bonds
U.S. Treasury yields have been on a steep incline since the election. And I’ve read a number of possible reasons for that and perhaps some of them are true. But, what’s notable is the context with which this has taken place, as 10-year yields have risen by as much as 120 basis points since just before the Fed kicked off a rate cut cycle.
That’s helped to normalize the yield curve, and while many have already dismissed the traditional signaling of yield curve inversion to imply recession potential, it’s often after the curve has normalized that economic hardship may show.
Nonetheless, as the Fed has continued to cut rates, 10-year yields have continued their incline and last week saw yields tilt above 4.74%, which has been a waymark of sorts over the past year-and-change. There were retracements in equities in April of last year and leading into October of the year before, in both instances as 10-year yields were rising fast and to that level.
So far today we’re seeing a bit of pullback in that theme, but the big question is whether this morning’s CPI data, which, again, was pretty high with headline at 2.9% YoY – is fueling a rush of buying activity into Treasury notes? It seems more likely that this is a short-cover type of scenario after CPI didn’t increase at a blistering pace. And this seems tied to the move that’s showed in stocks.
So, whether either move can continue, the sell-off in bonds and stocks and the related rise in yields, will need to see follow-through confirmation.
Yield on 10-Year Treasury Notes
Chart prepared by James Stanley; data derived from Tradingview
--- written by James Stanley, Senior Strategist
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.

Equity Indices Q4, 2026 Outlook: Cracks Begin to Show
There's still an open door for a melt-up in the S&P 500 and Nasdaq but the Dow and Russell 2000 are looking more vulnerable, and until calm hits the Treasuries market there's a higher probability for volatility. The big question is whether that's a next quarter theme or not.
S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.