



Stocks Slump Over Easing Lockdown Uncertainties
Wall Street ended lower after Fauci and the Fed set a sombre tone. Risk aversion then spilled into Asia and is setting the path for a lower start in Europe.
Share this:
Wall Street ended lower after Fauci and the Fed set a sombre tone. Risk aversion then spilled into Asia and is setting the path for a lower start in Europe.
US Health official Anthony Fauci warned that reopening the US economy too quickly could in fact delay the road to recovery. His comments served as a reminder of the uncertainties that still lay ahead not just for the US economy as it attempts to navigate the easing of restrictive lockdown measures, but for global economies as they attempt the same.
US Health official Anthony Fauci warned that reopening the US economy too quickly could in fact delay the road to recovery. His comments served as a reminder of the uncertainties that still lay ahead not just for the US economy as it attempts to navigate the easing of restrictive lockdown measures, but for global economies as they attempt the same.
UK slowly reopens
Today the UK will start to take small steps to reopen the economy. Real estate market will reopen, people are encouraged to return to work if they can’t work from home and unlimited outdoor exercise is permitted. Despite, these moves the fact that the Chancellor has extended the furlough programme through to October means that the government is expecting this crisis to last, with any return to normality expected to take months. With this in mind the FTSE’s 25% rally from it March low looks overdone.
Today the UK will start to take small steps to reopen the economy. Real estate market will reopen, people are encouraged to return to work if they can’t work from home and unlimited outdoor exercise is permitted. Despite, these moves the fact that the Chancellor has extended the furlough programme through to October means that the government is expecting this crisis to last, with any return to normality expected to take months. With this in mind the FTSE’s 25% rally from it March low looks overdone.
Retailers. restaurants fragile as spending collapses
Data is starting to lay bare the extent of the damage that coronavirus crisis is having. British retail sales plunged by 19.1% in April, the biggest fall ever recorded by the BRC. Whilst Barclaycard announced that credit card spending tanked by 36.5% as spending in restaurants, pubs and travel collapsed overnight. Online spending has also soared amid lockdown and social distancing measures. Non-essential online spending jumped 60%. The longer that these restrictive measures stay in place and non-essential retailers remain shut the more deeply entrenched these habits will become, endangering the already very fragile UK high street. Retailers could remain under pressure for some time yet.
Data is starting to lay bare the extent of the damage that coronavirus crisis is having. British retail sales plunged by 19.1% in April, the biggest fall ever recorded by the BRC. Whilst Barclaycard announced that credit card spending tanked by 36.5% as spending in restaurants, pubs and travel collapsed overnight. Online spending has also soared amid lockdown and social distancing measures. Non-essential online spending jumped 60%. The longer that these restrictive measures stay in place and non-essential retailers remain shut the more deeply entrenched these habits will become, endangering the already very fragile UK high street. Retailers could remain under pressure for some time yet.
UK GDP in focus
Today will see a slew of UK data released, including GDP, trade balance and industrial production. Expectations are for the GDP Q1 to show -2.5% contraction QoQ, and the more volatile monthly reading to reveal an 8% contraction reflecting the start of the lockdown. Whilst a weak number is expected to the reality of seeing that figure could still send jitters through the market, as the UK heads into what is expected to be the deepest recession in 300 years. The Pound is heading cautiously higher ahead of the release.
Powell speaks as negative rate speculation swirls
Today will see a slew of UK data released, including GDP, trade balance and industrial production. Expectations are for the GDP Q1 to show -2.5% contraction QoQ, and the more volatile monthly reading to reveal an 8% contraction reflecting the start of the lockdown. Whilst a weak number is expected to the reality of seeing that figure could still send jitters through the market, as the UK heads into what is expected to be the deepest recession in 300 years. The Pound is heading cautiously higher ahead of the release.
Powell speaks as negative rate speculation swirls
Looking ahead to the US session, full attention will be on Fed Chair Powell as he live streams a speech on economic issues amid swirling expectations that the Fed will eventually go negative on rates. After inflation dived -0.8% the most since the Great Depression, Trump was quick to jump on the negative rates bandwagon. So far, the Fed has pushed back against the idea citing the damage that it would cause the financial sector. Fed fund futures, on the other hand, see rates negative by this time next year. The dollar is holding steady ahead to Powell’s appearance.
FTSE levels to watch
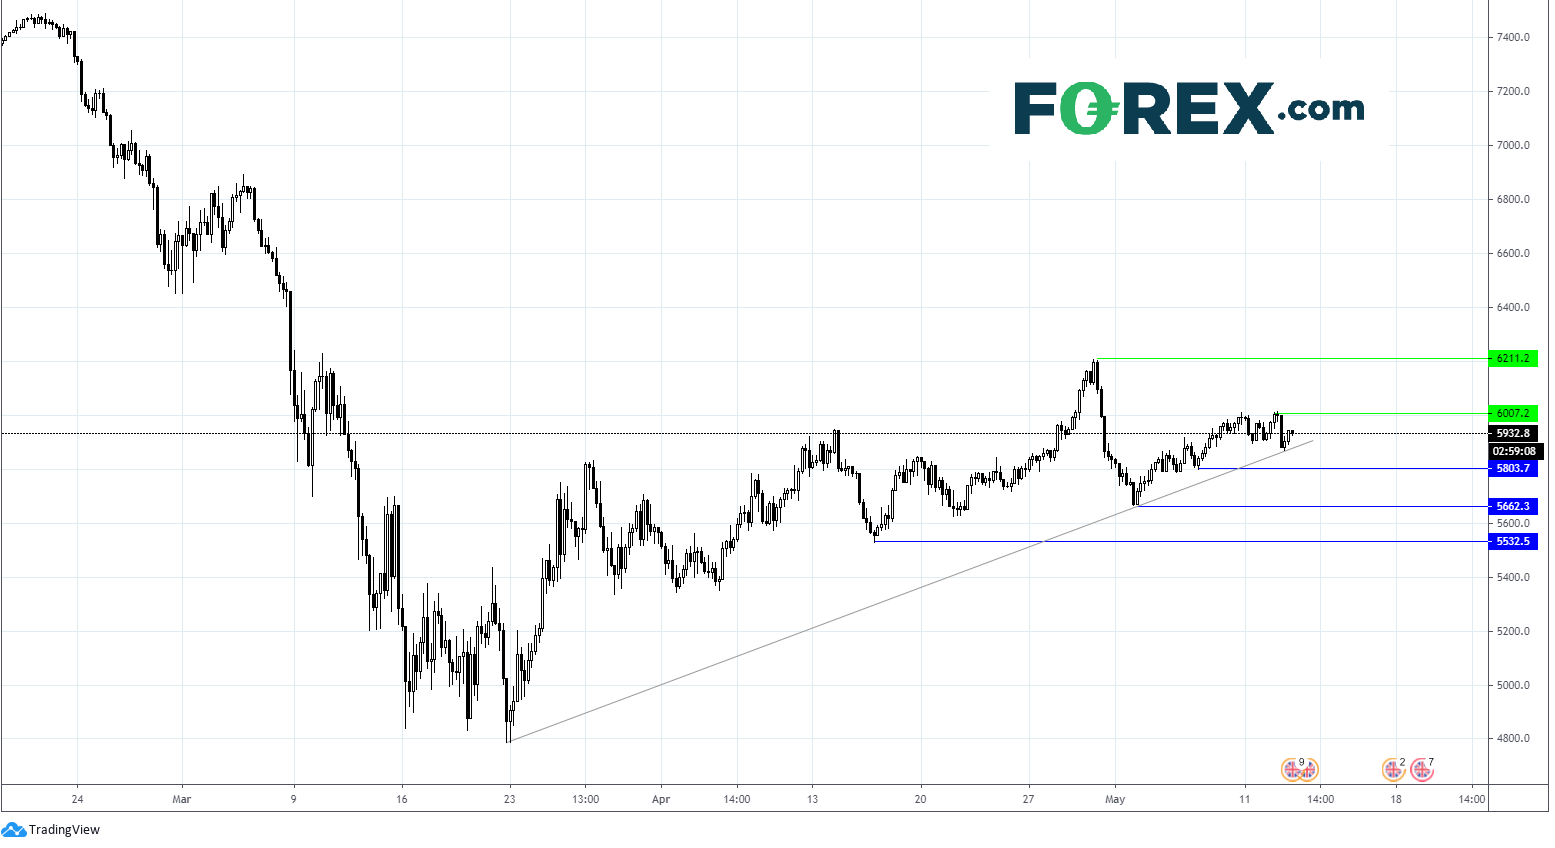
FTSE looking to open 60points lower, however bullish trend remains in tact.
Immediate resistance at 6000, key pscyological figure, prior to 6200 (high 30th April)
Support seen at 5875 (trendline) prior to 5800 (low 6th May) and 5666 (1st May).
FTSE looking to open 60points lower, however bullish trend remains in tact.
Immediate resistance at 6000, key pscyological figure, prior to 6200 (high 30th April)
Support seen at 5875 (trendline) prior to 5800 (low 6th May) and 5666 (1st May).
Wall Street ended lower after Fauci and the Fed set a sombre tone. Risk aversion then spilled into Asia and is setting the path for a lower start in Europe.
US Health official Anthony Fauci warned that reopening the US economy too quickly could in fact delay the road to recovery. His comments served as a reminder of the uncertainties that still lay ahead not just for the US economy as it attempts to navigate the easing of restrictive lockdown measures, but for global economies as they attempt the same.
US Health official Anthony Fauci warned that reopening the US economy too quickly could in fact delay the road to recovery. His comments served as a reminder of the uncertainties that still lay ahead not just for the US economy as it attempts to navigate the easing of restrictive lockdown measures, but for global economies as they attempt the same.
UK slowly reopens
Today the UK will start to take small steps to reopen the economy. Real estate market will reopen, people are encouraged to return to work if they can’t work from home and unlimited outdoor exercise is permitted. Despite, these moves the fact that the Chancellor has extended the furlough programme through to October means that the government is expecting this crisis to last, with any return to normality expected to take months. With this in mind the FTSE’s 25% rally from it March low looks overdone.
Today the UK will start to take small steps to reopen the economy. Real estate market will reopen, people are encouraged to return to work if they can’t work from home and unlimited outdoor exercise is permitted. Despite, these moves the fact that the Chancellor has extended the furlough programme through to October means that the government is expecting this crisis to last, with any return to normality expected to take months. With this in mind the FTSE’s 25% rally from it March low looks overdone.
Retailers. restaurants fragile as spending collapses
Data is starting to lay bare the extent of the damage that coronavirus crisis is having. British retail sales plunged by 19.1% in April, the biggest fall ever recorded by the BRC. Whilst Barclaycard announced that credit card spending tanked by 36.5% as spending in restaurants, pubs and travel collapsed overnight. Online spending has also soared amid lockdown and social distancing measures. Non-essential online spending jumped 60%. The longer that these restrictive measures stay in place and non-essential retailers remain shut the more deeply entrenched these habits will become, endangering the already very fragile UK high street. Retailers could remain under pressure for some time yet.
Data is starting to lay bare the extent of the damage that coronavirus crisis is having. British retail sales plunged by 19.1% in April, the biggest fall ever recorded by the BRC. Whilst Barclaycard announced that credit card spending tanked by 36.5% as spending in restaurants, pubs and travel collapsed overnight. Online spending has also soared amid lockdown and social distancing measures. Non-essential online spending jumped 60%. The longer that these restrictive measures stay in place and non-essential retailers remain shut the more deeply entrenched these habits will become, endangering the already very fragile UK high street. Retailers could remain under pressure for some time yet.
UK GDP in focus
Today will see a slew of UK data released, including GDP, trade balance and industrial production. Expectations are for the GDP Q1 to show -2.5% contraction QoQ, and the more volatile monthly reading to reveal an 8% contraction reflecting the start of the lockdown. Whilst a weak number is expected to the reality of seeing that figure could still send jitters through the market, as the UK heads into what is expected to be the deepest recession in 300 years. The Pound is heading cautiously higher ahead of the release.
Powell speaks as negative rate speculation swirls
Today will see a slew of UK data released, including GDP, trade balance and industrial production. Expectations are for the GDP Q1 to show -2.5% contraction QoQ, and the more volatile monthly reading to reveal an 8% contraction reflecting the start of the lockdown. Whilst a weak number is expected to the reality of seeing that figure could still send jitters through the market, as the UK heads into what is expected to be the deepest recession in 300 years. The Pound is heading cautiously higher ahead of the release.
Powell speaks as negative rate speculation swirls
Looking ahead to the US session, full attention will be on Fed Chair Powell as he live streams a speech on economic issues amid swirling expectations that the Fed will eventually go negative on rates. After inflation dived -0.8% the most since the Great Depression, Trump was quick to jump on the negative rates bandwagon. So far, the Fed has pushed back against the idea citing the damage that it would cause the financial sector. Fed fund futures, on the other hand, see rates negative by this time next year. The dollar is holding steady ahead to Powell’s appearance.

FTSE levels to watch
FTSE looking to open 60points lower, however bullish trend remains in tact.
Immediate resistance at 6000, key pscyological figure, prior to 6200 (high 30th April)
Support seen at 5875 (trendline) prior to 5800 (low 6th May) and 5666 (1st May).
FTSE looking to open 60points lower, however bullish trend remains in tact.
Immediate resistance at 6000, key pscyological figure, prior to 6200 (high 30th April)
Support seen at 5875 (trendline) prior to 5800 (low 6th May) and 5666 (1st May).




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
ASX 200 Rebound Stalls Despite Wall Street Surge
The ASX 200 rebound is struggling for traction despite a powerful Wall Street rally, leaving 8800 resistance and downside risks in focus.


Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.


Nasdaq 100 Forecast: Confidence Returns as the Index Challenges Record Highs
The trading week is getting underway with renewed bullish momentum across Nasdaq. This is reflected in today's session, where the index has gained more than 2.5%, highlighting a buying bias that has not been observed with this level of strength in several weeks.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.