




StoneX Bullion Report Launched
Our precious metals team have recently relaunched a new platform, ”StoneX Bullion”, tied to the successful US franchise, and providing a seamless global product within the precious metals markets. The website is https://stonexbullion.com/
Share this:
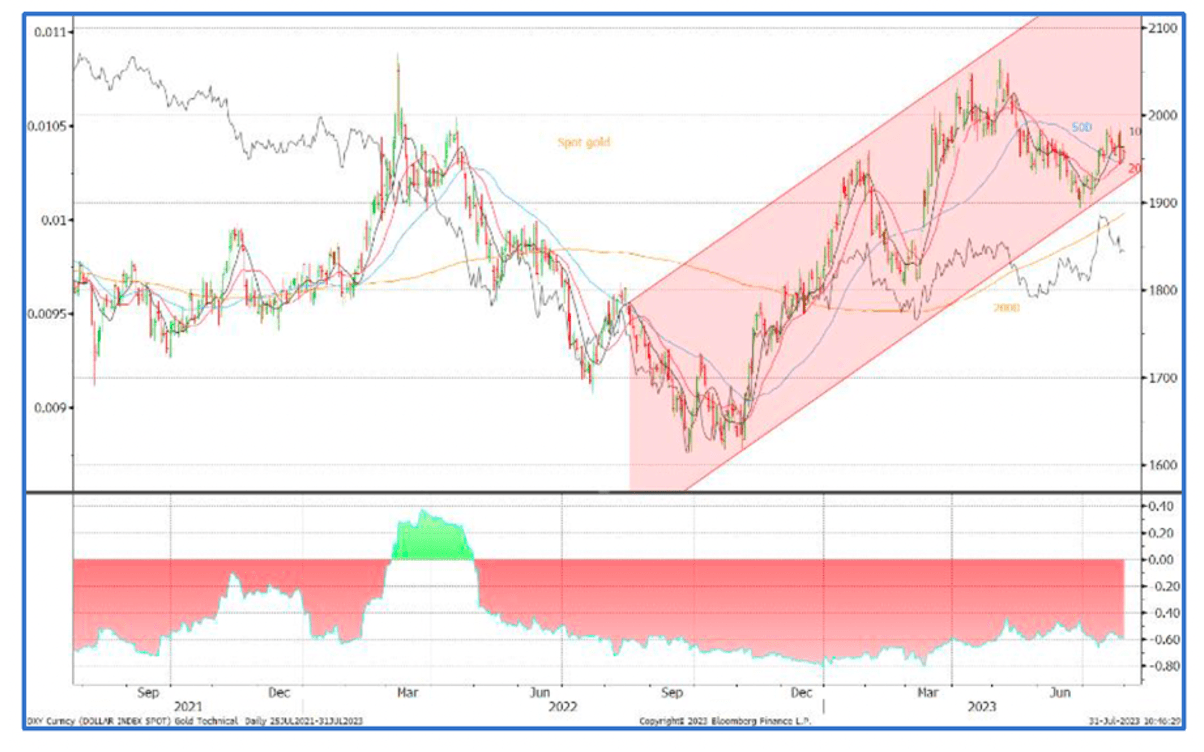
Gold barely responded to recent interest rate and inflation news out of the US in the past few weeks. The Fed dropped its reference to further rate rises this year, but Jay Powell kept the options open. European Central Bank guidance was fuzzy. The Bank of Japan began its first cautious steps away from a decades-long policy of quantitative easing. Gold appears to be trapped on a short-term technical basis in a trading range between $1,950 and $1,965.
Our precious metals team have recently relaunched a new platform, ”StoneX Bullion”, tied to the successful US franchise, and providing a seamless global product within the precious metals markets. The website is https://stonexbullion.com/
Gold technical and dollar relationship, two-year view
Source: Bloomberg, StoneX
Economic backdrop
Data on US inflation and spending numbers raised some fears of further interest rate hikes. Core Personal Consumption Expenditure, one of the Fed’s key parameters when framing policy, was actually slightly lower than the market consensus expectation, but at 4.1% annual rate it still points to a prolonged period of restrictive policy.
This tipped gold lower with the selling accelerated by the severance of key moving averages. Spot gold, which had previously been edging higher and testing $1,980, dropped smartly towards $1,950 before some fresh bargain hunting appeared.
As far as gold is concerned, economic data are still likely to put a cap on fresh strength, barring exogenous shocks. Were the US economy to tip into a recession in partial response to continued restrictive policy then this would be supportive as it would generate concerns and uncertainty.
Judging from the healthy personal spending numbers that were released at the same time as the PCE figures, that possibility currently looks relatively remote. The University of Michigan Sentiment Index, a closely watched gauge of consumer sentiment rose for the second month in succession, for the best reading since October 2021, with all components improving “considerably”, led by an 18% surge in long term business conditions, and a 14% gain in short-run business conditions.
While there was a glimmer of positive sentiment in the gold market two weeks ago, we are back to where we started. Gold continues to consolidate between $1,950 and $1,980. Silver is struggling to regain the $25 level.
Silver is posting a surplus this year that we currently estimate as equivalent to eight weeks’ global industrial demand and with investment demand still very anemic there is little prospect of a fundamentally-driven rally without either gold changing gear or an improvement in base metal sentiment. Neither of which look particularly encouraging at the moment.
Physical investment
The latest Commodity Futures Trading Commission (CFTC) figures, report on the period up to Tuesday 25th July, when gold had slipped from testing $1,985 and was hovering around $1,960, and silver was slipping from testing $25.25. Money Managers on COMEX added long gold positions for the third successive week, by 72 tonnes, or 19%, and reduced shorts by 30 tonnes, or 23%. This took the net long position to 359 tonnes from 256 tonnes.
Silver longs were trimmed, after a massive increase in longs the previous week, by 908 tonnes, or 11%, while shorts increased by 713 tonnes, or 18%. This took the net long position to 3,151 tonnes, down from 1,622 tonnes. Professional sentiment has been negative towards silver, and this have removed some of the speculative overhang, opening the path for further strength when the circumstances are right.
Gold suffered continued attrition in Exchange Traded Products (ETPs). Since the start of June there have been only four days out of 42 in which there were any ETP creations and tonnage has dropped by 80 tonnes, or 3%, to 3,393 tonnes. For comparison, global gold mine production is circa 3,700 tonnes. Silver has seen just 15 days of creation over the same period, for a loss of 526 tonnes, or 2%, to 22,770 tonnes. For comparison, global silver mine production is circa 25,600 tonnes.
For the time being gold is likely to continue to tread water and silver is expected to underperform because of an uncertain economic environment. Gold will do very little until we have the NonFarm payroll numbers from the States at the end of this week. A strong number will be bearish for gold; a weaker number will be supportive.
Gold and silver, five-year view
Source: Bloomberg, StoneX
Taken from analysis by Rhona O’Connell, Head of Commodity Market Analysis for EMEA & Asia, StoneX Financial Ltd.
Contact: [email protected].


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Gold Outlook: XAU/USD hit hard as US yields, dollar resume ascent
A stronger dollar, surging front-end yields and renewed geopolitical tension have combined to push gold back towards key technical support.


S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.