



Strong Data Offset By Rising US Coronavirus Numbers
European bourses are pointing to a move lower on the open as trading in the second half of the year gets underway.
Share this:
European bourses are pointing to a move lower on the open as trading the second half of the year gets underway. Improving economic data is being offset by rising coronavirus numbers in the US raising fears that the economic recovery could be knocked off its path before it even takes off.
Following on from strong US pending home sales and rebounding consumer confidence both stateside and in Europe, data showed that Chinese manufacturing activity gathered steam in June boosting optimism that the economic recovery in the world’s second largest economy is gaining traction. Chinese manufacturing PMI jumped to 51.2 in June, ahead of the 50.5 expected.
German retail sales surge
German retail sales smashed expectations in May, rebounding +13.9% after slumping -5.3% in April. This was well ahead of forecasts of 3.9%. The huge difference between the data print and the forecast goes to show just how difficult it is proving to be to gauge how the economic recovery is progressing. Without any doubt this 13.9% jump in retail sales represents pent up demand, however, we know that sentiment has been improving and consumers are not shying away from spending in the shops. The encouraging numbers hint towards the idea that maybe the downturn won’t be as harsh as initially feared, particularly in Europe
German retail sales smashed expectations in May, rebounding +13.9% after slumping -5.3% in April. This was well ahead of forecasts of 3.9%. The huge difference between the data print and the forecast goes to show just how difficult it is proving to be to gauge how the economic recovery is progressing. Without any doubt this 13.9% jump in retail sales represents pent up demand, however, we know that sentiment has been improving and consumers are not shying away from spending in the shops. The encouraging numbers hint towards the idea that maybe the downturn won’t be as harsh as initially feared, particularly in Europe
Rising US Covid-19 cases could knock recovery
However, the number of US coronavirus cases is also increasing at an alarming rate with 47,000 new cases a day, its biggest single increase since the outbreak began. The surge in cases in the US has dampened the equities rally in recent weeks as investors grow increasingly concerned that the rolling back of reopening measures or the return to full on lock down in parts of the country will knock the economy when it is already on its knees.
However, the number of US coronavirus cases is also increasing at an alarming rate with 47,000 new cases a day, its biggest single increase since the outbreak began. The surge in cases in the US has dampened the equities rally in recent weeks as investors grow increasingly concerned that the rolling back of reopening measures or the return to full on lock down in parts of the country will knock the economy when it is already on its knees.
Just how well the economic recovery is going will become more apparent today as investors await a barrage of economic data.

Data Deluge
UK and Eurozone manufacturing PMI’s are expected to confirm preliminary readings. Activity in the UK is expected at 50.1, just scrapping into expansion this month. The Eurozone activity remains below the 50 level that separates expansion from contraction, although at significantly slower pace
Looking ahead, US ISM manufacturing and non-manufacturing PMI data will provide further clues over the health of the US economy as lockdwn measures have eased. Both the manufacturing sector and the non-manufacturing sector are expected to show the pace of contraction slowing considerably.
ADP private payroll figures are expected to show a solid rebound. Payrolls are expected to jump 3 million, after slumping -2.7 million in the previous session. These will be closely eyed ahead of tomorrow’s non-farm payroll.
Any market reaction to stronger than forecast US data could be limited given the concerns surrounding rising covid-cases. Downbeat data could add to the negativity and drag equities sharply lower.
Dax chart
European bourses are pointing to a move lower on the open as trading the second half of the year gets underway. Improving economic data is being offset by rising coronavirus numbers in the US raising fears that the economic recovery could be knocked off its path before it even takes off.
Following on from strong US pending home sales and rebounding consumer confidence both stateside and in Europe, data showed that Chinese manufacturing activity gathered steam in June boosting optimism that the economic recovery in the world’s second largest economy is gaining traction. Chinese manufacturing PMI jumped to 51.2 in June, ahead of the 50.5 expected.
German retail sales surge
German retail sales smashed expectations in May, rebounding +13.9% after slumping -5.3% in April. This was well ahead of forecasts of 3.9%. The huge difference between the data print and the forecast goes to show just how difficult it is proving to be to gauge how the economic recovery is progressing. Without any doubt this 13.9% jump in retail sales represents pent up demand, however, we know that sentiment has been improving and consumers are not shying away from spending in the shops. The encouraging numbers hint towards the idea that maybe the downturn won’t be as harsh as initially feared, particularly in Europe
German retail sales smashed expectations in May, rebounding +13.9% after slumping -5.3% in April. This was well ahead of forecasts of 3.9%. The huge difference between the data print and the forecast goes to show just how difficult it is proving to be to gauge how the economic recovery is progressing. Without any doubt this 13.9% jump in retail sales represents pent up demand, however, we know that sentiment has been improving and consumers are not shying away from spending in the shops. The encouraging numbers hint towards the idea that maybe the downturn won’t be as harsh as initially feared, particularly in Europe
Rising US Covid-19 cases could knock recovery
However, the number of US coronavirus cases is also increasing at an alarming rate with 47,000 new cases a day, its biggest single increase since the outbreak began. The surge in cases in the US has dampened the equities rally in recent weeks as investors grow increasingly concerned that the rolling back of reopening measures or the return to full on lock down in parts of the country will knock the economy when it is already on its knees.
However, the number of US coronavirus cases is also increasing at an alarming rate with 47,000 new cases a day, its biggest single increase since the outbreak began. The surge in cases in the US has dampened the equities rally in recent weeks as investors grow increasingly concerned that the rolling back of reopening measures or the return to full on lock down in parts of the country will knock the economy when it is already on its knees.
Just how well the economic recovery is going will become more apparent today as investors await a barrage of economic data.
Data Deluge
UK and Eurozone manufacturing PMI’s are expected to confirm preliminary readings. Activity in the UK is expected at 50.1, just scrapping into expansion this month. The Eurozone activity remains below the 50 level that separates expansion from contraction, although at significantly slower pace
Looking ahead, US ISM manufacturing and non-manufacturing PMI data will provide further clues over the health of the US economy as lockdwn measures have eased. Both the manufacturing sector and the non-manufacturing sector are expected to show the pace of contraction slowing considerably.
ADP private payroll figures are expected to show a solid rebound. Payrolls are expected to jump 3 million, after slumping -2.7 million in the previous session. These will be closely eyed ahead of tomorrow’s non-farm payroll.
Any market reaction to stronger than forecast US data could be limited given the concerns surrounding rising covid-cases. Downbeat data could add to the negativity and drag equities sharply lower.
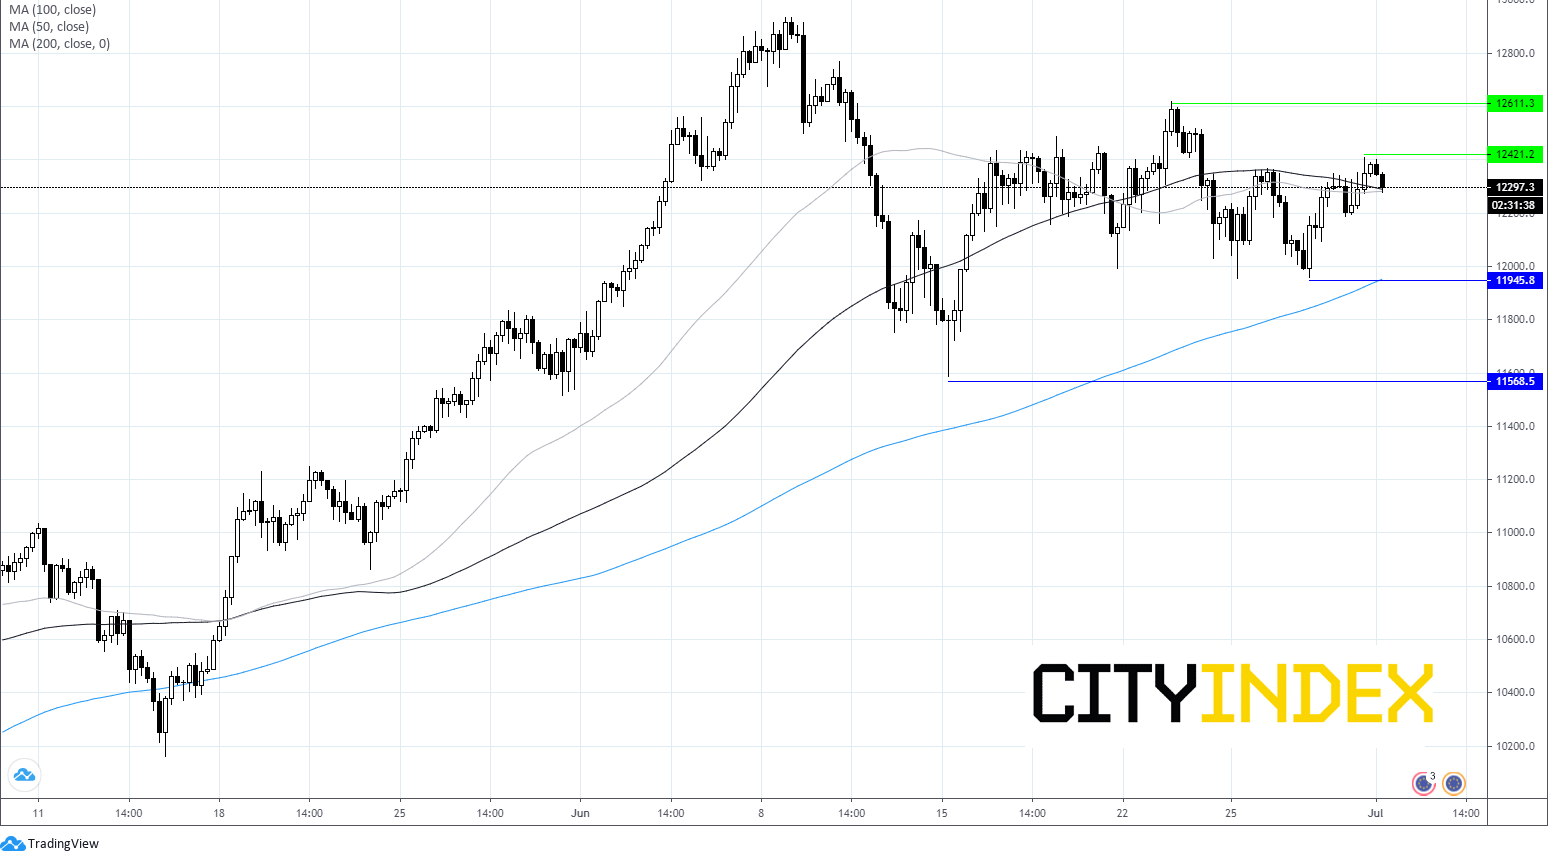
Dax chart
Related tags:




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
GBP/USD, DAX Forecast Two trades to watch 220926
GBP/USD struggles as UK government borrowing exceeds forecasts, putting pressure on Healey ahead of the Budget. DAX eases back after yesterday's gains as oil prices and political headwinds rise.

USD/JPY, DAX Forecast: Two trades to watch 150926
USD/JPY rises as U.S. Treasury yields rise above 5%. DAX slumps as bond rout continues and oil prices surge.

DAX, Crude oil forecast: Rising energy prices, yields threaten risk assets
Following a weak handover from Asia, European markets and US indices were under pressure this morning, as rising oil prices and elevated bond yields once again weighed on risk appetite. Among the major European indices, the German DAX will be in firm focus this week, with the ECB’s rate decision coming up on Thursday. That decision is likely to be a hike, as rising oil prices threaten to re-accelerate inflation.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.