




The Week Ahead: US inflation, BOC and RBNZ meetings take the helm
US inflation takes the centre stage next week for economic data, with the Bank of Canada (BOC) and Reserve Bank of New Zealand (RBNZ) also set to announce their monetary policy decisions.
Share this:

The Week Ahead: US inflation, BOC and RBNZ meetings take the helm
Just one week into the month, it’s already apparent that volatility does not intend to get back in its box (which is usually the norm this time of year). Investors are being keep on edge with increasingly inverted yield curves, hawkish comments from central bankers and definitely strong economic data from the US justifying the Fed’s hawkish stance. Janet Yellen is currently treading eggshells in China, where one wrong stop could get messy - and have strong ramifications for global sentiment next week and beyond. As for economic data, US CPI takes the centre stage, with the Bank of Canada (BOC) and Reserve Bank of New Zealand (RBNZ) also set to announce their monetary policy decisions.
The week that was:
- Global bond yields continued to rise and their curves invert (where the short-term rate rise faster than the longer-term and push the spread into negative territory) as investors remain increasingly concerns about the global economy
- The FOMC minutes were more hawkish than traders were expecting, with the decision to pause in June not as ‘unanimous’ as originally suggested as “some members” supported a 25bp hike “almost all members” are on board for further hikes
- US economic data was also very strong overall ahead of NFP data, which saw ADP employment print nearly 500k jobs, layoffs fall and ISM services PMI expand faster than expected (with rising new orders, business activity and employment)
- However, US manufacturing sector continued to deteriorate with the ISM survey contracting at it fastest pace since the pandemic, with employment also falling alongside new orders
- PMI surveys across China, Europe and the US continue to weaken
- China’s services PMI was the latest of its series to disappoint, expanding at its slowest pace in five months and down -3.5 points m/m
- The RBA delivered their second pause of their tightening cycle in July, although warned that “inflation is still too high” and that “some further monetary policy tightening may be required”
- Sino-US relations took another step backwards as China warned that their decision to curb the export of metals used in semiconductors are “just the start”, ahead of US Treasury Secretary Janet Yellen’s visit to Beijing
The week ahead (calendar):
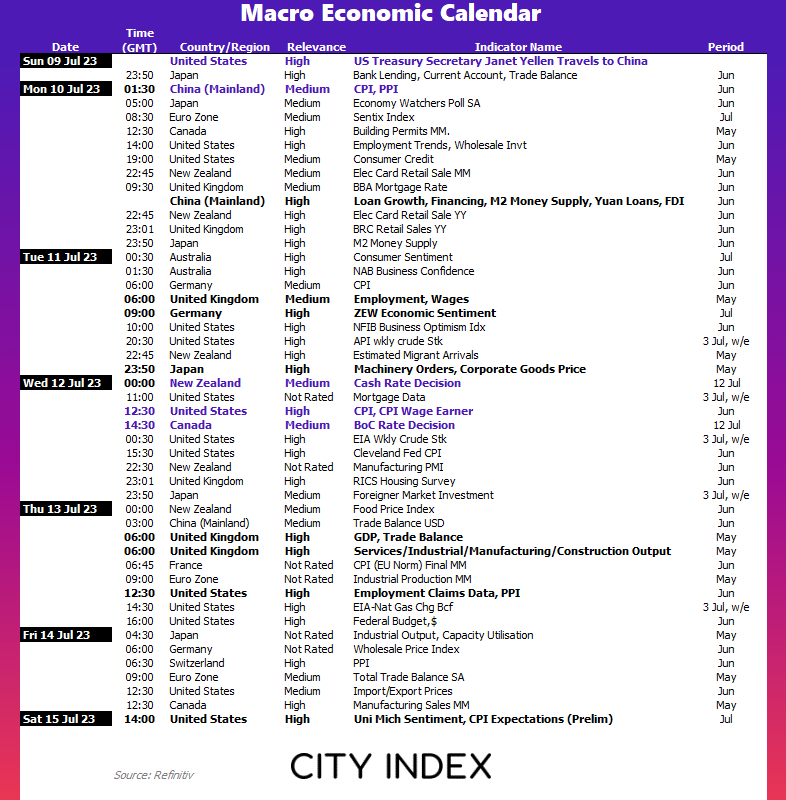
Central Bank members to speak: Time (GMT)
- 14:30 - Fed's Daly
- 15:00 - Fed's Mester
- 16:00 - Fed's Bostic
- 3:10 - RBA Governor Lowe
- 13:45 - Fed's Kashkari
- 15:00 - BOC's Macklem and Rogers
- 20:00 - Fed's Mester to Speak
This content will only appear on City Index websites!
Earnings This Week
Look at the corporate calendar and find out what stocks will be reporting results in Earnings This Week.
The week ahead (key events and themes):
- US inflation
- Janet Yellen’s trip to China
- BOC and RBNZ cash rate decisions
- China inflation
- Inflation expectations
US inflation
PCE inflation data came softer than expected last week, which saw traders jump back on to the ‘short dollar’ trade and further reduce the odds of any Fed hikes beyond July. Well, Jerome Powell has since said that two more consecutive hikes could be coming, the FOMC minutes were more hawkish than expected and US data overall has been definitely strong to justify at least another couple of hikes. And that puts next week’s inflation data back on the radar (not that it ever really left it).
Whilst headline inflation was soft in June’s report and services inflation showed signs of moderating, rents remained stubbornly high. It’s unlikely we’ll see inflation spike higher, but it if was to then we’d expect USD buying to come back in full force. By the same token, it would likely take much softer inflation figures to dampen the excitement (or fear) of the hawkish Fed that employment data is justifying. But we can at least expect volatility to dry up in the lead up to the headline calendar event, and quickly return when the data is released.
Market to watch: EURUSD, USD/JPY, WTI Crude Oil, Gold, S&P 500, Nasdaq 100, Dow Jones
Janet Yellen’s trip to China
Relations between US and China are back in the reverse gear with both remained in a tit-for-tat approach over trade restrictions, mostly around technology and in particular microchips. AI is the new space race, and both are doing their best to stimmy the other’s effort to succeed. So it will be interesting to see what, if anything, US Treasury Secretary Janet Yellen can achieve in her visit to China. She arrived on Thursday and spoke to China’s ambassador for a “frank and productive discussion”, but with topics such as national security Ukraine and Taiwan on the agenda, the ramifications of the visit could indeed make an impact next week and beyond.
Market to watch: USD/CNH, USD/JPY, S&P 500, Nasdaq 100, Dow Jones, VIX, AUD/JPY
BOC cash rate decision
Like the RBA, the BOC also surprised markets with a 25bp hawkish hike in their June meeting. Those two decisions, alongside a 50bp hike from the BOE and warnings of another couple of hike from the Fed knocked sentiment as traders realised they had been complacent with their expectations for peak cycles.
A Reuters poll shows that 83% of economists back another 25bp hike on Wednesday and that it could be their last this cycle. Money markets seem less convinced with the 1-month OIS (overnight index swap) suggesting just a 48% chance of a hike, although the 3-month suggests an 80% chance. But with their statement explicitly saying that “excess demand in the economy looks to be more persistent than anticipated” and “concerns have increased that CPI inflation could get stuck materially above the 2% target”, we suspect a hike is more probable, even if recent inflation data did come in softer than expected. And a strong employment report later today could bolster bets that a hike is more probable than not.
Market to watch: USD/CAD, CAD/JPY, NZD/CAD,
RBNZ cash rate decisions
New Zealand’s central bank are my favourite central banks amongst the respective FX majors, as they do not mince their words and are not to come out swinging as and when required. They were the first major central bank to begin hiking (South Korea’s take the title for the first CB overall to begin this cycle), although expectations are for them to finally pause tightening on Wednesday. Their own forecasts pencilled in the current rate of 5.5%, inflation is expected to continue falling, demand is dwindling and NZ has since entered a technical recession. Whilst we see little room for a surprise at this meeting, we’ve learned to never drop out guard when the RBNZ is concerned – and that can prompt decent levels of volatility on NZD and AUD pairs.
Market to watch: AUD/USD, NZD/USD, AUD/NZD, NZD/JPY, AUD/JPY, ASX 200
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Australian Dollar Outlook: AUD/USD Rally Stalls as Fed Risk Returns
AUD/USD momentum fades as Fed hike expectations return, while RBA officials keep September tightening risks firmly in focus.
Australian Dollar Outlook: AUD/USD Eyes May High Ahead of US CPI
AUD/USD holds above 72c as traders weigh rising Fed hike bets, US CPI, Treasury yields and a potential test of its year-to-date high.
Australian Dollar Outlook: AUD/USD Bears Tighten Grip with 60s in Sight
AUD/USD broke below 71c after strong US jobs data revived Fed hike bets, while signs are growing that the RBA may have reached peak rates.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.