





The Week Ahead: PCE inflation, euro CPIs and China PMIs in focus
We’re heading into the weekend with some risk-off volatility across Asian markets, as traders respond to the 50bp BOE and (well-grounded) concerns that central banks globally are not yet done with their tightening cycles. That means economic data remains as important as ever as investor as we head into next week, which includes PCE inflation for the US, flash PMIs across Europe and official PMI data for China.
Share this:
We’re heading into the weekend with some risk-off volatility across Asian markets, as traders respond to the 50bp BOE and (well-grounded) concerns that central banks globally are not yet done with their tightening cycles. That means economic data remains as important as ever as investor as we head into next week, which includes PCE inflation for the US, flash CPIs across Europe and official PMI data for China. We also have central bank titans (Powell, Lagarde, Bailey and Ueda) on a panel at the ECB Forum on Central Banking 2023, which covers “macroeconomic stabilisation in a volatile inflation environment”. Riveting stuff!
The week that was:
- It was a risk-off tone as we headed into the back of the week, with the growing realisation that central banks are far from done with hiking interest rates
- Jerome Powell testified in front on congress on Wednesday and Thursday and warned that the Fed will likely have to hike rates again
- As there was nothing substantially new compared to his recent FOMC press conference, the US dollar traded lower and markets continued to favour an additional 25bp hike in July
- UK inflation continued to rip higher with core CPI rising to a 31-year high on the even of the BOE’s meeting, which saw money markets fully price in five hikes from 4.5%
- The BOE hiked by 50bp (consensus was 25bp) which increases the odds of the UK entering a prolonged recession, and markets are betting on several more hikes to follow in this cycle
- The SNB hiked by 25bp and markets now expect another 25bp hike to arrive in September
- Odds for another BOC hike were on the rise following Canada’s hot retail sales report, which sent USD/CAD to a 9-month low on Wednesday
- The RBA minutes kept the threat of further interest rate hikes alive and well, market markets latched on to the ‘finely balanced’ debate between a pause and a hike and send AU and AU yields sharply lower
- The Australian Treasurer announced on national radio that they intend to finalise the appointment of the next RBA governor by July
The PBOC cut their 1-year LPR (Loan prime rate) by 10bps to try and help prop up China’s weakening economy
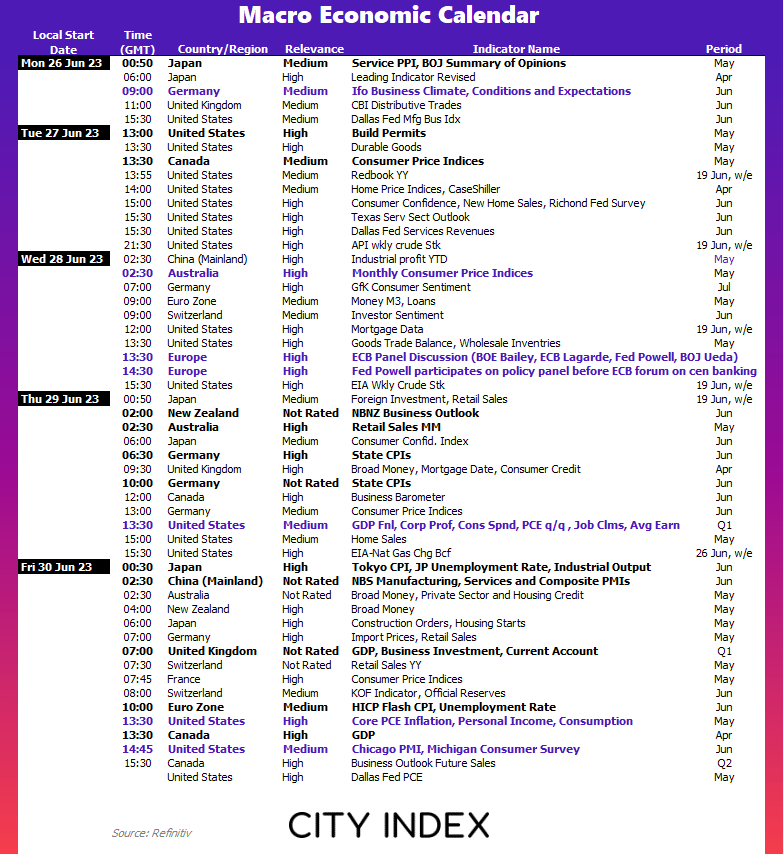
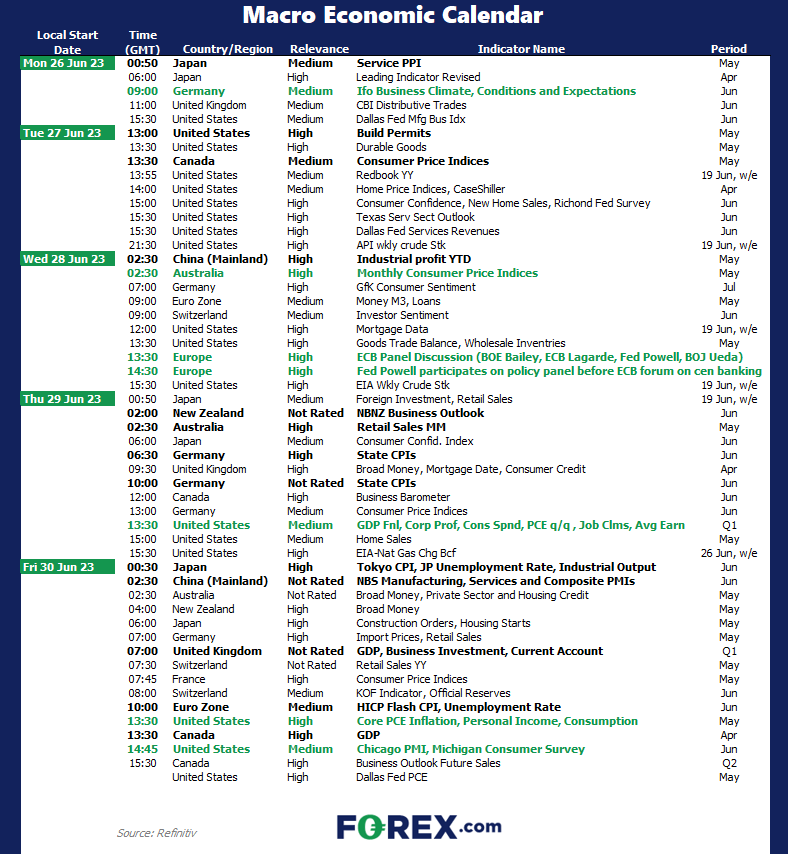
The week ahead (calendar):
Earnings This Week
Look at the corporate calendar and find out what stocks will be reporting results in Earnings This Week.
The week ahead (key events and themes):
- ECB Forum on Central Banking 2023
- US core PCE inflation and US GDP
- European data (CPI, confidence)
- China’s PMIs
- Australian inflation
- Canadian inflation
- Tokyo CPI
ECB Forum on Central Banking 2023
The annual ECB forum on central banking takes pace in Sintra, Portugal between 26-28 June, with the baulk of key speeches scheduled throughout Tuesday and Wednesday. Whether or not it turns out to be a market moving event remains to be seen, but traders will likely keep an eye on who says what during the policy panel on Wednesday at 14:30 CET-1, as the panel includes none other than Fed Chair Jerome Powell, ECB President Christine Lagarde, Bank of Japan Governor Ueda and Bank of England Governor Andrew bailey. Given the concerns surrounding recessions and high interest rates in a low-growth environment, we expect every word to be scrutinised.
Markets to watch: EUR/USD, USD/JPY, EUR/JPY, GBP/USD, GBP/JPY, EUR/GBP, WTI crude oil, S&P 500, Nasdaq 100, Dow Jones Industrial
US PCE inflation and GDP data
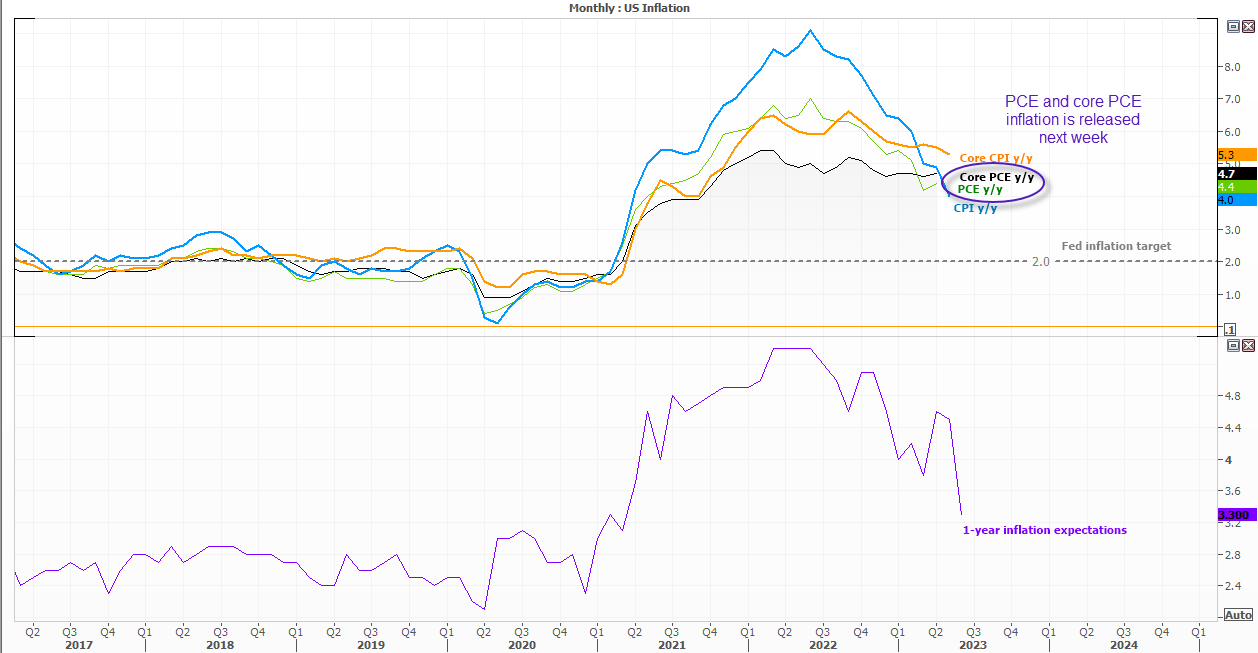
Over the past week or so we have seen various measures of US consumer inflations and CPI fall in tandem. Traders are now keen to see if PCE inflation (the Fed’s preferred gauge) follows suit.
We know that the general rate of inflation has peaked in the US, as it has in many other economies (barring the UK…). Yet it remains stubbornly high, and Fed Chair Jerome Powell is telling us that more hikes are coming. But if the rate of inflation slows faster than anticipated, money markets will be more convinced that another 50bp of Fed hikes seems unlikely and weigh on the US dollar accordingly. Of course, the caveat here is that inflation surprises to the upside and markets scramble to reprice the more hawkish scenario, send the dollar higher and weigh on its peers and appetite for risk in general.
Whilst the GDP is the final report, any downward revisions to growth, corporate profits or consumer spending could fan fears that we’re nearing (or already within) a recession, given the risk-off tone for some markets.
Markets to watch: EUR/USD, USD/JPY, WTI crude oil, S&P 500, Nasdaq 100, Dow Jones Industrial
Canadian inflation report on Tuesday
The BOC delivered a hawkish hike earlier this month, and a hot retail sales report for Canada this week serves as a reminder that demand remains strong and inflation too high. Especially when we have seen the RBA hike, ECB, SNB and BOE since hike whilst the Fed continue to speak of further hikes. Unless we see a material weakness in Canada’s inflation report on Tuesday, we could see an increase in bets for another BOC (Bank of Canada) hike and a higher Canadian dollar as a consequence.
Markets to watch: USD/CAD, CAD/JPY, Brent
Inflation data for Europe and IFO business sentient for Germany
The IFO business sentiment survey is released for Germany at the start of the week, where investors will want to see if conditions have deteriorated further. The ZEW survey has provided the lead, and now IFO is turning lower. Clearly, lower business sentiment is not ideal for growth, but it could be a source of deflation.
Flash CPI reports for Europe and its constituents are released throughout the week. But state level inflation for Germany can also prompt decent marker reactions for euro pairs and bonds as it can provide a lead for eurozone CPI and shift expectations for ECB policy. Whilst not exactly top-tier stuff, German import prices may also provide some reprieve to consumer price expectations if they cone in soft enough.
Markets to watch: EUR/USD, EUR/JPY, DAX
China PMIs (purchase managers index)
Central authorities for China continue to add stimulus to support an economy that is losing steam. We have seen keep interest rates cut,… yet trade data PMIs etc remain underwhelming. Perhaps this week’s PMIs will surprise to the upside and restore some faith that the government’s 5% GDP target for 2023 remains feasible. A soft data set will tell us what we already know, but any notable disappointment could be a case of ‘bad news is good’ as markets rally on anticipated stimulus.
Market to watch: AUD/USD, AUD/JPY, USD/CNH, Hang Seng, China A50
Australian CPI report
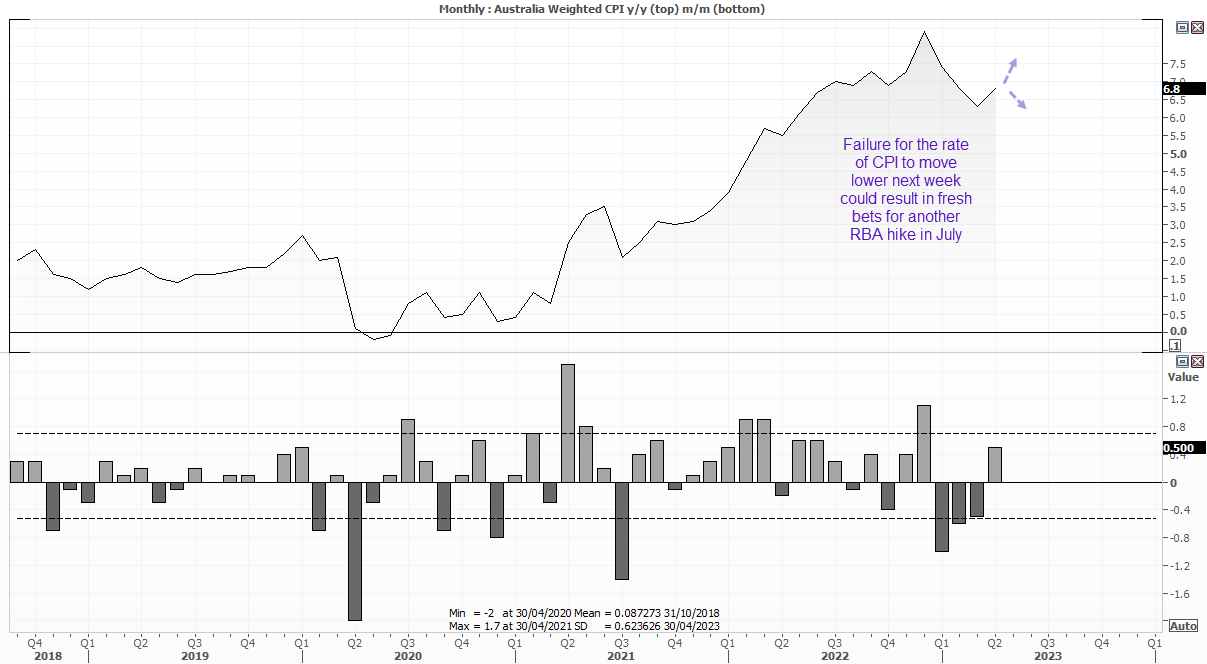
Like the BOC, the RBA also delivered a hawkish 25bp hike and caught the consensus off guard for a second consecutive meeting. Yet markets deemed the June meetings as dovish due to the debate between a pause or hike in June as ‘finely balanced’, sending AUD pairs and AU bond yields lower on the day. Whilst some were seemingly positioned for a hawkish surprise within the minutes, they still look more hawkish than dovish to my eyes. And that means that Wednesday’s inflation report likely needs to come in very soft for the RBA to not hike again in August, given the BOE have since hiked by 50bp and the Fed continue to hint at one or two more.
Tokyo CPI
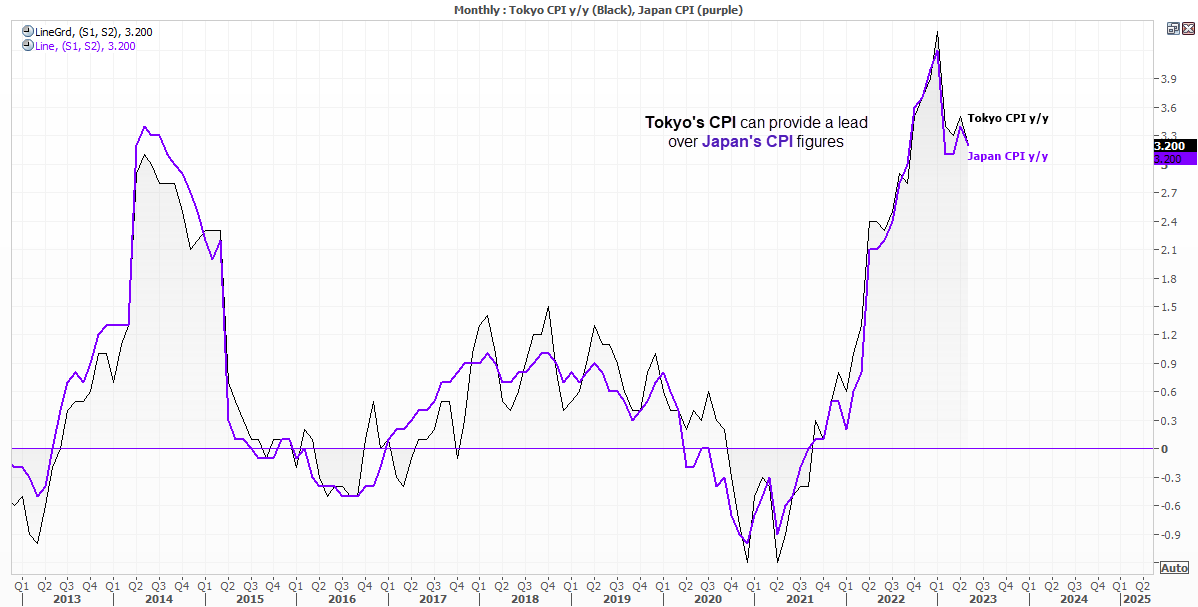
We’re torn when it comes to data from Japan because, despite much of it exceeding expectations, the BOJ are in no hurry to abandon years of stubbornly ultra-dovish policies. But then we also have the fear that if we look away, we could miss the straw that breaks the camel’s back and sees a sudden repricing of expectations and volatile reaction form the yen. If we’re to see an upside surprise for Japan’s nationwide inflation, it will appear on Tokyo’s data first. So whilst Friday’s CPI report may amount to nothing, it’s probably worth a look - just in case.
Market to watch: USD/JPY, Nikkei 25
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Australian Dollar Outlook: AUD/USD Holds 70c Ahead of RBA and CPI
AUD/USD faces an expected RBA hike and Australian CPI before attention turns to US PCE, ISM and nonfarm payrolls later in the week.
Australian Dollar Outlook: AUD/USD Rally Stalls as Fed Risk Returns
AUD/USD momentum fades as Fed hike expectations return, while RBA officials keep September tightening risks firmly in focus.
Australian Dollar Outlook: AUD/USD Eyes May High Ahead of US CPI
AUD/USD holds above 72c as traders weigh rising Fed hike bets, US CPI, Treasury yields and a potential test of its year-to-date high.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.