



Weekly Equities Outlook: Alphabet, Tesla, Intel
US earnings season turns towards tech.
Share this:
Alphabet Q2 Earnings Preview
Google parent Alphabet is due to report Q2 2026 earnings after the market closes on July 22, with investors focusing on three key themes: Google Cloud growth, AI spending, and the progress of Gemini.
Wall Street expects revenue of $116.8 billion, up 21% year-on-year, broadly matching the pace of growth seen in Q1. Earnings per share are forecast to come in at $2.87, representing 24.2% annual growth.
Google Cloud remains Alphabet's primary growth engine and is expected to be the main driver of investor sentiment. Cloud revenue grew 63% in Q1, while the backlog almost doubled from the previous quarter to more than $460 billion, highlighting robust demand for cloud computing and AI services. Investors will be looking for signs that this momentum is continuing. Ultimately, the key question is whether AI is generating enough growth in Google Cloud to justify Alphabet's aggressive investment strategy.
AI spending will also remain firmly in focus. Alphabet has been investing heavily in data centres and AI infrastructure to support future growth. Capital expenditure more than doubled year-on-year to $35.7 billion in the first quarter, and management expects to invest between $180 billion and $190 billion during 2026. While these investments are designed to strengthen Alphabet's competitive position, they have also weighed on free cash flow, leaving investors looking for evidence that they are beginning to generate meaningful returns. Positive commentary around the company's AI strategy could support the share price, while another step up in capital expenditure may unsettle investors.
Gemini will be another major talking point. Google's AI platform has made solid progress over the past two quarters, narrowing the gap with OpenAI and Anthropic. Gemini's mobile user base rose 295% year-on-year to 118 million users, while ChatGPT remains the market leader with 441 million daily active users, although growth has largely plateaued since May. Investors will be looking for further signs that Gemini 3.5 Pro is gaining traction and helping Google capture AI market share.
Overall, analysts maintain a positive view on Alphabet. The stock carries a Strong Buy consensus rating, with 29 Buy recommendations and 5 Holds over the past three months. The average analyst price target stands at $435, implying around 17.5% upside from current levels.
How to Trade Alphabet Earnings
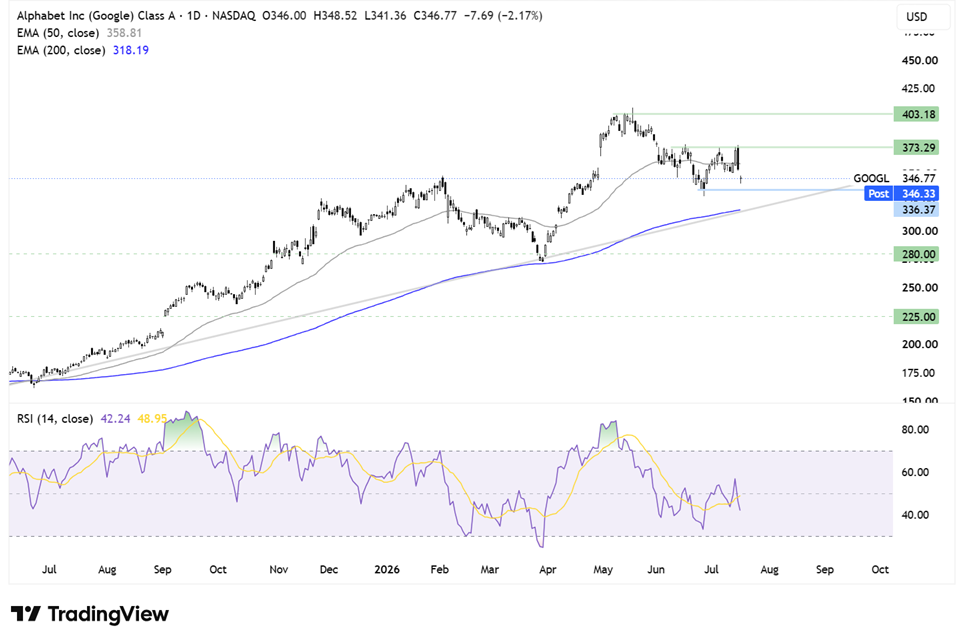
Alphabet continues to trade above its 200-day EMA and long-term rising trendline, keeping the broader trend constructive. However, after failing to hold above the $400 record high, the share price has pulled back and now trades below the 50-day EMA, suggesting the near-term technical picture has weakened.
With the RSI below 50, sellers will look for a move towards $340, the June low. A break below this level would expose the 200-day EMA and rising trendline support around $317.
On the upside, buyers would first need to reclaim the 50-day EMA near $360. A move above this level would bring $373, the July and June 15 swing highs, into focus before attention turns back to the $400 record high.
Tesla Q2 Earnings Preview
Tesla is due to report Q2 earnings after the market closes on July 22.
Wall Street expects revenue of $25.31 billion and earnings per share of $0.50.
Tesla has already reported stronger-than-expected Q2 deliveries of 480,126 vehicles, comfortably beating consensus forecasts by around 18%. The key question now is whether those stronger deliveries translated into revenue growth without sacrificing profitability.
The delivery beat comes at a time when Tesla's core EV business has faced growing concerns over slowing demand and intensifying competition. However, the stronger delivery figures suggest those concerns may have been overstated.
Margins could prove to be the key swing factor for the earnings report. Investors remain concerned that aggressive price cuts and incentives used to stimulate demand may have squeezed profitability. Gross margin deterioration has been one of Tesla's biggest headwinds in recent quarters, meaning weaker margins could offset the positive impact of stronger deliveries.
Beyond the core automotive business, Tesla's longer-term growth story continues to broaden.
The rollout of its robotaxi service continues, with operations expanding into Miami, while its energy storage division is steadily emerging as another high-margin growth business. Progress on Full Self-Driving and Optimus also continues to support the longer-term investment case, highlighting that Tesla's future increasingly extends beyond electric vehicles alone.
Wall Street's consensus rating remains Hold. If Tesla delivers healthy margins alongside encouraging updates on its emerging growth businesses, the shares could respond positively. However, disappointing margins or renewed concerns surrounding valuation could weigh on the stock.
How to Trade Tesla Earnings
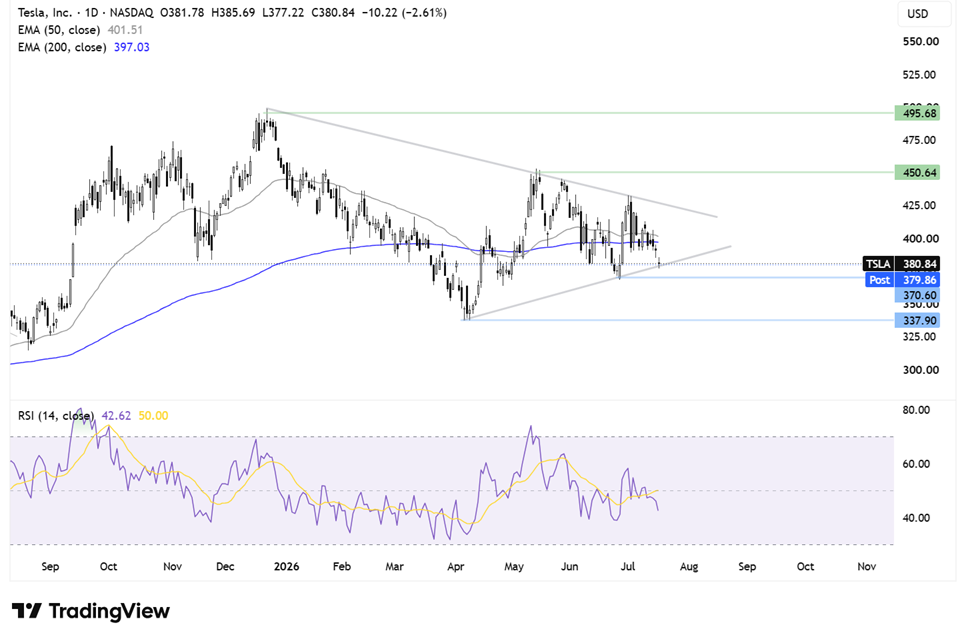
Tesla continues to trade within a symmetrical triangle pattern.
The share price failed at falling trendline resistance around $425 before pulling back, breaking below both the 50-day and 200-day EMAs and testing the rising trendline support.
A break below this support would expose the June low at $368, opening the door towards the 2026 low at $337.
Should the trendline hold, buyers would first need to reclaim the 200-day EMA around $400. A move above this level would bring the falling trendline resistance near $427 into focus before attention turns towards $450.
Intel Q2 Earnings Preview
Intel is due to report Q2 earnings after the market closes on July 23.
Wall Street expects earnings per share of $0.10, compared with a loss of $0.26 a year earlier. Revenue is forecast to rise to $14.41 billion, representing 12% annual growth.
The key driver this quarter is expected to be Intel's Data Center and AI business, which is forecast to deliver its strongest sequential revenue growth in a decade as AI-related demand continues to accelerate.
While Nvidia dominates the AI GPU market, growing AI workloads also require high-performance CPUs, networking infrastructure and advanced packaging, areas where Intel is also well positioned.
Custom AI processors represent another important growth opportunity. Intel's custom AI chip business has now surpassed $1 billion in annual revenue, providing another avenue for future expansion.
However, supply constraints remain a potential headwind. Although demand appears robust, manufacturing capacity limitations and inventory shortages could restrict near-term revenue growth.
How to Trade Intel Earnings
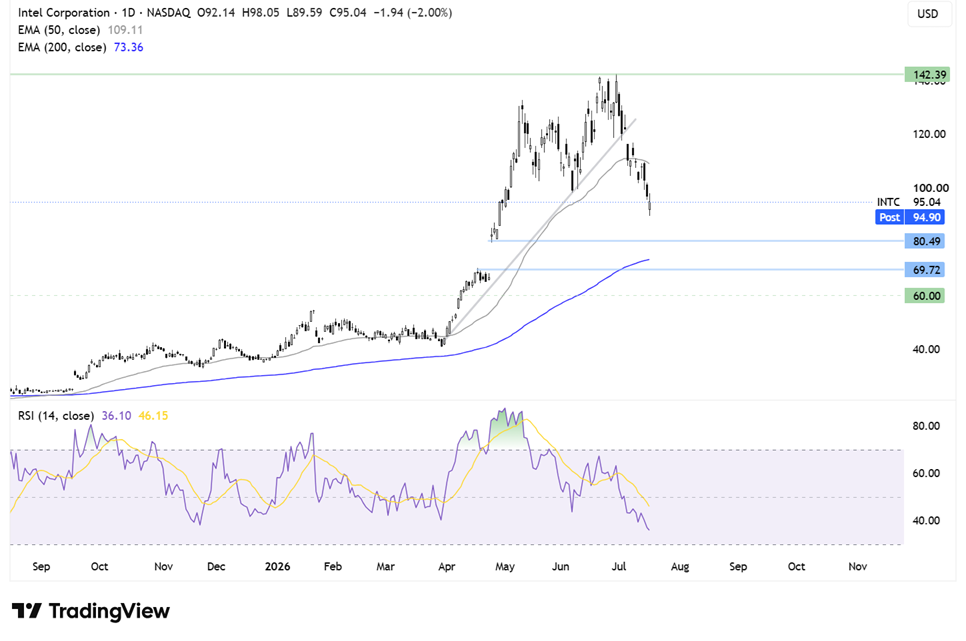
Intel failed to hold above its record high around $142 before pulling back sharply, breaking below its rising trendline and the 50-day EMA to a low of $89.50.
With the RSI below 50, the technical picture continues to favour sellers.
A break below $80, the April 27 low, would expose the 200-day EMA at $73.30, before bringing the $70 support level into focus.
To improve the outlook, buyers would first need to reclaim the 50-day EMA, with a move back above the broken trendline helping to signal that bullish momentum is returning.
Related tags:




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P 500, Nasdaq, Dow Forecast: Wall Street Split Widens Into Month-End 9 26 2026
Nasdaq strength contrasts with mounting Dow pressure as rising Treasury yields raise the stakes for stocks heading into the monthly close.

Weekly Equities Outlook: Nike, Micron Technology, Carnival Corp.
Earnings from Nike comes as the share price trades at a 12-year low. Micron Technology keeps the AI trade in focus and Carnival suffers from rising fuel costs.

Weekly Equities Forecast: Costco, JD Sports & Strategy
Earnings Costco, JD Sports report earnings and crypto stocks are in focus with after Friday's SEC announcement which boosted BTC.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.