




will there be another ruble rout 934572015
<p>Back in Jan/ Feb the Ruble was under attack, USDRUB reached a record high of nearly 80.00, causing intervention from Russian officials and hasty rate […]</p>
Share this:

Back in Jan/ Feb the Ruble was under attack, USDRUB reached a record high of nearly 80.00, causing intervention from Russian officials and hasty rate hikes to stem the decline in the currency. Things calmed down for the RUB over the next few months, however, it started to drift higher in June, as US dollar strength gathered pace, and the RUB has been the worst performer in the emerging market FX space this week.
The sharp 3% fall in the RUB on Friday was triggered by the 50 basis point cut in interest rates by the Russian central bank. The central bank has been cutting rates in recent months to erode the negative economic effects of hiking rates to 17% at the start of the year to halt the previous slide in the RUB.
Why cut rates?
The decision to cut rates again today comes on the back of weak economic data, wages have been falling, retail sales are slumping and business investment is at a 6 year low. Q1 GDP slumped by 2.2%, and the future does not look good for growth for the rest of this year.
The central bank has had to weigh up the risks of cutting interest rates to try and boost the economy, with the weakening RUB and rising inflation. For now growth seems to be the bigger priority, as inflation is currently an eye wateringly high 15.3%, which hasn’t been helped by the decline in the currency.
Russia bucks the trend:
Interestingly, the Russian authorities have bucked the trend by cutting rates, after Brazil hiked the Selic rate by 50 basis points to 14.25% earlier this week to stem the decline in BRL. The rate hike has helped to stem USDBRL strength, but the impact has been limited so far and there could be pressure on the Brazilian authorities to step back in to the market and prop up the BRL in the coming weeks.
Where does this leave Russia?
If we continue to see RUB weakness then we think that the Russian authorities may have no choice but to reverse its recent dovish stance and start hiking interest rates once more. As we mentioned, the RUB has been the weakest performer in the emerging market FX space this week and we expect the decline to continue. The RUB could get punished further for the Bank of Russia’s unwillingness to follow the lead of countries like Brazil and support its currency.
The RUB faces the same pressures as it did back in January: the prospect of a Fed rate rise making Russia’s external debt load more expensive, and a lower oil price threatening the long term economic health of the country. With Brent crude prices back at April levels, the latter point remains a major cause of concern, and if the Fed does hike rates in September then it could add even more downward pressure to the RUB.
The technical view:
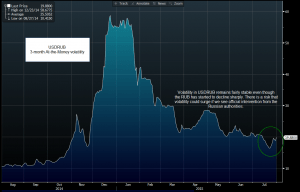
Interestingly, USDRUB volatility has managed to stay fairly stable around the 20 mark during this latest bout of RUB weakness (see figure 1). This could be because the market for USDRUB options is fairly quiet, however we would expect volatility to pick up sharply in the coming days and for the price of protection against further RUB declines to rise.
From a technical perspective, USDRUB is already above the major moving averages, and momentum seems to be on the side of the RUB bears. The daily range in USDRUB widened sharply in recent days, which suggests that there could be further downside for the RUB. When there is a risk of panic selling in a currency, it is worth looking for the big psychological levels that may slow down the decline. For USDRUB that includes 65.00 – the high from 23rd Feb, and then 70.00 – the 2nd Feb high.
As we mention above, if we continue to see the RUB decline then the risk of official intervention increases. If the Russian authorities step into the market and buy RUB or the central bank reverses course and starts hiking interest rates (the latter is more likely in our view), then we could see a sharp short-term relief rally in RUB, back to the 55.00 area – a cluster of simple moving average support (as you can see in figure 2).
Takeaway:
- The RUB is once again under attack after the central bank cut interest rates on Friday.
- USDRUB is at its highest level since March, the pace of gains has picked up in the last two days suggesting that panic RUB selling could be back in vogue in the EM FX world.
- We believe that the Russian central bank will be forced to intervene to stem the decline in the RUB in the coming days/ weeks, and rates may have to rise.
- If there is intervention then expect USDRUB volatility to soar, and a short term, relief rally in RUB. 55.00 – is a key level of support for USDRUB.
Figure 1:
Source: City Index Data: Bloomberg
Figure 2:
Source: City Index Data: Bloomberg
Related tags:



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.