



S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
Share this:
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies. Against this backdrop, our S&P 500 forecast remains tilted to the downside in the near-term outlook.
Why are the market struggling?
The backdrop is becoming increasingly difficult for US and indeed global stocks. On Wall Street, market breadth has deteriorated sharply, bond yields are breaking higher and concerns about the US fiscal position are resurfacing, just as expectations of further Federal Reserve tightening are building. With fewer stocks doing the heavy lifting, the risk of a more meaningful correction has increased.
The weakness in risk assets has gathered pace over the past few sessions, as last week’s post-FOMC bounce has faded. Higher interest-rate expectations, elevated oil prices and a stronger dollar have combined to take some of the air out of the rally. I was never particularly convinced that equities could remain comfortably supported against such a challenging macro backdrop in the first place, but things could potentially get worse before they get better.
Wednesday’s move was particularly telling. The main catalyst was the sharp sell-off in the bond market, with yields breaking higher across the curve. Some stronger-than-expected US data and hawkish comments from Fed officials added to the pressure.
Trump-Xi summit matters, but the bond market matters more
The meeting between Donald Trump and Xi Jinping will command attention today, but it may not be the most important driver of markets. Any agreement to extend the existing trade truce would probably be mildly supportive for risk appetite, although much of that outcome appears to be anticipated already. Progress on artificial intelligence and related technology restrictions could also be welcomed.
The bigger issue is what is happening in the Treasury market.
As long as crude oil remains elevated, the combination of inflation concerns, a stronger dollar and higher Treasury yields is likely to keep pressure on risk assets. The US 10-year yield has surged above 5 per cent this week, while the 30-year yield is testing levels last seen around the 2007 highs.
Higher long-term yields raise the opportunity cost of owning growth stocks and other low- or zero-yielding assets like gold and silver. If yields continue to climb, the pressure on equity valuations is likely to intensify.
Market breadth is flashing warning signs
The weakness in breadth is another reason yesterday’s sell-off should not have come as a major surprise.
The S&P 500’s return towards record highs had increasingly been driven by a relatively narrow group of stocks, particularly the hyperscalers and semiconductor names that have carried much of the market’s gains.
As of Tuesday’s close, 52 per cent of S&P 500 constituents were trading below their 200-day moving averages, according to MarketWatch. That is an unusually weak level of participation for an index sitting, at the time, within 1 per cent of a record high.
Indeed, the last time the market displayed a similar combination of weak breadth and proximity to a record was around March 2000, at the peak of the dotcom bubble.
There is another worrying statistic. MarketWatch has highlighted that as of Monday, roughly 60 per cent of S&P 500 stocks were more than 20 per cent below their all-time highs.
None of this means the current market is about to repeat 2000. But it does highlight how narrow the rally has become. Add widening credit spreads and rising nominal Treasury yields to the equation, and the foundations underneath the index look considerably less comfortable than the headline level suggests.
Technical S&P 500 forecast and levels to watch
From a technical analysis perspective, the S&P 500 remains in a bullish trend and most of the important support levels are still intact. So, at this stage, there is no definitive confirmation that the market has peaked.
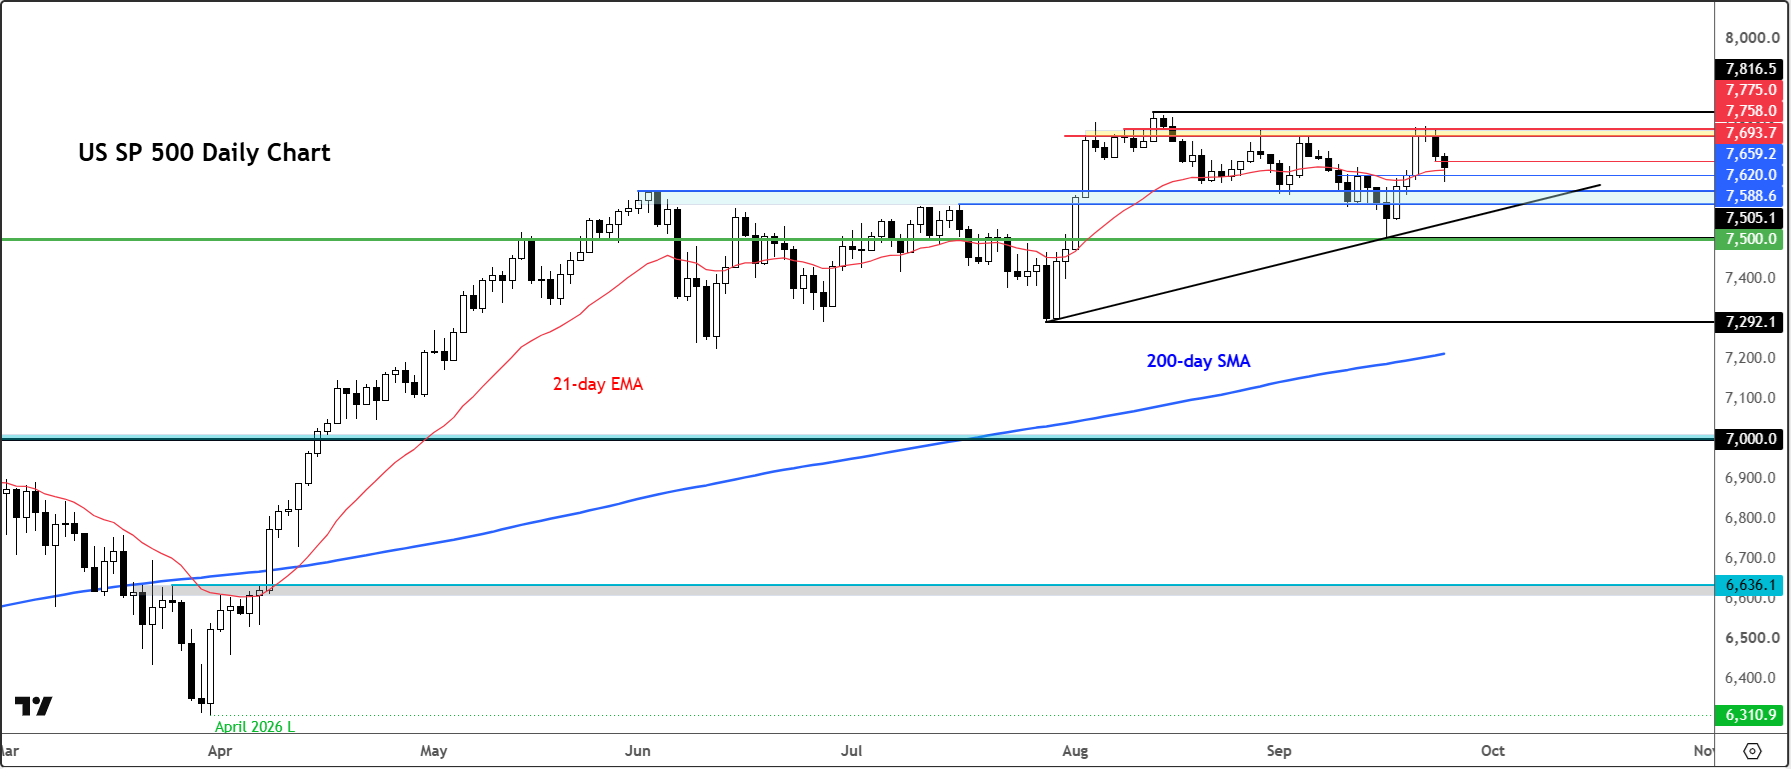
There is, however, a growing warning sign. Our SPX 500 index, which is derived from the underlying S&P 500 futures, has tested the 7,755 to 7,775 area several times without managing to break through decisively. That repeated failure raises the prospect that we may have seen at least a near-term peak.
Similar price action has occurred in the past before the market eventually pushed through resistance, so a renewed attempt at the highs cannot be ruled out. But the macro backdrop is deteriorating, although technically I would still want to see more evidence before declaring the broader uptrend over.
The immediate test is around 7,588-7620, which represents an important short-term support zone.
Below that, 7,505 becomes important. This was the most recent swing low. That is the line in the sand for me tactically. A decisive break would materially weaken the technical picture and increase the likelihood of a deeper correction.
In that scenario, the index could break below 7,500, opening the door towards the summer lows around 7,292.
There could ultimately be scope for an even deeper retracement, but there is little point in getting ahead of the market.
For now, the question is whether the S&P 500 can stabilise above these nearby support levels — or whether the deteriorating macro backdrop finally forces a more meaningful technical break.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.