European Open GBP Steady ahead of GDP USD Rises into CPI
‘Big Six’
The first of the U.S. big six banks will report second quarter (Q2) earnings on Friday, offering the latest insight into whether major U.S. lenders have sustained the strong pace of profit growth seen over the last few quarters.
The very biggest U.S. bank, JPMorgan will report at the end of this week, together with Wells Fargo and Citigroup. Goldman Sachs, Morgan Stanley and Bank of America, will release Q2 figures on 18th July. Here, we outline key themes to look out for, together with a few specifics for Friday’s batch of results.
Trumped
Once regarded as ‘Trump Trade’ stocks par excellence, due to their place at the heart of the new administration’s plans to cut taxes and financial regulation, big lenders’ prospects became less certain when those hopes faded as the White House’s troubles mounted. But after a late-February to mid-April wobble, bank shares kept rising. They were up around 24% on aggregate this week since 8th November, as shown in the rebased chart of the S&P 500 Financial index below.
Figure 1 – S&P 500 Financial index: 8th Nov 2016 to date (rebased)
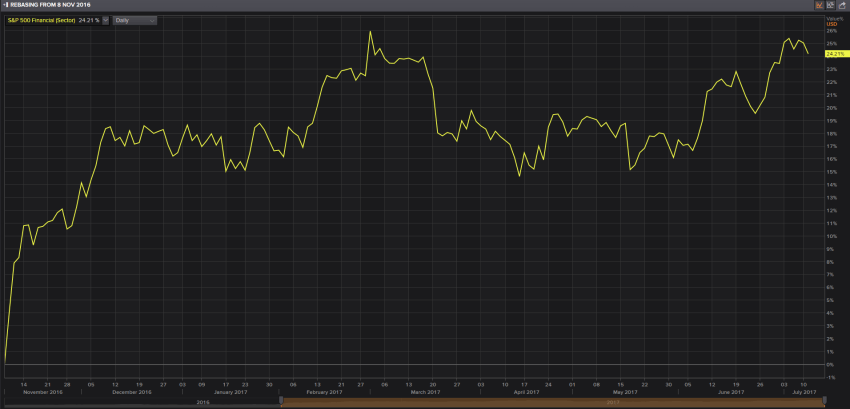
Source: Thomson Reuters and City Index
Rated
Three further Federal Reserve interest rate rises since December 2015’s have revived borrowing costs, resulting in an eight basis point lending margin rise in Q1. If it holds across the sector, U.S. banks could net an additional $11bn of interest income per year, according to data from bank researcher Autonomous. Despite halting progress most recently, general U.S. economic improvement has also underpinned big banks.
The deal
Dealogic’s analytics platform this week shows the large U.S. banks back in the top five spots for global announced M&A advisory in the year to date. Goldman remains number one and Citi has leapt four places to number two. In equity deals, whilst the 92% rise year-on-year in Q1 for global IPOs looks difficult to sustain, a stronger year-on-year pace is still likely for Q2. At $16.1bn, Q1 proceeds were already close to the total for the whole of 2016, when a paltry $18.8bn was raised, the lowest in 7 years, looking at Renaissance Capital’s annual IPO report.
Flattening
On the negative side, the key near-term risks for big U.S lenders also relate to financial and economic conditions. Recent yield curve gyrations may play havoc. The U.S. five-year and 30-year curve reached 93.10 basis points late last month, the flattest since 2007. In recent weeks curves have begun to normalise, though Q2 interest margins may already have been impacted.
Revenue views
The outlook for bank revenue growth also looks flat for now. Mature North American and Western markets are continuing to cap growth. With the retrenchment of recent years over, forays by the big banks into faster-growing emerging markets ought to aid top lines, but these have much further to run. Some large banks have already warned investors not to expect another unusually profitable quarter for trading.
What to watch
Almost all U.S. lenders passed the Federal Reserve’s latest and toughest ‘stress test’ last month, satisfying the Fed’s condition for increased dividends and share buybacks. With balance sheet growth still largely constrained by a fragile yield curve – ‘capital optimisation’ – AKA share buybacks — could step up a gear. Citigroup announced within hours of the test result that it would double its quarterly dividend and hike buybacks by $15.6bn to $18.9bn over a year. The rest of the largest six can be expected to at least turn up the notch to some degree.
On other fronts though, differing share price returns so far this year underline differing expectations. Goldman, down 4% and Wells Fargo up barely 1%, have apparently been marked by investors. Goldman is still nursing a discount after failing to benefit from the recent rise in trading revenues. Its fund management outflows so far this year, estimated at $26bn, easily the worst by any global manager monitored by Morningstar, are another potential pressure. Wells, the least exposed to trading, is still dealing with the aftermath of last year’s sales scandal. It warned in June that new credit card account openings have been hit.
Still, as the table below shows, sizeable profit growth is only expected at Bank of America and JPMorgan in Q2, seldom the year’s strongest quarter for banks. Revenues are forecast to be little changed. Low expectations could therefore enable strongly positive share price reactions if expectations are exceeded. JPMorgan in particular has garnered a reputation for beating expectations. My colleague Kathleen Brooks pointed out this week that 6 of its last 8 quarterly earnings were above Wall Street forecasts.
Table 1 – Earnings and revenue forecasts
| Bank Name | Earnings Forecasts (rounded; $) | Revenue Forecasts (rounded; $) | ||||
| Q2 2017 EPS Estimate | Q2 2016 Reported | Q2 YoY Estimate Growth | Q2 2017 Estimate (billions) | Q2 2016 Actual Reported (billions) | Q2 YoY Estimate Growth | |
| Goldman Sachs Group Inc. | 3.40 | 3.72 | -8.5% | 7 | 8 | -5.9% |
| Citigroup Inc. | 1.21 | 1.24 | -2.6% | 17 | 18 | -0.9% |
| Wells Fargo & Co | 1.01 | 1.01 | 0.3% | 22 | 22 | 1.2% |
| Morgan Stanley | 0.76 | 0.75 | 2.0% | 9 | 9 | 1.8% |
| Bank of America Corp | 0.43 | 0.37 | 4.6% | 21 | 21 | 1.2% |
| JPMorgan Chase & Co | 1.59 | 1.55 | 2.5% | 24 | 25 | -1.6% |
Source: Thomson Reuters and City Index
The information on this web site is not targeted at the general public of any particular country. It is not intended for distribution to residents in any country where such distribution or use would contravene any local law or regulatory requirement. The information and opinions in this report are for general information use only and are not intended as an offer or solicitation with respect to the purchase or sale of any currency or CFD contract. All opinions and information contained in this report are subject to change without notice. This report has been prepared without regard to the specific investment objectives, financial situation and needs of any particular recipient. Any references to historical price movements or levels is informational based on our analysis and we do not represent or warranty that any such movements or levels are likely to reoccur in the future. While the information contained herein was obtained from sources believed to be reliable, author does not guarantee its accuracy or completeness, nor does author assume any liability for any direct, indirect or consequential loss that may result from the reliance by any person upon any such information or opinions.
Futures, Options on Futures, Foreign Exchange and other leveraged products involves significant risk of loss and is not suitable for all investors. Losses can exceed your deposits. Increasing leverage increases risk. Spot Gold and Silver contracts are not subject to regulation under the U.S. Commodity Exchange Act. Contracts for Difference (CFDs) are not available for US residents. Products and services available depend on your location and the entity holding your account. Before deciding to trade forex, commodity futures, or digital assets, you should carefully consider your financial objectives, level of experience and risk appetite. Any opinions, news, research, analyses, prices or other information contained herein is intended as general information about the subject matter covered and is provided with the understanding that we do not provide any investment, legal, or tax advice. You should consult with appropriate counsel or other advisors on all investment, legal, or tax matters. References to FOREX.com or GAIN Capital refer to StoneX Group Inc. and its subsidiaries. Please read Characteristics and Risks of Standardized Options.
Please note that foreign exchange and other leveraged trading involves significant risk of loss. It is not suitable for all investors and you should make sure you understand the risks involved, seeking independent advice if necessary.
FOREX.com is a trading name of GAIN Global Markets Inc. which is authorized and regulated by the Cayman Islands Monetary Authority under the Securities Investment Business Law of the Cayman Islands (as revised) with License number 25033.
FOREX.com may, from time to time, offer payment processing services with respect to card deposits through StoneX Financial Ltd, Moor House First Floor, 120 London Wall, London, EC2Y 5ET.
GAIN Global Markets Inc. has its principal place of business at 30 Independence Blvd, Suite 300 (3rd floor), Warren, NJ 07059, USA., and is a wholly-owned subsidiary of StoneX Group Inc.
© FOREX.COM 2026