




A Lot Riding On The Fed
The calm before the storm. Asia traded muted overnight, Europe is pointing to a mildly mixed start and the FX markets are subdued ahead of Jerome Powell taking to the virtual stage at Jackson Hole.
Share this:

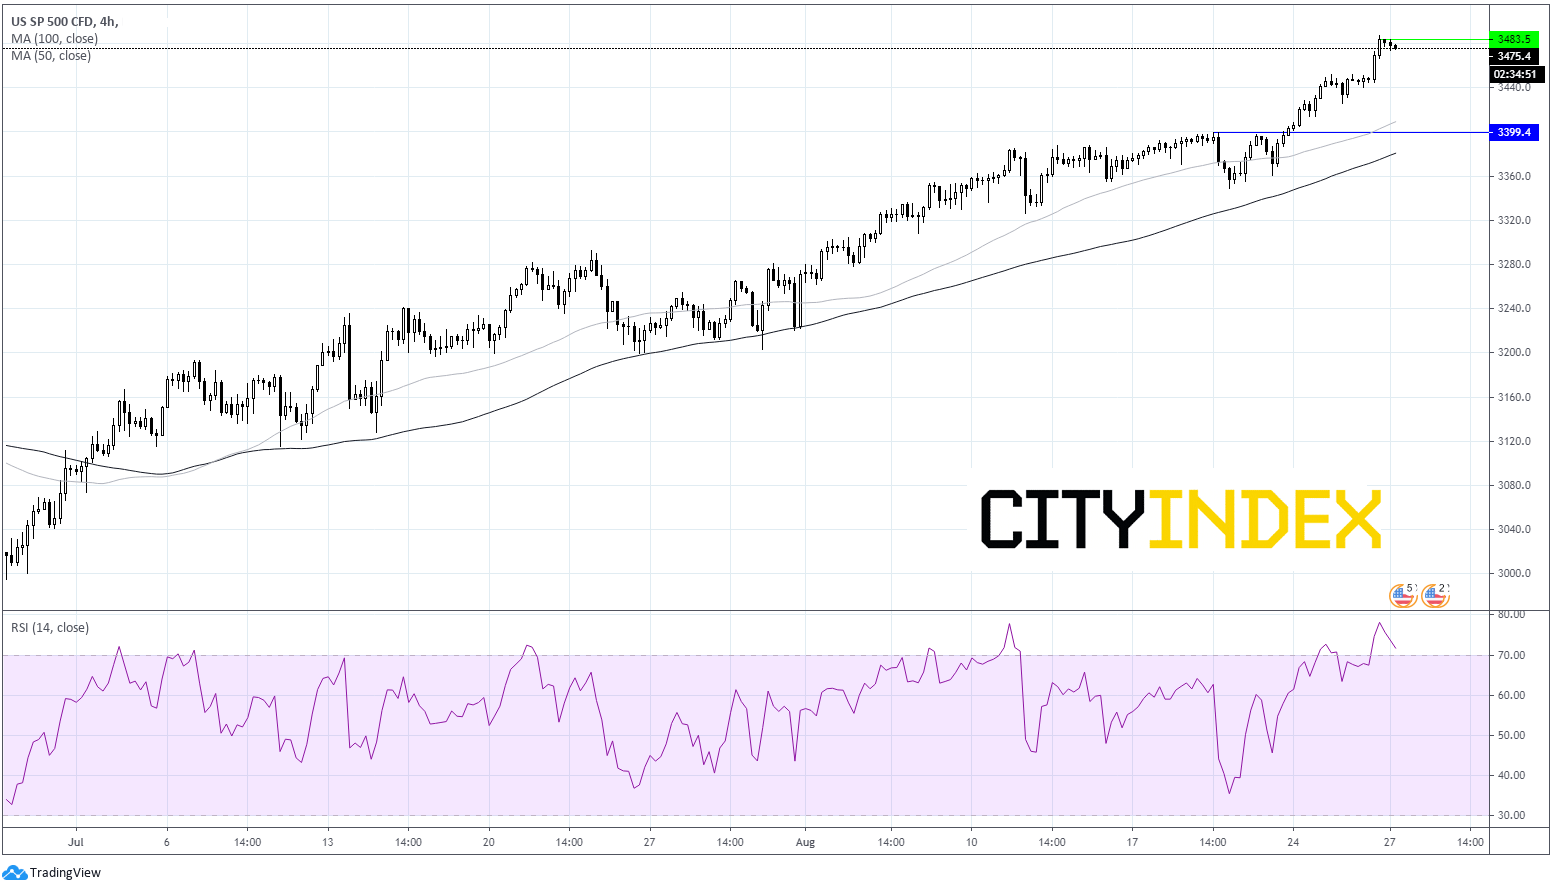
Wall Street rolled on with another record day. The S&P hit its fourth straight closing high and the Nasdaq set its 39th closing high YTD as investors remained focused on big tech and large cap momentum stocks which have continued to outperform since the start of the coronavirus outbreak.
Now it’s the calm before the storm. Asia traded muted overnight, Europe is pointing to a mildly mixed start and the FX markets are subdued ahead of Jerome Powell taking to the virtual stage at Jackson Hole.
Fed Chair Jerome Powell could announce or at least hint towards a paradigm shift in policy to Average Target Inflation; a model which would allow inflation to overshoot 2% for extended periods of time in order to support economic activity. This means that interest rates will ultimately stay low for longer.
Such an announcement from the Fed wouldn’t necessarily be a huge surprise. Whilst some of this policy shift has already been priced in, it is unlikely to be fully priced in either. Meaning Powell could send the US Dollar on another leg lower, cause a rebound in Gold which has fallen away from its record high in recent sessions and push US equities (further) northwards.
With the markets believing such an announcement is forthcoming, anything less than a signal from Powell that ATI in some form is imminent could destabilise the markets.
USD GDP & Jobless claims
Whilst Jerome Powell is the star performer, warm up acts in the form of US GDP data (2nd revision) and initial jobless claims will also be in focus.
US GDP is expected to see a very slight downward revision to 32.6% from 32.9%. Initial jobless claims could garner more interest. Last week they rose back above 1 million, potentially the first sign of trouble after the Federal additional $600 unemployment benefit expired. Should claims remain over 1 million pressure will ramp up on Congress to agree to an additional rescue package.
Whilst Jerome Powell is the star performer, warm up acts in the form of US GDP data (2nd revision) and initial jobless claims will also be in focus.
US GDP is expected to see a very slight downward revision to 32.6% from 32.9%. Initial jobless claims could garner more interest. Last week they rose back above 1 million, potentially the first sign of trouble after the Federal additional $600 unemployment benefit expired. Should claims remain over 1 million pressure will ramp up on Congress to agree to an additional rescue package.
Oil unusually steady ahead of Hurricane Laura
The price of oil has barely changed over the past two session even as oil rigs and refineries shut in preparation for a huge tropical storm in the Gulf of Mexico. Usually these storms create significant volatility in oil prices given the supply impact. But this, year, as we know, is not like any other year. High inventories as a result of the coronavirus pandemic hit to demand, combined with uncertainty over future demand means that the oil market can take these storms in its stride.
With coronavirus cases rising in parts of Europe, such as France and Spain, fears are rising of a second wave. Whilst the governments are vocally against a second national lockdown, oil markets are still nervous.
SPX Chart
Wall Street rolled on with another record day. The S&P hit its fourth straight closing high and the Nasdaq set its 39th closing high YTD as investors remained focused on big tech and large cap momentum stocks which have continued to outperform since the start of the coronavirus outbreak.
Now it’s the calm before the storm. Asia traded muted overnight, Europe is pointing to a mildly mixed start and the FX markets are subdued ahead of Jerome Powell taking to the virtual stage at Jackson Hole.
Fed Chair Jerome Powell could announce or at least hint towards a paradigm shift in policy to Average Target Inflation; a model which would allow inflation to overshoot 2% for extended periods of time in order to support economic activity. This means that interest rates will ultimately stay low for longer.
Such an announcement from the Fed wouldn’t necessarily be a huge surprise. Whilst some of this policy shift has already been priced in, it is unlikely to be fully priced in either. Meaning Powell could send the US Dollar on another leg lower, cause a rebound in Gold which has fallen away from its record high in recent sessions and push US equities (further) northwards.
With the markets believing such an announcement is forthcoming, anything less than a signal from Powell that ATI in some form is imminent could destabilise the markets.
USD GDP & Jobless claims
Whilst Jerome Powell is the star performer, warm up acts in the form of US GDP data (2nd revision) and initial jobless claims will also be in focus.
US GDP is expected to see a very slight downward revision to 32.6% from 32.9%. Initial jobless claims could garner more interest. Last week they rose back above 1 million, potentially the first sign of trouble after the Federal additional $600 unemployment benefit expired. Should claims remain over 1 million pressure will ramp up on Congress to agree to an additional rescue package.
Whilst Jerome Powell is the star performer, warm up acts in the form of US GDP data (2nd revision) and initial jobless claims will also be in focus.
US GDP is expected to see a very slight downward revision to 32.6% from 32.9%. Initial jobless claims could garner more interest. Last week they rose back above 1 million, potentially the first sign of trouble after the Federal additional $600 unemployment benefit expired. Should claims remain over 1 million pressure will ramp up on Congress to agree to an additional rescue package.
Oil unusually steady ahead of Hurricane Laura
The price of oil has barely changed over the past two session even as oil rigs and refineries shut in preparation for a huge tropical storm in the Gulf of Mexico. Usually these storms create significant volatility in oil prices given the supply impact. But this, year, as we know, is not like any other year. High inventories as a result of the coronavirus pandemic hit to demand, combined with uncertainty over future demand means that the oil market can take these storms in its stride.
With coronavirus cases rising in parts of Europe, such as France and Spain, fears are rising of a second wave. Whilst the governments are vocally against a second national lockdown, oil markets are still nervous.
SPX Chart
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Equity Indices Q4, 2026 Outlook: Cracks Begin to Show
There's still an open door for a melt-up in the S&P 500 and Nasdaq but the Dow and Russell 2000 are looking more vulnerable, and until calm hits the Treasuries market there's a higher probability for volatility. The big question is whether that's a next quarter theme or not.

S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.


S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.