



ASX200 Afternoon Report September 7th 2022
The ASX200 trades 100 points lower at 6727 at 3.05pm
Share this:

The ASX200 trades 100 points lower at 6727 at 3.05pm
If the Labour Day long weekend was meant to provide a circuit breaker after the Fed Chairs' hawkish speech at Jackson Hole, then the bond market didn't get the memo as a surge higher in yields saw U.S equity markets extend their free fall overnight.
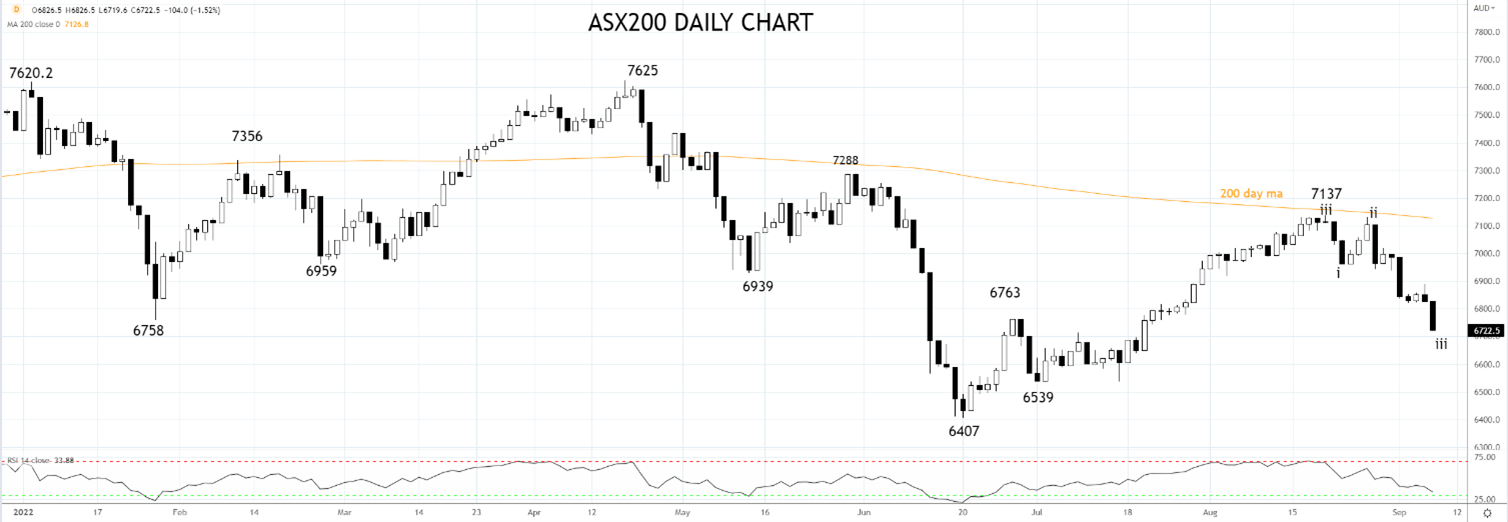
The weaker session on Wall Street was the backdrop for the local bourse to plunge 1.6% to its lowest level in seven weeks (6719.6) an hour after the opening bell, a move that it has struggled to unwind during the remainder of the session.
A reversal lower in crude oil on fears over higher interest rates, recession, and Covid lockdowns in China, along with a 6.9% fall in European natural gas prices, unleashed carnage in Energy stocks.
Beach Energy fell 6.4% to $1.69, Woodside fell 3.15% to $33.98, Cooper Energy fell 3.7% to $0.26c, Santos fell 2.14% to $7.77. New Hope Coal fell 4.37% to $5.47, Coronado coal fell 3% to $1.68, Whitehaven coal fell 2.2% to $8.61, and Yancoal fell 0.6% to $6.67.
News that the lockdown in Chengdu is set to be extended weighed on metals prices and the price of the big miners. FMG fell 2.75% to $16.00, BHP fell 2.4% to $36.38. Rio Tinto fell 1.8% to $89.15, and Mineral Resources fell 1.5% to $59.43.
The national accounts released today showed the Australian economy in the June Quarter expanded by a solid 0.9% and 3.6% YoY. It's the third consecutive quarter of economic expansion for the Australian economy.
Today's figures coincided with the start of the RBA's rate hiking cycle in May and come just one day after the RBA raised rates by 50bps to 2.35%, leaving Q3 as the one that should reveal the impact of the RBA's 225bp of rate hikes to date.
While the statement that accompanied yesterday's rates decision hinted at a more moderate pace of rate rises, more clues may be forthcoming from the RBA Governors' Speech at the Annika Foundation lunch tomorrow.
Nonetheless, stocks in the Financial Sector weren't in the mood to wait around. NAB fell 3% to $29.22, Westpac fell 2% to $20.84, CBA fell 1.86% to $94.31, and ANZ fell 1.5% to $22.25.
Defying the melt-up in interest rates, the IT sector held its ground, led by gains in Link Administration which added 2.4% to $4.30, and Computershare added 1.5% to $24.46. Appen added 0.83% to $3.65 and Megaport added 0.55% to $7.30.
Unable to withstand the heat of an unrelenting rise in the U.S dollar and in USDCNY, the AUDUSD is trading at .6715, eyeing the .6681 low from mid-June. A break/close below .6681 would then see the AUDUSD move towards the next level of support, .6530/00.
After today's acceleration lower, the ASX200 is vulnerable to a retest of the June 6407 low, with bounces expected to be met by sellers at 6850 and again at 7000.
Source Tradingview. The figures stated are as of September 7th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
The ASX200 trades 100 points lower at 6727 at 3.05pm
If the Labour Day long weekend was meant to provide a circuit breaker after the Fed Chairs' hawkish speech at Jackson Hole, then the bond market didn't get the memo as a surge higher in yields saw U.S equity markets extend their free fall overnight.
The weaker session on Wall Street was the backdrop for the local bourse to plunge 1.6% to its lowest level in seven weeks (6719.6) an hour after the opening bell, a move that it has struggled to unwind during the remainder of the session.
A reversal lower in crude oil on fears over higher interest rates, recession, and Covid lockdowns in China, along with a 6.9% fall in European natural gas prices, unleashed carnage in Energy stocks.
Beach Energy fell 6.4% to $1.69, Woodside fell 3.15% to $33.98, Cooper Energy fell 3.7% to $0.26c, Santos fell 2.14% to $7.77. New Hope Coal fell 4.37% to $5.47, Coronado coal fell 3% to $1.68, Whitehaven coal fell 2.2% to $8.61, and Yancoal fell 0.6% to $6.67.
News that the lockdown in Chengdu is set to be extended weighed on metals prices and the price of the big miners. FMG fell 2.75% to $16.00, BHP fell 2.4% to $36.38. Rio Tinto fell 1.8% to $89.15, and Mineral Resources fell 1.5% to $59.43.
The national accounts released today showed the Australian economy in the June Quarter expanded by a solid 0.9% and 3.6% YoY. It's the third consecutive quarter of economic expansion for the Australian economy.
Today's figures coincided with the start of the RBA's rate hiking cycle in May and come just one day after the RBA raised rates by 50bps to 2.35%, leaving Q3 as the one that should reveal the impact of the RBA's 225bp of rate hikes to date.
While the statement that accompanied yesterday's rates decision hinted at a more moderate pace of rate rises, more clues may be forthcoming from the RBA Governors' Speech at the Annika Foundation lunch tomorrow.
Nonetheless, stocks in the Financial Sector weren't in the mood to wait around. NAB fell 3% to $29.22, Westpac fell 2% to $20.84, CBA fell 1.86% to $94.31, and ANZ fell 1.5% to $22.25.
Defying the melt-up in interest rates, the IT sector held its ground, led by gains in Link Administration which added 2.4% to $4.30, and Computershare added 1.5% to $24.46. Appen added 0.83% to $3.65 and Megaport added 0.55% to $7.30.
Unable to withstand the heat of an unrelenting rise in the U.S dollar and in USDCNY, the AUDUSD is trading at .6715, eyeing the .6681 low from mid-June. A break/close below .6681 would then see the AUDUSD move towards the next level of support, .6530/00.
After today's acceleration lower, the ASX200 is vulnerable to a retest of the June 6407 low, with bounces expected to be met by sellers at 6850 and again at 7000.
Source Tradingview. The figures stated are as of September 7th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.