


DAX: European stocks outperform again
Sentiment boosted because of warmer-than-expected weather which has reduced fears about gas shortages.
Share this:

European equity indices again outperformed in the first half of today’s session, with the likes of the German DAX being up around 1.5% by midday in London. US future were up modestly at the time of writing. As we transition to the US session, will those earlier gains evaporate for Europe, as the focus turns back to central bank policy tightening and a slumping US technology sector?
In Europe, sentiment has been boosted because of warmer-than-expected weather at the start of the winter season, which has reduced fears about gas shortages. What’s more, data from Eurozone has improved, albeit from a very low base. Today, for example, the latest services PMI data from Spain and Italy beat expectations, while the Eurozone final PMI was revised up a touch – though still remained just below the boom/bust level of 50.0. What’s more, German import prices slumped 4.5% month-over-month, in a further sign that inflation may have peaked.
However, recession fears have not gone away completely. Just look at oil prices. They fell more than 3.5% to extend their drop from the previous session. We had weak PMI data from China over the weekend and yesterday Caixin PMI was also weak. With activity contracting, this feeds back into the weak global growth narrative. China’s reopening has been hampered by rising covid cases and measures countries are putting against Chinese travellers.
In the afternoon, the focus will turn to US data, with ISM manufacturing PMU, JOLTS Job Openings and FOMC meeting minutes all to come. So, we will have this year’s first set of important macro data later, with the minutes of the FOMC’s December meeting likely to be the most important. At that meeting, the FOMC reduced the pace of tightening to 50 basis points but appeared more hawkish than expected, in that policymakers projected a higher terminal interest rate and indicated that monetary policy will remain contractionary for longer. The minutes should reveal more details, which should set the tone for next few days at least.
Overall, much of the issues we faced in 2022 are going to be with us well into 2023, including high levels of inflation and rising interest rates. A recession seems unavoidable. Traders know that after a big rebound starting in October for US and global indices, much of the positivity about the Fed pivoting to a less hawkish stance has now been priced in. So, the risks remain tilted towards the downside.
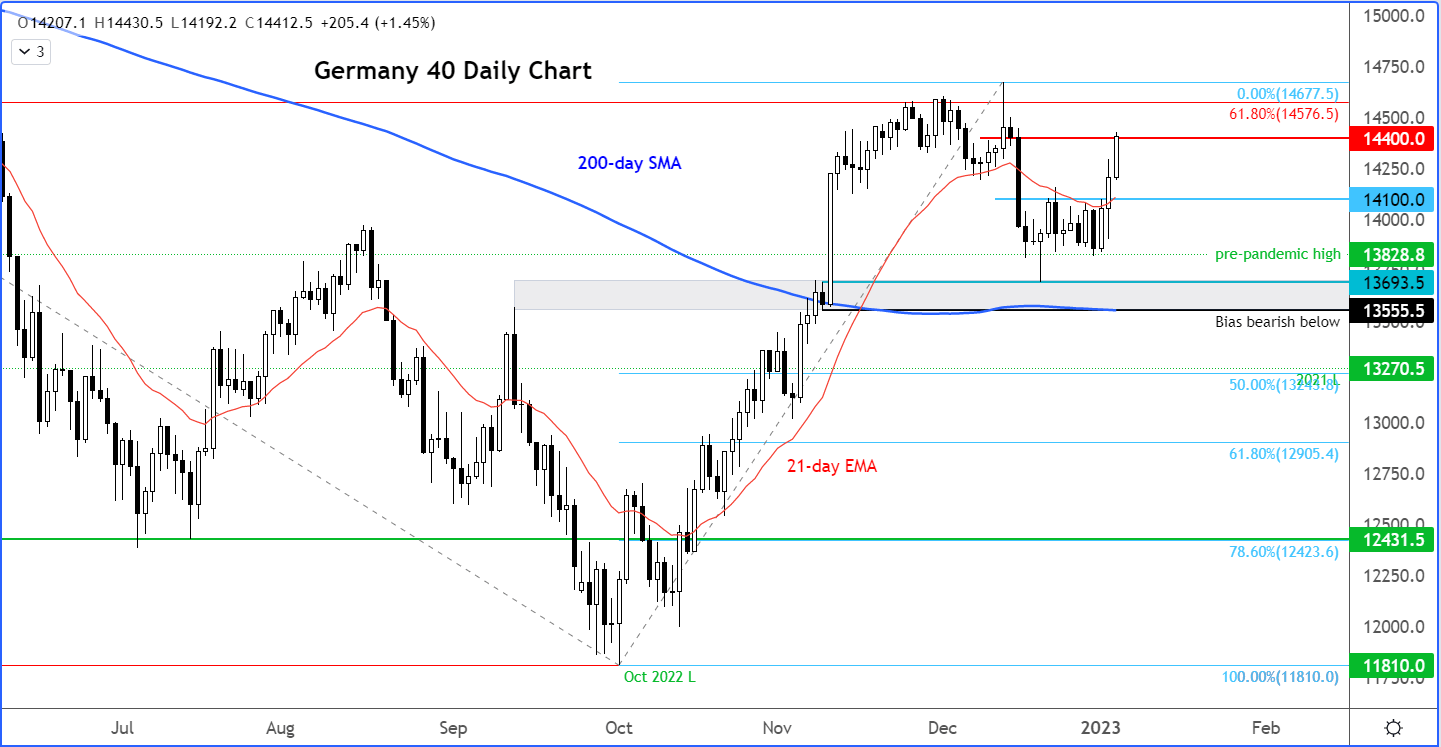
Still, the DAX’s strong recovery cannot be ignored. The bears will need to see some confirmation after it broke key resistance at around 14100, before surging to the next resistance around 14400 today. Perhaps a potential move back below 14100 could excite the bears. On the other hand, if the index closes today’s session around current levels then the bulls will remain confident of a larger recovery and will thus be in the mood to keep buying short-term dips.
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log-in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.