



FTSE Surges After Chinese PMIs Impress
Vaccine optimism, impressive Chinese factory data and the prospect of continuing fiscal and monetary stimulus is keeping the European bourses upbeat.
Share this:

After a phenomenal November run-up European markets are broadly resuming gains at the start of December, a traditionally strong moth for equities. Vaccine optimism, impressive Chinese factory data and the prospect of continuing fiscal and monetary stimulus is keeping the mood upbeat.
China’s blue chip index surged over 1.5% on Tuesday after business survey data revealed that factory activity accelerated at its fastest pace in a decade in November. The Chinese Caixin/Markit manufacturing PMIA rose to 54.9 in November, up from 53.6 in October, in the 7th straight month of expansion.
The data confirms that the economic recovery in the world’s second largest economy continues to rebound strongly since the pandemic paralysed the economy earlier in the year.
Manufacturing PMIs in focus
Manufacturing PMIs will remain in focus with data due from the UK and the Eurozone. The UK manufacturing sector has shown resilience across recent months even as services have shown signs of weakening. The flash estimate for UK manufacturing PMI was firmly in expansionary territory at 55.2 and this isn’t expected to change. Its understandable that manufacturing will be stronger than services during the lockdown period given that they haven’t been required to close.
Manufacturing PMIs will remain in focus with data due from the UK and the Eurozone. The UK manufacturing sector has shown resilience across recent months even as services have shown signs of weakening. The flash estimate for UK manufacturing PMI was firmly in expansionary territory at 55.2 and this isn’t expected to change. Its understandable that manufacturing will be stronger than services during the lockdown period given that they haven’t been required to close.
The pound is striving higher +0.5% at 1.3360.
UK’s mini housing boom continues
House builders will be under the spotlight after Nationwide House Price data showed that UK house prices grew at the fastest pace since 2015 in November. The mini housing boom is showing no signs of letting up with house prices jumping 6.5% on an annual rate despite lockdown 2.0, as behaviour shifts and the stamp duty holiday keep the market robust.
House builders will be under the spotlight after Nationwide House Price data showed that UK house prices grew at the fastest pace since 2015 in November. The mini housing boom is showing no signs of letting up with house prices jumping 6.5% on an annual rate despite lockdown 2.0, as behaviour shifts and the stamp duty holiday keep the market robust.
Oil slips again with no OPEC+ agreement reached
Oil is under pressure once again battling $45 after OPEC+ members failed to reach an agreement over extending oil production cuts. Talks will be extended over the coming days which is likely to keep oil under pressure. Failure to agree a deal will see oil production increase by 2 million barrels a day at a time when travel restrictions and lockdown measures are likely to be dragging on demand.
Oil is under pressure once again battling $45 after OPEC+ members failed to reach an agreement over extending oil production cuts. Talks will be extended over the coming days which is likely to keep oil under pressure. Failure to agree a deal will see oil production increase by 2 million barrels a day at a time when travel restrictions and lockdown measures are likely to be dragging on demand.
Fallout from Arcadia’s collapse
Retailers are likely to attract attention as concerns grow over the health of the UK high street after Arcadia fell into administration. the fallout from this could be far reaching and that is unnerving investors. Not only are 13,000 jobs on the line, but landlords are also in line to take a hit from the collapse of Topshop’s owner.
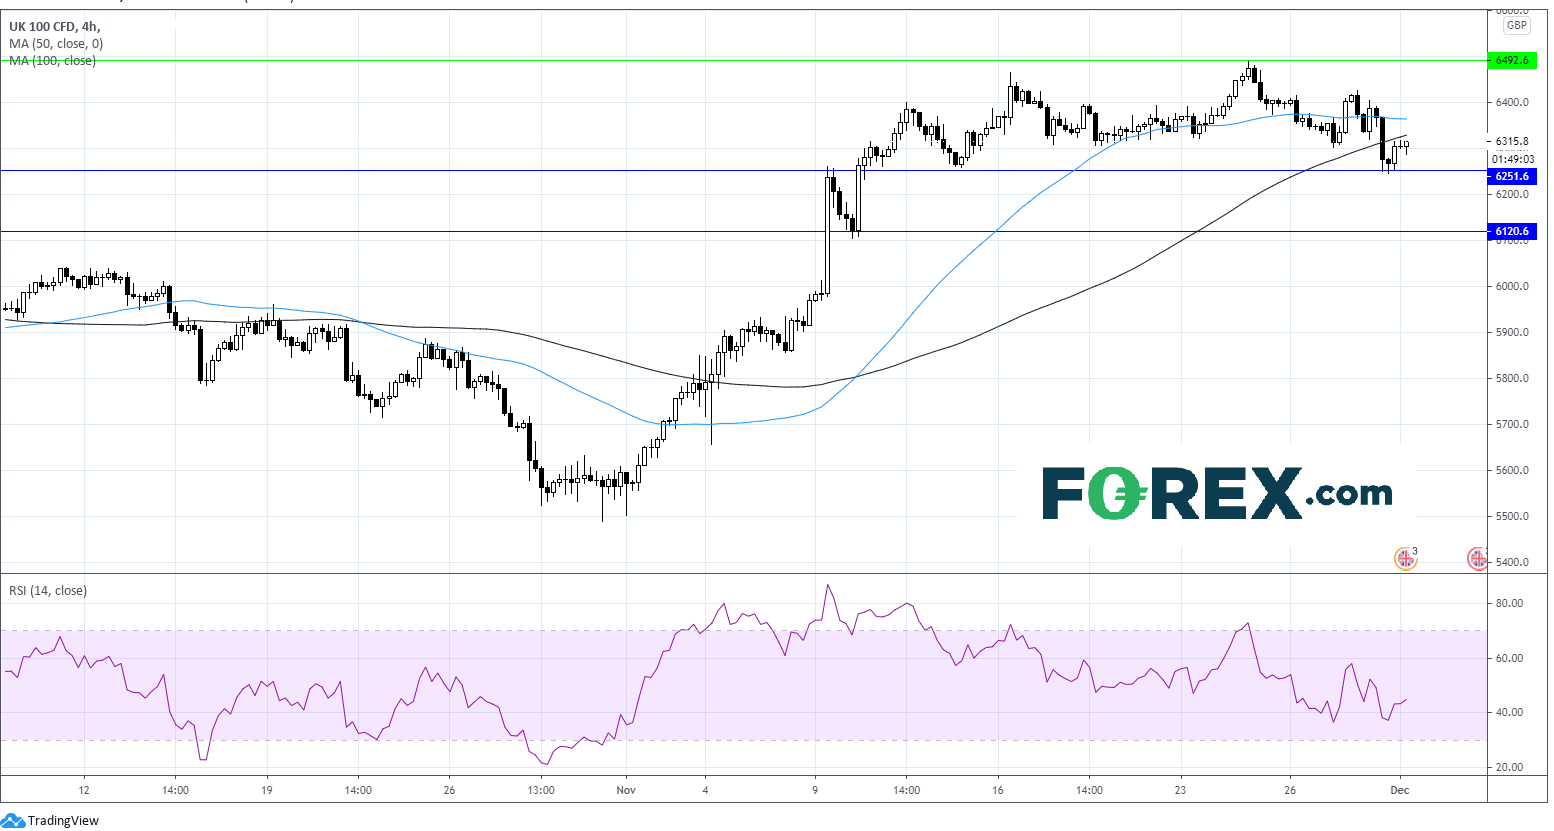
FTSE Chart
After a phenomenal November run-up European markets are broadly resuming gains at the start of December, a traditionally strong moth for equities. Vaccine optimism, impressive Chinese factory data and the prospect of continuing fiscal and monetary stimulus is keeping the mood upbeat.
China’s blue chip index surged over 1.5% on Tuesday after business survey data revealed that factory activity accelerated at its fastest pace in a decade in November. The Chinese Caixin/Markit manufacturing PMIA rose to 54.9 in November, up from 53.6 in October, in the 7th straight month of expansion.
The data confirms that the economic recovery in the world’s second largest economy continues to rebound strongly since the pandemic paralysed the economy earlier in the year.
Manufacturing PMIs in focus
Manufacturing PMIs will remain in focus with data due from the UK and the Eurozone. The UK manufacturing sector has shown resilience across recent months even as services have shown signs of weakening. The flash estimate for UK manufacturing PMI was firmly in expansionary territory at 55.2 and this isn’t expected to change. Its understandable that manufacturing will be stronger than services during the lockdown period given that they haven’t been required to close.
Manufacturing PMIs will remain in focus with data due from the UK and the Eurozone. The UK manufacturing sector has shown resilience across recent months even as services have shown signs of weakening. The flash estimate for UK manufacturing PMI was firmly in expansionary territory at 55.2 and this isn’t expected to change. Its understandable that manufacturing will be stronger than services during the lockdown period given that they haven’t been required to close.
The pound is striving higher +0.5% at 1.3360.
UK’s mini housing boom continues
House builders will be under the spotlight after Nationwide House Price data showed that UK house prices grew at the fastest pace since 2015 in November. The mini housing boom is showing no signs of letting up with house prices jumping 6.5% on an annual rate despite lockdown 2.0, as behaviour shifts and the stamp duty holiday keep the market robust.
House builders will be under the spotlight after Nationwide House Price data showed that UK house prices grew at the fastest pace since 2015 in November. The mini housing boom is showing no signs of letting up with house prices jumping 6.5% on an annual rate despite lockdown 2.0, as behaviour shifts and the stamp duty holiday keep the market robust.
Oil slips again with no OPEC+ agreement reached
Oil is under pressure once again battling $45 after OPEC+ members failed to reach an agreement over extending oil production cuts. Talks will be extended over the coming days which is likely to keep oil under pressure. Failure to agree a deal will see oil production increase by 2 million barrels a day at a time when travel restrictions and lockdown measures are likely to be dragging on demand.
Oil is under pressure once again battling $45 after OPEC+ members failed to reach an agreement over extending oil production cuts. Talks will be extended over the coming days which is likely to keep oil under pressure. Failure to agree a deal will see oil production increase by 2 million barrels a day at a time when travel restrictions and lockdown measures are likely to be dragging on demand.
Fallout from Arcadia’s collapse
Retailers are likely to attract attention as concerns grow over the health of the UK high street after Arcadia fell into administration. the fallout from this could be far reaching and that is unnerving investors. Not only are 13,000 jobs on the line, but landlords are also in line to take a hit from the collapse of Topshop’s owner.
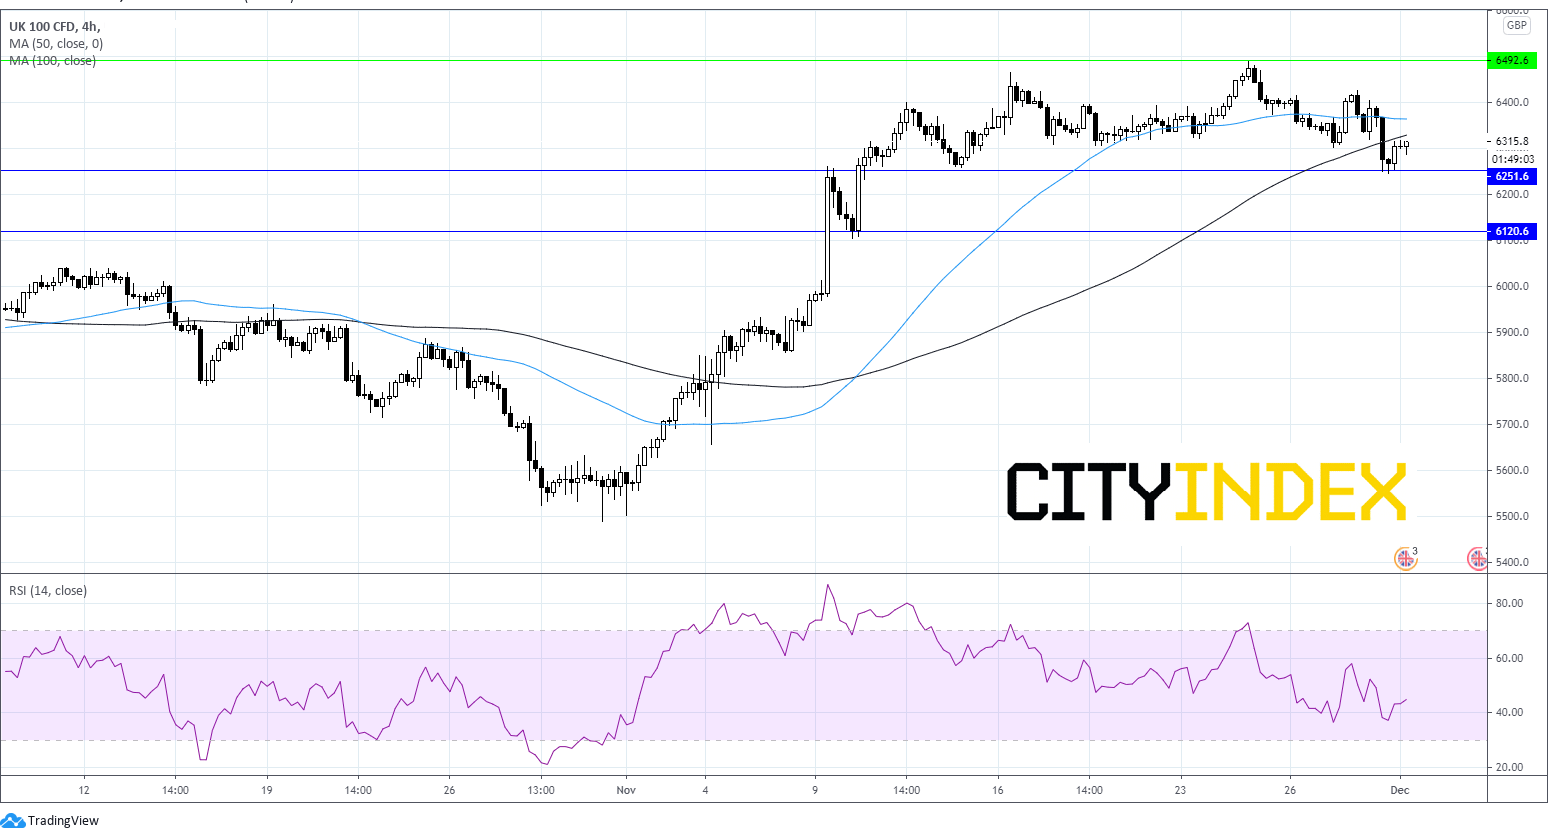
FTSE Chart
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD, FTSE 100 Forecast: Two trades to watch 1507
EUR/USD rises after weaker US CPI, PPI up next. FTSE 100 falls as weak China GDP data hits miners.

FTSE 100, USD/JPY Forecast: Two trades to watch
FTSE eases modestly despite inflation unexpectedly holding steady. USD/JPY drifts lower ahead of the FOMC rate decision.
EUR/USD, FTSE 100 Forecast: Two trades to watch 21-05-26
EUR/USD slips below 1.16 as weak eurozone data weighs on sentiment. FTSE 100 slips as oil prices rebound and caution returns.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.