




Market Brief NFP set to disappoint
A summary of news and snapshot of moves ahead of the US session.
Share this:

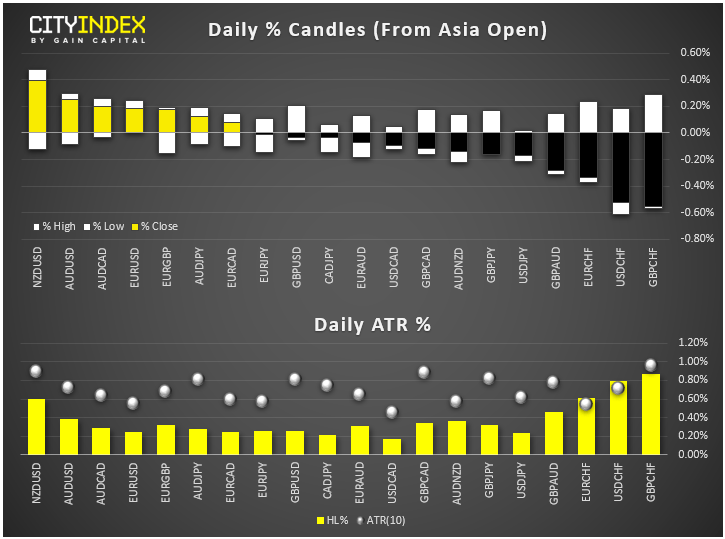
- At midday in London, NZD and AUD were among the strongest, while GBP and USD were the weak links.
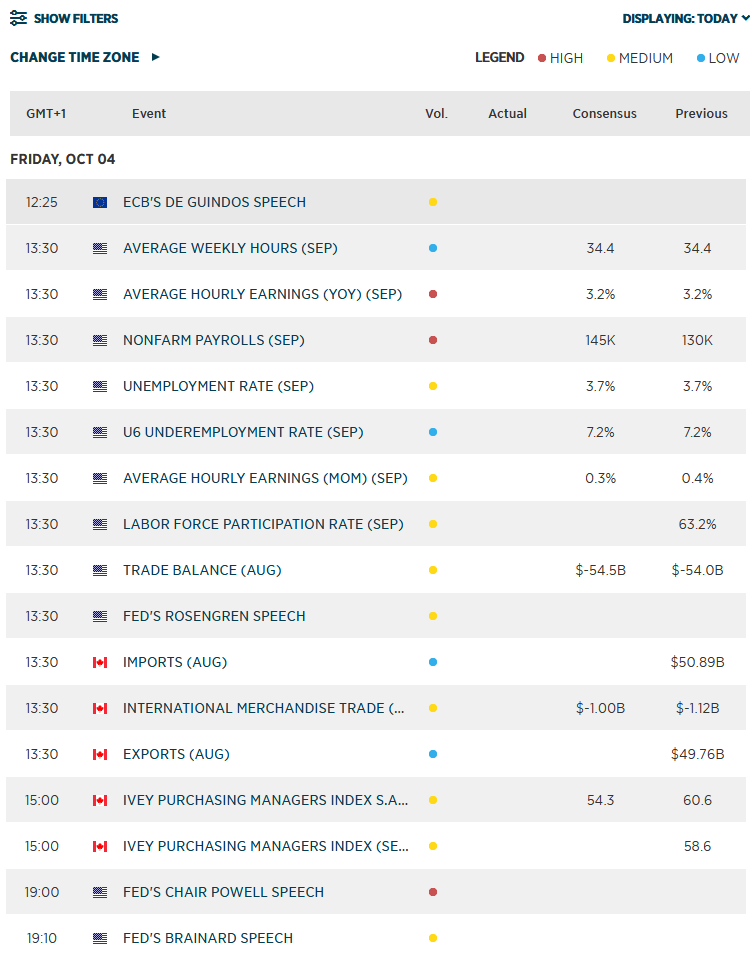
- Today’s US nonfarm payroll report is – for obvious reason – the main focal point. A headline jobs growth of 145K is expected, with wages seen rising by 0.3% month-over-month. But due to several soft pre-NFP leading indicators released throughout this week, you can almost sense that the market is bracing itself for disappointment. Read our NFP preview HERE. If our fears are realised then the probability of a 25bps rate cut at the October 30 FOMC meeting may rise near the 100% level, which would could see the greenback break further support levels.
- Among commodities, gold was continuing to shine brightly in these turbulent times due, among other things, to higher demand for haven assets. Also supporting the precious metal is a falling US dollar and rising bond prices (or put another way, falling yields – this is boosting the appeal of noninterest-bearing assets like gold and silver). Meanwhile, crude prices struggled to recover further ground after its kick-back rally along with stocks yesterday. Oil has been hit by a double whammy of bearish news this week. The fact that Saudi has managed to restore its production back to original capacity after those attacks on its infrastructure by Houthi rebels (which Saudi and the US claimed were backed by Iran) sooner than expected means investors have had to price out raised supply risks at a faster clip than would have otherwise been the case. On top of this, we had a handful of soft global macro data – particularly from the US manufacturing sector – which has raised fears that oil demand might not grow as fast as it had been expected. But now that some of these factors have been priced in, oil prices may fall less sharply going forward or at best start to form a base.
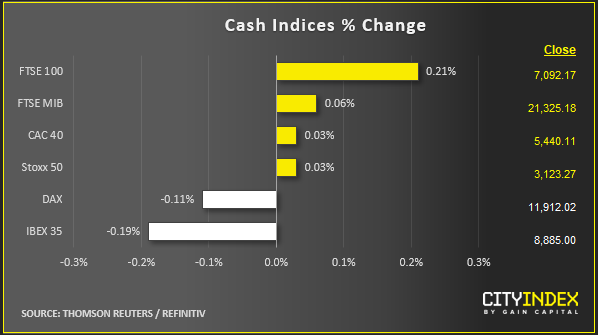
- Stocks were struggling again in Europe after yesterday’s short-covering bounce. It remains to be seen how the markets will end tonight after what has been a turbulent week so far. Will an unexpectedly good US employment report be enough to lift sentiment? Will opportunistic investors step in, hoping that the upcoming US-China trade talks will result in a breakthrough? Or will investors use this opportunity to close out their positions that were previously in deeper losses? We reckon that if the employment report is a poor one, then stocks may fall into the close – for the markets have responded negatively (for a change) to bad data so far in the week, suggesting investors feel that monetary policy alone is no longer enough to support stocks at these extremely elevated levels.
- At midday in London, NZD and AUD were among the strongest, while GBP and USD were the weak links.
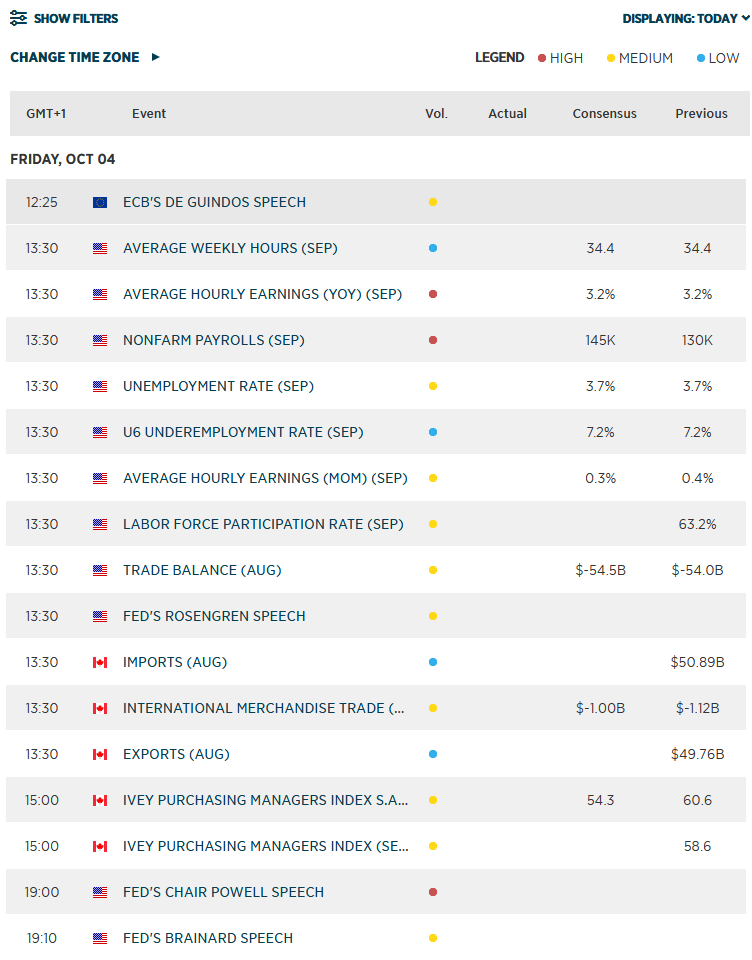
- Today’s US nonfarm payroll report is – for obvious reason – the main focal point. A headline jobs growth of 145K is expected, with wages seen rising by 0.3% month-over-month. But due to several soft pre-NFP leading indicators released throughout this week, you can almost sense that the market is bracing itself for disappointment. Read our NFP preview HERE. If our fears are realised then the probability of a 25bps rate cut at the October 30 FOMC meeting may rise near the 100% level, which would could see the greenback break further support levels.
- Among commodities, gold was continuing to shine brightly in these turbulent times due, among other things, to higher demand for haven assets. Also supporting the precious metal is a falling US dollar and rising bond prices (or put another way, falling yields – this is boosting the appeal of noninterest-bearing assets like gold and silver). Meanwhile, crude prices struggled to recover further ground after its kick-back rally along with stocks yesterday. Oil has been hit by a double whammy of bearish news this week. The fact that Saudi has managed to restore its production back to original capacity after those attacks on its infrastructure by Houthi rebels (which Saudi and the US claimed were backed by Iran) sooner than expected means investors have had to price out raised supply risks at a faster clip than would have otherwise been the case. On top of this, we had a handful of soft global macro data – particularly from the US manufacturing sector – which has raised fears that oil demand might not grow as fast as it had been expected. But now that some of these factors have been priced in, oil prices may fall less sharply going forward or at best start to form a base.
- Stocks were struggling again in Europe after yesterday’s short-covering bounce. It remains to be seen how the markets will end tonight after what has been a turbulent week so far. Will an unexpectedly good US employment report be enough to lift sentiment? Will opportunistic investors step in, hoping that the upcoming US-China trade talks will result in a breakthrough? Or will investors use this opportunity to close out their positions that were previously in deeper losses? We reckon that if the employment report is a poor one, then stocks may fall into the close – for the markets have responded negatively (for a change) to bad data so far in the week, suggesting investors feel that monetary policy alone is no longer enough to support stocks at these extremely elevated levels.
Related tags:



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD forecast: Eurozone stagflation risks mount as dollar holds firm ahead of data
The dollar was bouncing back at the time of writing, after it had eased overnight on the back of some weaker-than-expected economic data yesterday which had prompted markets to scale back expectations of an October Fed rate hike. However, with more significant US data due today and Friday, and with oil prices continuing to remain elevated, the dollar’s broader direction remains bullish.

NZD/USD pressure mounts as payrolls looms large
NZD/USD has fallen sharply as Fed rate expectations reset higher, but extreme downside stretch and major support raise the risk of a violent counter-trend rebound.


US Core PCE Preview: Stale or Significant for the Fed
Core PCE inflation takes center stage Wednesday, with traders watching for signs of renewed price pressure and clues on whether the Fed could hike again in October.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.