


Nasdaq 100 Forecast: QQQ at record highs on US trade deal optimism
The S&P 500 and Nasdaq futures have risen to record highs on Monday, boosted by optimism of U.S. trade negotiations with key partners and rising Fed rate cut expectations.
Share this:
US futures
Dow futures 0.57% at 44059
S&P futures 0.23% at 6196
Nasdaq futures 0.63% at 22670
In Europe
FTSE -0.09% at 8775
DAX -0.08% at 24000
- US stocks reaching fresh record levels
- Canada scraps digital services tax to move trade talks along
- Fed rate cut bets help the market mood
- Oil is set to drop 12% across the week as the risk premium evaporates
Record highs with trade deals in focus
The S&P 500 and Nasdaq futures have risen to record highs on Monday, boosted by optimism of U.S. trade negotiations with key partners.
News that Canada scrapped its digital services tax targeting US tech firms just hours before it was due to take effect has lifted technology heavyweights. The move comes in an effort to advance trade negotiations with the US, which have hit rocky ground.
Hopes for trade deals between the US and its key trading partners are acting as a tailwind to the market and could be a significant driver over the coming week, as the focus shifts to the July 9 deadline to reach a deal with the US.
Investors will also be looking into US economic data and fiscal policy developments. On Friday, U.S. stock indices, including the S&P 500 and the Nasdaq 100, hit all-time highs amid bets that the Federal Reserve could cut interest rates sooner. This week, data from ISM manufacturing and services PMI as well as Thursday's nonfarm payroll, could provide further clarity over the Fed's next move. Federal Reserve Chair Jerome Powell is also scheduled to speak.
Traders are pricing in at 20% probability that the Fed could cut rates as soon as July and a 73% chance of a September cut.
Corporate news
Banks will be in focus after the Federal Reserve's annual stress test found that 22 of the largest U.S. banks are well-positioned to weather a severe economic downturn. This optimistic result could mean banks increase how much they plan to distribute to shareholders.
Nvidia is rising nought .5% premarket with the share price at record levels. The AI trade returned last week as disruptions from the first half of the year eased. The share price has almost doubled from its April low.
Tesla is set to open lower with the EV maker expected to unveil second-quarter delivery numbers on Wednesday as it grapples with weaker demand and concerns surrounding Elon Musk's political stance.
Disney is opening over 2% higher after Jefferies upgraded its stance to buy from hold amid optimism surrounding Disney's cruise business.
Nasdaq 100 forecast – technical analysis.
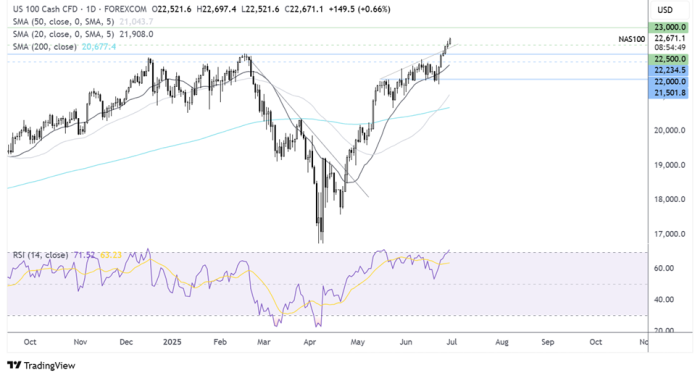
The Nasdaq 100 has recovered from last Monday’s low of 23,350, rising above 22,245 and the rising trendline resistance to a fresh record high of 22,700. The RSI is tipping into overbought territory, so some consolidation could be on the cards. The bulls will look to extend gains towards 23000. On the downside, support can be seen at 22,500, the trendline support, and round number. Belooew here 22,245 comes into focus. A break below 21,500 is needed to create a lower low.
FX markets – USD falls, EUR/USD falls
The USD is edging lower after falling 1.5% last week. Optimism over US trade deals boosted expectations that the Federal Reserve could cut interest rates sooner. The USD is at a multi-year low against its major peers.
The EUR/USD is rising modestly despite weaker-than-expected German retail sales, which fell -1.6% MoM, defying expectations of a rise of 0.5%. German CPI data is due shortly and is expected to rise to 2.2% YoY up from 2.1%. Eurozone inflation data is due tomorrow, and if it comes in weaker than expected, it could boost ECB rate cut bets, pulling the EUR lower.
GBP/USD is hovering around 1.37, a multi-year high reached last week. UK GDP data show that the UK economy grew 0.7% in Q12025, confirming the preliminary estimate and marking the fastest growth since Q1 2024; however, the pace of growth is not expected to be sustained, with the Bank of England forecasting growth of 0.25% in Q2.
Oil steadies after dropping 12% last week
After slumping 12% last week, oil prices are steadying around the 65 level as investors continue to weigh up easing Middle East risks and ahead of the OPEC+ meeting next weekend.
The market has returned to a range-trading environment as the risk premium, which had sent oil prices above $80 a barrel, has been reduced following the Israel ceasefire.
Attention is turning towards the OPEC+ meeting later this week, where the group is expected to boost production by 411,000 barrels per day in August, following similar increases in the previous three months. This could prevent any further upside in prices.




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nasdaq Breakout Potential into Q4 for Melt Up Scenarios
The headlines seem negative in almost any place that you look, with surging Treasury yields and frothy AI valuations getting more and more attention. But, if it’s so bad, why hasn’t the Nasdaq melted down yet, even as the Fed has started hiking rates?


S&P 500 Forecast: SPX rises after cooler-than-expected inflation data
U.S. stocks are rising and Treasury yields are falling after data showed that inflation increased at a cooler pace than expected, while U.S. consumer spending rose again in August.
Nasdaq 100 Forecast: NDX rises as oil eases and tech gains
U.S. stocks are heading higher on Tuesday, helped by a pullback in oil prices and after details about Anthropic's IPO boosted sentiment towards tech stocks.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.