



S&P 500 Forecast: SPX rises after cooler-than-expected inflation data
U.S. stocks are rising and Treasury yields are falling after data showed that inflation increased at a cooler pace than expected, while U.S. consumer spending rose again in August.
Share this:
US futures
Dow futures 0.06%, S&P 500 futures 0.2% & Nasdaq futures 0.45%
European futures
FTSE -0.04%, DAX -0.28%
- US stocks rise after core PCE misses expectations
- Core PCE rises 3% YoY vs 3.3% expected
- Fed October rate hike expectations fall to 37%
- Oil rises from a 3-week low
U.S. Stocks Rise after cooler-than-expected core PCE
U.S. stocks are rising and Treasury yields are falling after data showed that inflation increased at a cooler pace than expected, while U.S. consumer spending rose again in August.
U.S. core PCE, the Fed’s preferred gauge of inflation, remained unchanged at 3% annually, below the 3.3% increase that was forecast but still above the Fed’s 2% target. On a monthly basis, core PCE rose 0.2% in August, below expectations of 0.3%.
Meanwhile, inflation-adjusted personal spending climbed 0.6% in August from a month earlier, marking the largest monthly jump since March 2025.
The data suggests that the U.S. economy remains resilient despite elevated inflation. With the help of a stable jobs market, consumers remain comfortable spending even as prices rise. U.S. Q2 GDP was also revised higher to 2.2% annually, up from the previous reading of 1.5%, while Q1 growth was also revised higher.
Following the release of the data, markets reined in Fed rate hike expectations, which are now down to 37% for a 25-basis-point hike in October, from 70% last week. The key question now is whether cooler inflation can outweigh resilient consumer demand and stronger growth, limiting how quickly the Fed can ease policy even as markets price out an October hike.
Attention will now turn to U.S. jobs data on Friday. Expectations are for another solid month of job creation, with around 100K jobs expected to be added after 162K jobs were added in August.
Corporate Movers
Boeing is up 2% after securing a deal with the Defence Department to develop the next generation of U.S. fighter jets. The contract is worth $20 billion and will see Boeing develop the F/A-XX fighter.
Moderna is falling more than 6% after Citi downgraded the stock to sell. Analysts at the bank have set a price target 60% below Tuesday’s closing price, arguing that the current valuation cannot be justified.
S&P 500 Forecast – Technical Analysis
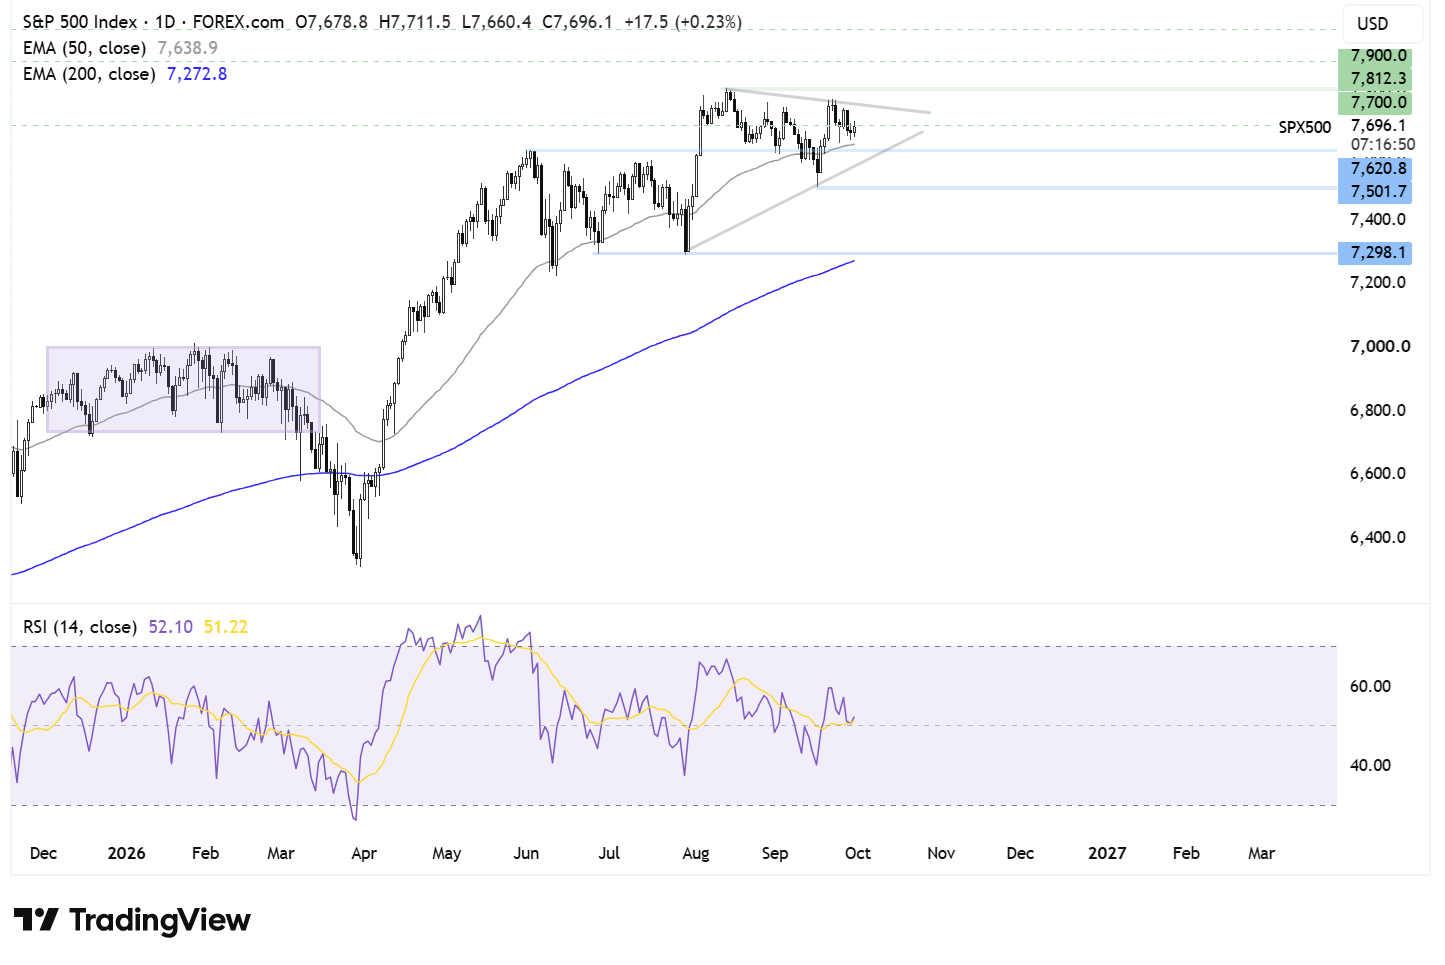
The S&P 500 trades in a symmetrical triangle pattern and is hovering around 7,700, near the midpoint of the pattern. The price holds above its 50- and 200-day EMAs, keeping the outlook constructive.
Buyers will look to rise above 7,765, the upper band of the falling trend-line resistance, to break out and bring 7,810 and fresh record highs into focus.
On the downside, support is seen at 7,450, the 50 EMA and June high. Below here, attention will turn to 7,575, the rising trend-line support, while a break below 7,500 would create a lower low and open the door to a deeper sell-off towards 7,300.
FX Markets – Dollar Rises, EUR/USD Recovers
The U.S. dollar is easing following the cooler-than-expected core PCE inflation data, which has resulted in markets reining in Fed rate hike expectations and pulling Treasury yields lower. The market is now pricing in just a 37% chance of an October hike, down from 70% yesterday.
EUR/USD is rising on the weaker U.S. dollar and following stronger-than-expected German inflation. German consumer prices rose 3.3% year-on-year in September, up from 2.9% in August and ahead of the 3.1% expected. German retail sales were also stronger than expected, rising 1.3% month-on-month in August after slumping in July.
GBP/USD is rising amid a weaker U.S. dollar and after stronger-than-expected UK GDP data. Figures from the ONS showed that GDP was revised higher to 0.5% in Q2, up from 0.4% in the preliminary reading.
The market is pricing in around 33 basis points of tightening from the Bank of England between now and the end of the year, and more than 100 basis points by the end of 2027.
Oil edges higher from a 3-week low
Oil prices are edging higher after President Trump denied being willing to ease sanctions on Iran, although gains remain limited by optimism over a recovery in Middle Eastern crude supply.
Brent is trading above $90 a barrel, with the December contract around $96, while WTI is near $89. Brent is on track for a 14% gain in September, its strongest monthly increase since July, compared with a 4% rise for WTI.
The Brent-WTI spread is at its widest in four months as markets assess potential U.S. restrictions on diesel exports, which could create an oversupply and encourage refiners to cut crude production.
Meanwhile, Qatar continues diplomatic efforts between Tehran and Washington, but prospects for a breakthrough remain uncertain.
Middle Eastern crude exports recovered to 16.32 million barrels per day in September, just 11% below pre-war levels. With supply recovering, concerns over shortages have eased, limiting upside pressure on prices.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P500 Forecast: SPX falls as Anthropic drops post IPO
U.S. stocks are trading mixed with tech leading the losses as the mood sours despite Anthropic’s record-breaking IPO yesterday, which failed to calm AI jitters and revive the AI trade.
DAX Under Pressure as Nvidia, AMD and Anthropic Fail to Lift Markets
European equities are heading into Friday with a clear risk-off bias as weakness in global technology stocks continues to weigh on sentiment. Despite strong results from NVIDIA and a record-breaking debut from Anthropic, investors are becoming increasingly selective about AI valuations, capital spending and regulatory risks. With semiconductor stocks under pressure, commodity prices weakening and geopolitical uncertainty persisting, the DAX enters the session facing its most important technical test in several weeks.

Gold and Silver's Deepening Dollar Dilemma
The dollar has broken higher, gold and silver have been crushed, and US financial conditions are tightening rapidly. Our historical analysis suggests this is no ordinary precious metals selloff.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.