



Recession concerns and a stronger US dollar send WTI back below $80
WTI suffered its worst day in 30 yesterday, with a combination of a stronger US dollar, recession concerns and weaker natural gas prices all playing their part for a bearish session.
Share this:


Recession fears continue to weigh no sentiment with Wall Street tracking the majority of Asian indices lower yesterday. Santa’s rally never materialised in December, and that negative sentiment has been carried over to the new year. Weak PMI data from China over the weekend and yesterday did not help either, with two separate manufacturing and service PMI reports all contracting which feeds back into the weak global growth narrative. Whilst China’s reopening partially offsets some of the doom and gloom, so rise of covid cases counters that upside somewhat.
Ultimately, we have entered the new year with a lot of uncertainty during a time of low liquidity. This has resulted in above-average moves, none of which I have too much confidence in – which basically means I’d prefer to remain nimble and not seek extended macro moves over the near-term.
WTI crude oil – daily chart:


WTI suffered its worst day in 30 yesterday, with a combination of a stronger US dollar, recession concerns and weaker natural gas prices all playing their part for a bearish session. A bearish outside day formed which markets a double top around $81.20, daily volume was above average (and its highest in 14 days) which adds weigh to the bearish reversal candle. Also note that previously the market has reversed lower around the 100-day EMA, yet here it is trying to turn lower around the 50-day EMA (which itself is below the 100-day EMA). A bearish divergence also formed on RSI ahead of the double top, therefore the bias is for another dip lower.
A break of the September low assumes bearish continuation, and next support resides around 72.50 – 73.40. In light of seeking to ‘remain nimble’, we prefer to stick to intraday timeframes in line with the daily bias.
Commitment of traders (managed funds) on WTI crude futures:
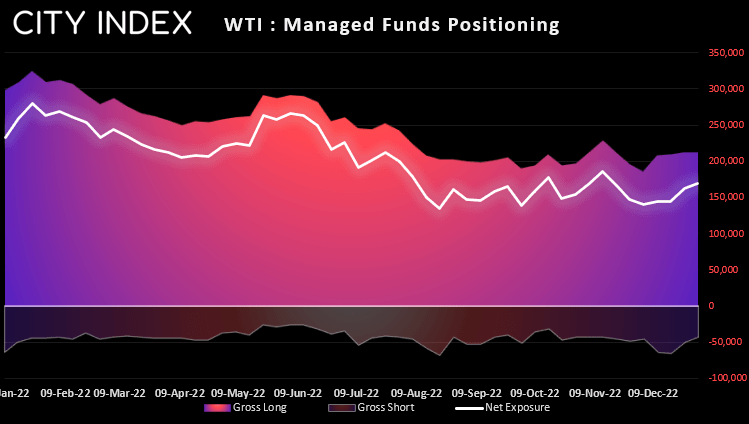

We can see that net-long exposure has been ticking higher on WTI for managed funds, but this is due to shorts being covered and not new longs being initiated in recent weeks. Given the negative sentiment then it’s plausible to suspect some of those bears will now be returning. But if or when we see gross longs increase and gross shorts decrease, we would be more confident in calling a bottom in oil. We’re just not there yet.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.