



S&P 500 Forecast: SPX falls as tech volatility continues
U.S. futures are pointing to a weaker start, led lower once again by technology stocks as AI jitters return amid mounting concerns over the cost of AI infrastructure and reports that OpenAI is considering delaying its IPO.
Share this:


US futures
Dow futures -0.2%, S&P futures -0.5% & Nasdaq futures -1.3%
In Europe
FTSE -1.1% & DAX -1.3%
- U.S futures fall with tech leading the move lower
- OpenAI is reportedly considering delaying its IPO until next year
- Stocks fall despite treasury yields weakening
- Oil falls 10% across the week
U.S. Futures Slip as AI Jitters Return
U.S. futures are pointing to a weaker start, once again led lower by technology stocks. AI jitters are returning amid mounting concerns over the cost of AI infrastructure and reports that OpenAI is considering delaying its IPO.
Reports suggest OpenAI could delay its planned IPO until 2027 following SpaceX's disappointing performance since its market debut and increased volatility across AI-related stocks.
This has been another volatile week for the technology sector. While AI optimism has been enough to drive markets higher for much of the past year, investors are becoming increasingly focused on whether the enormous capital spending required to build AI infrastructure will generate sufficient returns.
The recent pullback suggests the market is becoming more selective. Rather than simply buying the AI theme, investors are placing greater emphasis on earnings, valuations and evidence that AI investment is translating into profits.
Falling oil prices are pulling Treasury yields lower, helping to ease inflation concerns. However, this has provided little support for technology stocks, highlighting that AI valuation concerns are currently outweighing macroeconomic tailwinds.
Attention now turns to the University of Michigan Consumer Sentiment Index, which is expected to improve modestly to 50.0 in June from 48.9.
The survey follows yesterday's Core PCE data, which rose 3.4% year-on-year, in line with expectations. With inflation providing no major surprise, attention is already shifting towards next week's U.S. non-farm payrolls report, which could prove the next major catalyst for Fed expectations.
Corporate Movers
Chip makers are under pressure following reports that OpenAI may delay its IPO until 2027. Arm Holdings and Marvell Technology are down around 4%, while AMD is off 3.5% and Intel is down 3% in pre-market trading.
Memory stocks are also weaker as the technology sell-off continues. Micron is down over 4.5% after surging 16% on Thursday following its strong earnings report, while SanDisk is also trading lower.
Apple is rebounding modestly after falling more than 6% yesterday, its worst daily performance in over a year, after raising prices across several devices amid higher memory and storage costs.
Energy stocks are also under pressure as oil prices fall more than 3%, dragging the sector lower.
S&P 500 Forecast – Technical Analysis
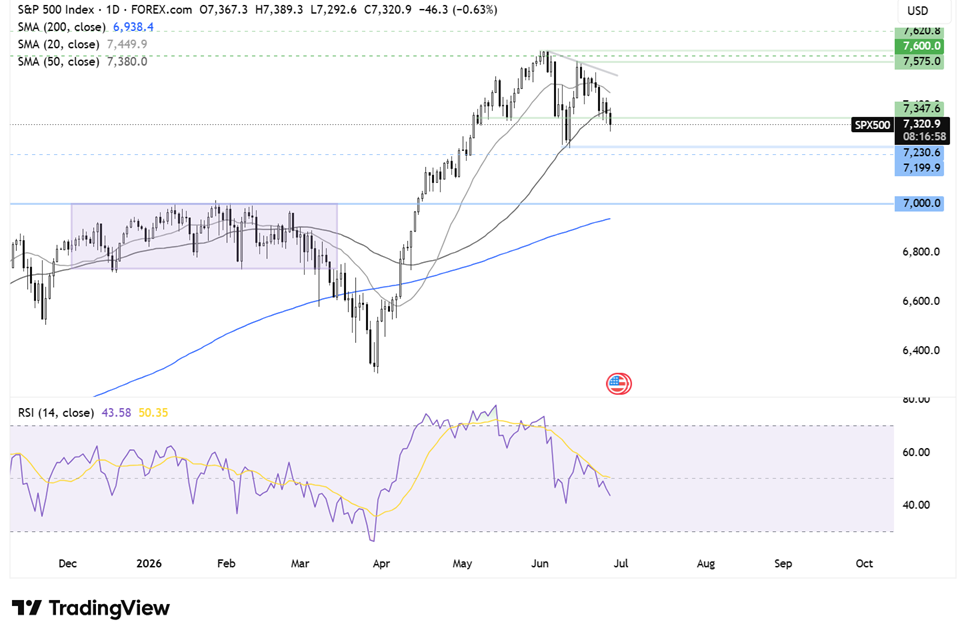
The S&P 500 recovery from 7,225 ran into resistance at 7,575, forming a lower high before reversing lower. The index has broken below the 50-day SMA and is currently testing support around 7,350.
The break below the 50-day SMA, combined with the RSI below 50, keeps sellers hopeful of further downside.
A move below 7,350 would expose 7,225, the June low, ahead of the psychological 7,200 and 7,000 levels.
Any recovery would first need to reclaim the 50-day SMA around 7,380 before targeting 7,500 and the falling trendline resistance. A move above 7,575 would create a higher high and bring the record high at 7,620 into focus.
FX Markets – USD Eases After Inflation Data
The U.S. dollar is easing on Friday as Treasury yields move lower after Core PCE inflation met expectations, reducing fears of an even more hawkish repricing from the Federal Reserve.
EUR/USD is rising back above 1.1400 as lower oil prices improve the outlook for the Eurozone, which is heavily dependent on imported energy. However, falling consumer inflation expectations could reduce pressure on the ECB to tighten policy further, limiting euro gains.
GBP/USD has recovered above 1.3200 alongside the softer U.S. dollar. However, gains remain cautious amid continued political uncertainty in the UK and a lack of clarity over the economic policies of the likely next Prime Minister, Andy Burnham.
Oil falls almost 10% across the week
Oil prices are falling more than 3% on Friday and are on course for a weekly decline of almost 10% as supply concerns continue to fade.
Crude shipments through the Strait of Hormuz have risen to their highest levels since the Middle East conflict began, supported by the ceasefire agreement and the reopening of the shipping route.
At the same time, demand remains subdued, particularly from China, leaving the market increasingly focused on the prospect of improving supply rather than geopolitical disruption.
Separately, Russia is considering a temporary diesel export ban following supply disruptions caused by Ukrainian drone attacks. While this could tighten refined fuel markets, it has done little to offset the broader improvement in crude oil supply.



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
WTI crude squeezed between Hormuz risk and diesel ban speculation
WTI is being pulled in opposite directions as Hormuz risk collides with growing political pressure over US diesel prices.

S&P 500, Nasdaq, Dow Forecast: Wall Street Split Widens Into Month-End 9 26 2026
Nasdaq strength contrasts with mounting Dow pressure as rising Treasury yields raise the stakes for stocks heading into the monthly close.

Equity Indices Q4, 2026 Outlook: Cracks Begin to Show
There's still an open door for a melt-up in the S&P 500 and Nasdaq but the Dow and Russell 2000 are looking more vulnerable, and until calm hits the Treasuries market there's a higher probability for volatility. The big question is whether that's a next quarter theme or not.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.