



WTI crude squeezed between Hormuz risk and diesel ban speculation
WTI is being pulled in opposite directions as Hormuz risk collides with growing political pressure over US diesel prices.
Share this:
- Brent-WTI spread widens sharply as underlying drivers diverge
- US diesel prices surge 42.6% since July 10
- Trump’s 2pm ET announcement looms as key event risk
Headlines released over the weekend have provided both WTI crude bulls and bears with ammunition for their views. Iran’s ceasefire proposal, which could have reopened the Strait of Hormuz, was knocked back by US President Donald Trump, providing a tailwind for crude prices. At the same time, speculation that Trump may announce a US diesel export ban has contributed to downside pressure on WTI, creating an uncertain and volatile environment entering the new week.
Same spread widening, very different drivers
That push and pull is showing up in the sharp widening between Brent and WTI futures contracts for November delivery, shown in the graphic below, with the premium for Brent over WTI widening to around $13 a barrel, close to the extremes seen earlier this year.
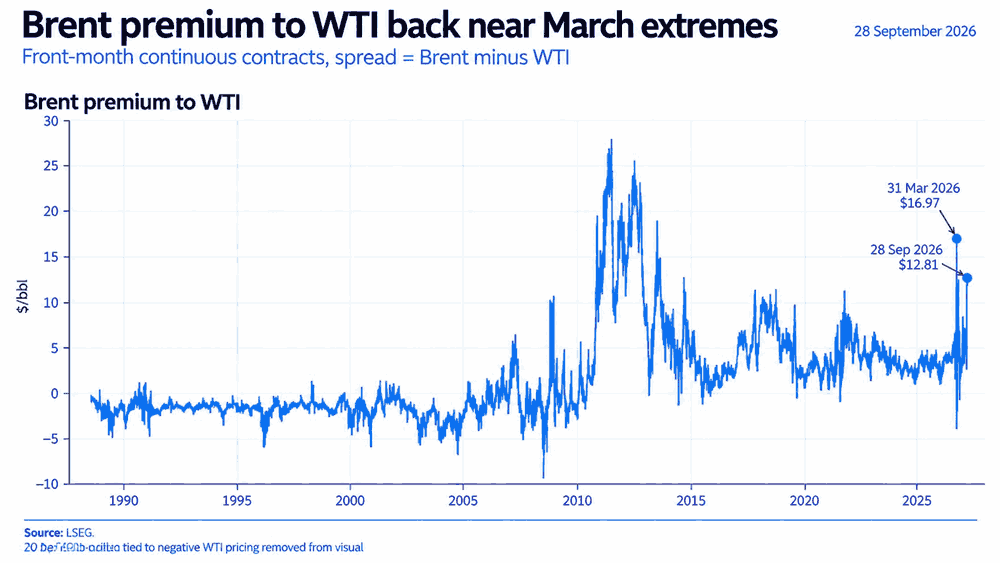
Source: LSEG
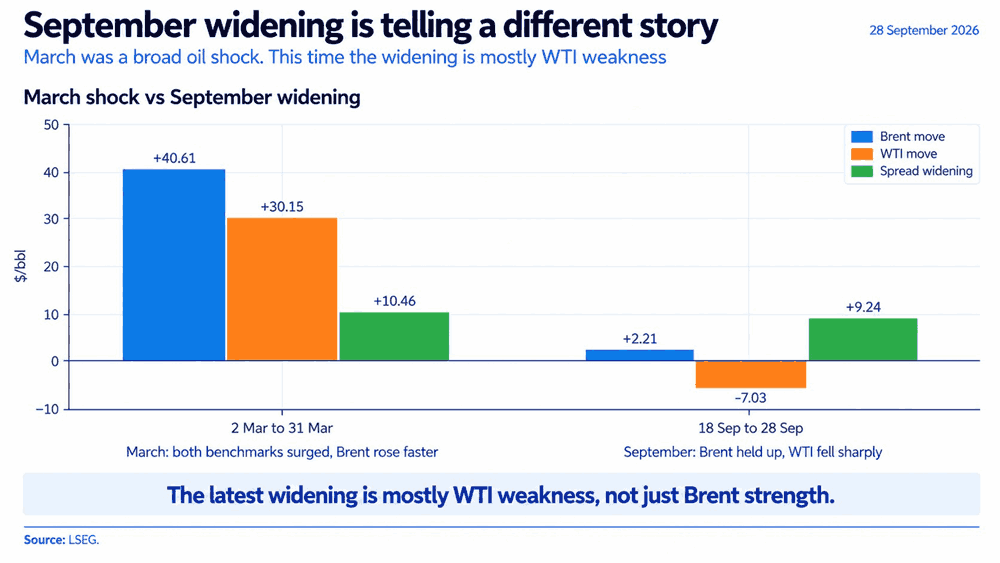
The difference this time is what’s driving it. In March, both contracts surged as markets priced the risk of major disruptions to global crude supply, with Brent simply rising faster given its role as the global benchmark. Since September 18, however, Brent is a little more than $2 higher while WTI is down around $7, widening the spread by more than $9 a barrel.
Source: LSEG
I don’t pretend to be a specialist in refinery economics, but from what I’ve read so far, the narrative is that if US refiners are restricted from exporting diesel, the incentive to process as much crude as possible diminishes because there are fewer markets to sell into. In a nutshell, it implies weaker refinery demand for WTI relative to Brent.
Record US diesel prices turn up political heat
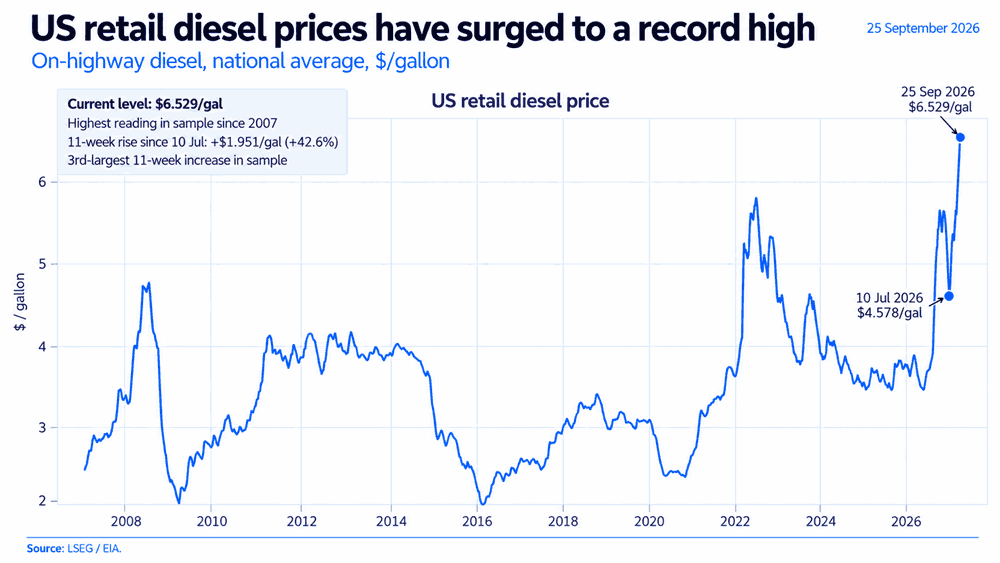
Taking a step back to explain why a diesel export ban is being considered, US highway diesel prices have surged to a record $6.53 a gallon, up almost $2, or 42.6%, since July 10. The political pressure on Trump and Republican members of Congress is clearly there, given the hit to households and businesses across Middle America, including much of their electoral base, ahead of the November 3 midterm elections.
Source: LSEG
That makes Trump’s scheduled 2:00pm ET announcement from the Oval Office an obvious event risk later Monday. Nobody knows what the announcement is about, but if it does relate to diesel export restrictions, it could go a long way towards determining whether the recent pressure on WTI relative to Brent extends or starts to unwind.
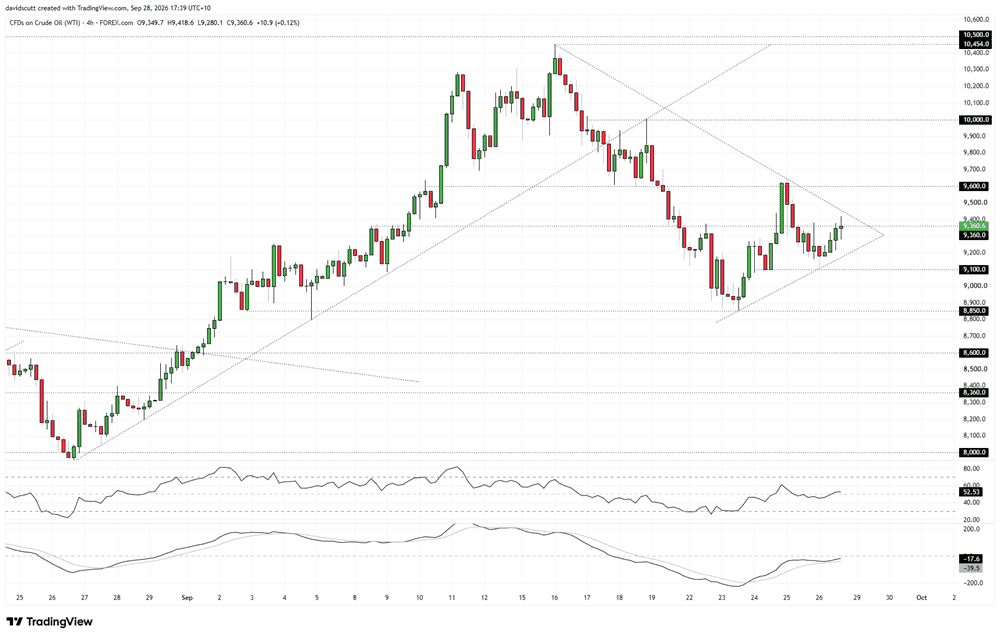
WTI levels as price action tightens
Given the degree of uncertainty, I’m reluctant to put too much weight on technical signals right now. That said, WTI is still showing enough respect for known levels to give us a framework to work with.
Source: TradingView
The price is currently trading either side of $93.60, a level that has repeatedly acted as resistance and support over the past few weeks. It also sits in the middle of the current coiling price action.
We’ve only had a couple of touches on either side of the potential triangle, so I wouldn’t read too much into it yet. The top side comes in around $94.65 today, with the lower side near $91.80, suggesting some form of breakout may be approaching.
That makes $93.60 a level that can potentially be used to build setups around. On the topside, $96 is the first level I’m watching, having acted as resistance, support and then resistance again last week. Above that, $100 is the next obvious level after the price stalled there on September 18.
Underneath, a clean break of the rising trendline from the September 23 low would put $91 back in focus, followed by $88.50 and then $86, all levels that have been respected previously.
The oscillators are neutral, so I’m putting far more weight on price action and the headlines that may accompany it rather than holding a strong directional bias.
Over the medium and longer term, there’s no shortage of crude globally. If the conflict were to end and the supply threat fade, that would likely create immediate downside risk for both WTI and Brent.
Related tags:


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
British Pound Technical Outlook: GBP/USD Rebound Challenges September Downtrend 9 30 2026
Sterling has rallied sharply from key support, with GBP/USD at an inflection point that could determine whether a larger recovery is underway.

S&P 500 Forecast: SPX rises after cooler-than-expected inflation data
U.S. stocks are rising and Treasury yields are falling after data showed that inflation increased at a cooler pace than expected, while U.S. consumer spending rose again in August.


Treasury Yields Lose Momentum as Energy ETF Retreats
The 10-year Treasury yield is testing a resistance zone respected since the 1920s, as bearish RSI divergence signals fading upside momentum.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.