

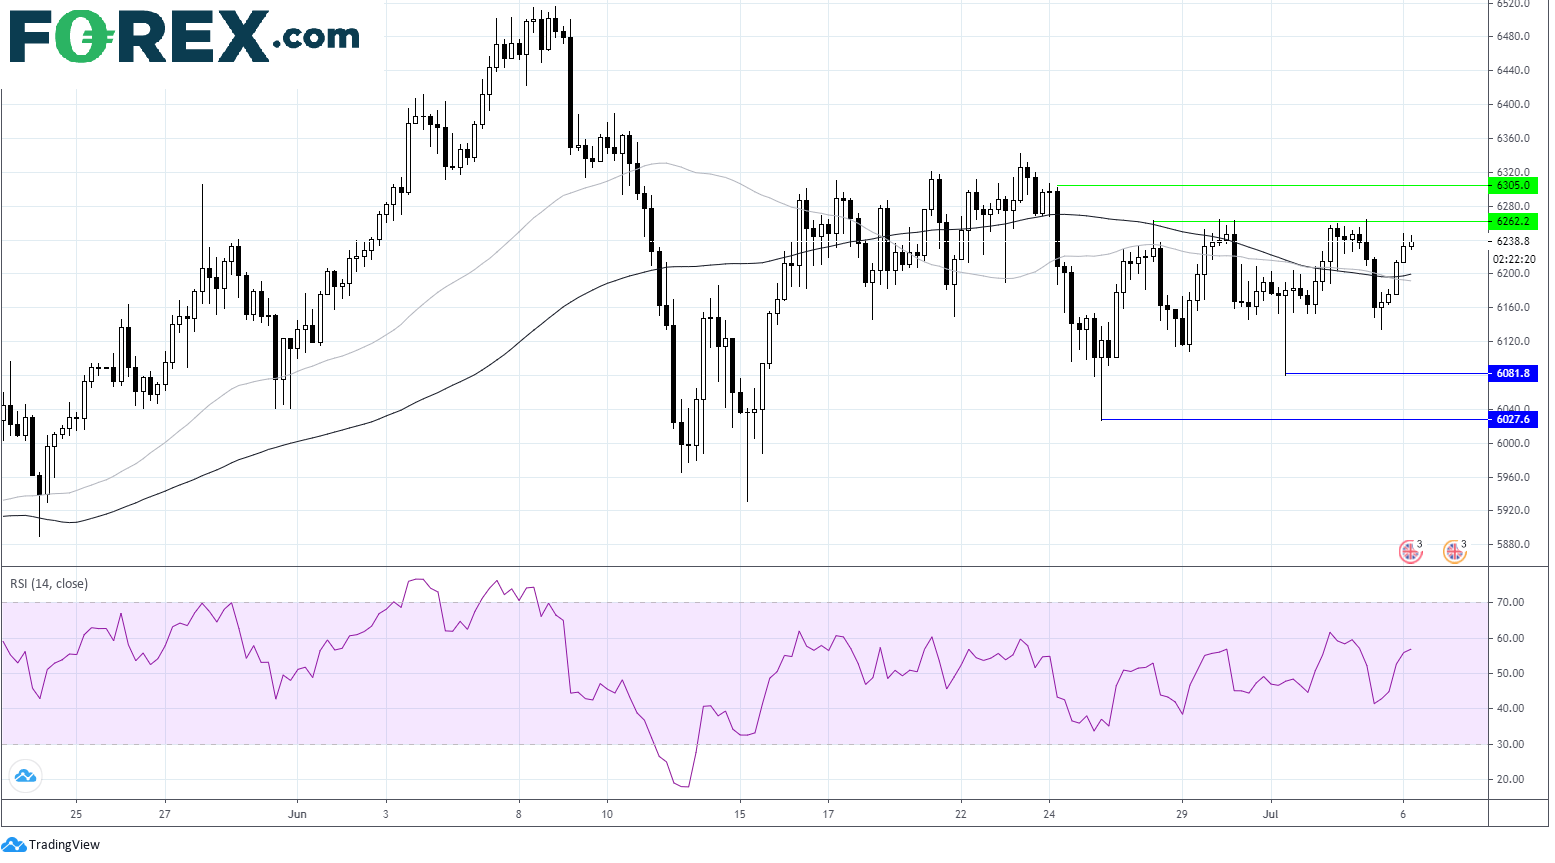



Stocks Start Week With Gains
Economic recovery optimism is in full swing as the new week kicks off overshadowing concerns of rising covid numbers and second wave fears.
Share this:

Economic recovery optimism is in full swing as the new week kicks off, driving Asian and European markets firmly higher whilst overshadowing concerns of rising covid numbers and second wave fears.
According to the Word Health Organisation a record 212,000 new daily coronavirus cases were reported, with US, Brazil and India reporting the largest number of increases. However, the US reported 53,000 which is a slight improvement on the 57,000 daily cases reported on Friday. Still with July 4th celebrations dominating across the weekend, there is a good chance that this number will rise again in the coming weeks. What is clear is that the US never got the outbreak under control before reopening the economy, putting the world’s largest economy in the firing line for a second wave.
China blue chips at 5 year high
Even as the coronavirus statistics show concerningly high increases the mood in the market remains bullish as investors place firm belief in the view that a revival in Chinese activity will help sustain global economic growth.
Even as the coronavirus statistics show concerningly high increases the mood in the market remains bullish as investors place firm belief in the view that a revival in Chinese activity will help sustain global economic growth.
Chinese blue chips soar almost 5%, adding to a 7% jump last week, taking the stocks to a 5 year high. High volumes suggest that investors are tactically opting for a stronger and speedier recovery in Asia over the US.
This week as a whole is relatively quiet on the economic data front, compared to last week. Today German factory orders showed that the largest economy in the Eurozone was rebounding with orders increasing +10% short of the 15% forecast, but still a vast improvement on May’s -28% decline. Looking ahead Eurozone investors sentiment and retail sales will be in focus.
GBP under pressure amid negative rates talk
The Pound is a notable decliner versus the Euro in early trade after a report surfaced that BoE Governor Andrew Bailey and Co are still seriously considering negative interest rates in the UK in order to boost the economic recovery. Negative rates would pressurise already squeezed lending margins at the banks. The banks could lag other sectors on the open.
This weekend saw the UK hospitality sector reopen with pubs, restaurants and har dressers among those that could reopen. With more and more of the economy reopening the economic rebound should start to gather pace in the UK after a very slow few month.
UK construction PMI is due to show that the contraction in the sector slowed, increasing from 28.9 to 47.
The final US service sector PMI is also due late today. Expectations are also for the contraction to have slowed. Meanwhile the closely watched ISM non manufacturing PMI is expected to reach 50, the level which separates expansion from contraction.
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD, FTSE 100 Forecast: Two trades to watch 1507
EUR/USD rises after weaker US CPI, PPI up next. FTSE 100 falls as weak China GDP data hits miners.

FTSE 100, USD/JPY Forecast: Two trades to watch
FTSE eases modestly despite inflation unexpectedly holding steady. USD/JPY drifts lower ahead of the FOMC rate decision.
EUR/USD, FTSE 100 Forecast: Two trades to watch 21-05-26
EUR/USD slips below 1.16 as weak eurozone data weighs on sentiment. FTSE 100 slips as oil prices rebound and caution returns.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.