



US open: Stocks extend gains as earnings impress
Stocks rise , adding to yesterday's strong rally as upbeat earnings distract from inflation, recession and hawkish Fed fears.
Share this:

US futures
Dow futures +2% at 30825
S&P futures +2.2% at 3760
Nasdaq futures +2.5% at 11340
In Europe
FTSE +1.3% at 7011
Dax +2% at 12912
Netflix is due after the close
US stocks are set to head higher, extending gains from the previous session as earnings remain in focus.
Stocks posted strong gains yesterday, with the Nasdaq rising 3,4% and the S&P500 booking gains of 2.6% after upbeat banking results and as investors positioned themselves for tech earnings.
Corporate earnings are stealing the show and overshadowing recession concerns. Those same recession fears had meant that the bar was low heading into earnings, raising the likelihood of beating estimates.
The macroeconomic calendar is quiet, with just US industrial output due to be released.
Even though stocks are rising, as earnings provide a welcomed distraction, this move higher is still a bear market rally rather than anything more meaningful. Cheap valuations and positive results have seen investors jump back into the market.
However, with inflation, hawkish central banks, and recession fears still providing headwinds to the market, there are questions about how high this rally can go. Inflation has proved to be stickier than initially expected, and the Fed could still take the terminal interest rate higher, making any meaningful recovery in stocks unlikely at this point.
Corporate news:
Goldman Sachs is rising over 2% pre-market after earnings and revenue beat forecasts. The investment bank also announced that it would be reorganizing its business into three units as part of a significant restructuring.
Netflix is due to report after the market close. Expectations are for 1 million new subscribers. EPS is expected to fall to $2.75 from $3.19 a year earlier. Revenue is expected to rise to $7.84 billion from $7.48 billion a year earlier.
Where next for the S&P500?
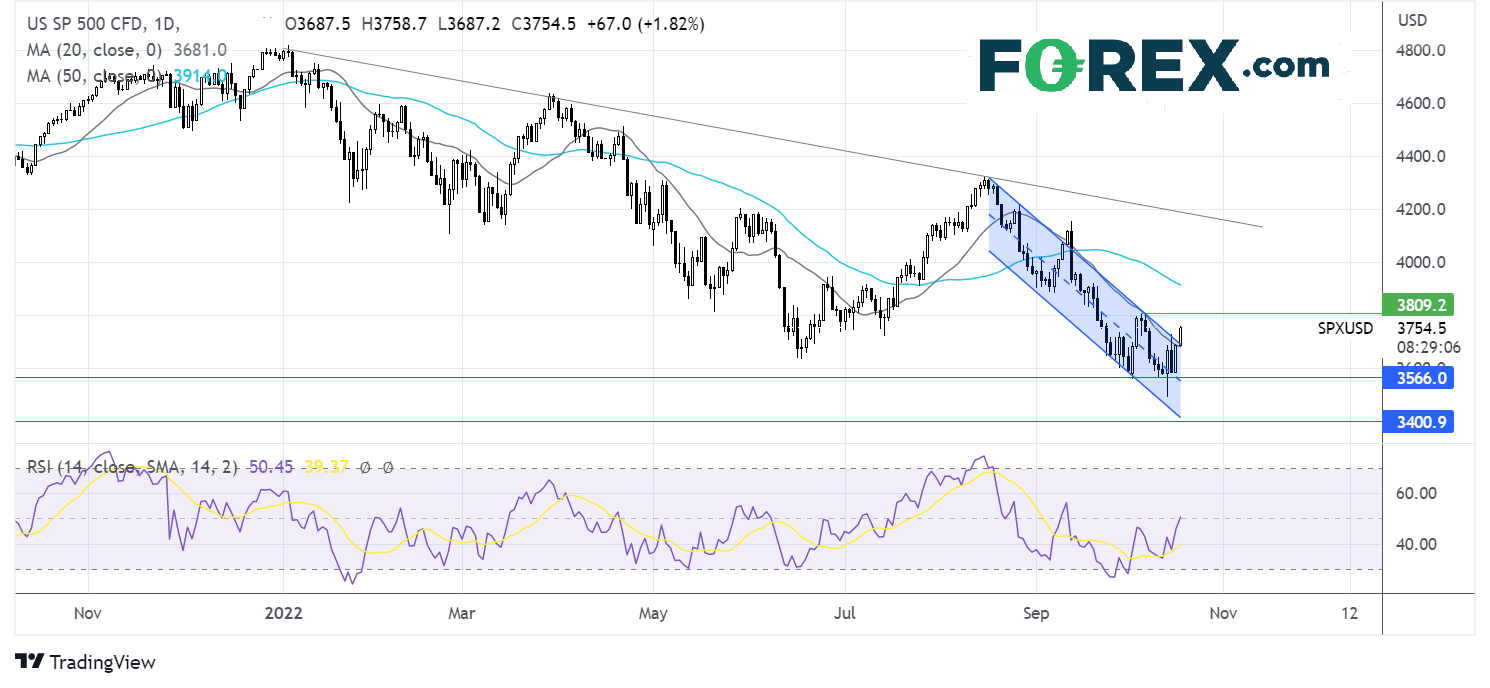
The S&P has risen out of the falling channel within which it has traded since mid-August. The break above the falling trendline, and the 20 sma, combined with the RSI moving back up to the 50 level keeps buyers hopeful of further upside. Buyers will now look to re-take the 3800 October high to expose the 50 sma at 3910. Meanwhile, sellers could look for a move below 3690 to re-entre the falling channel, bringing 3560 The October 3 low back into play.
FX markets – USD rises, GBP falls
The USD is rising after losses in the previous session. The upbeat market mood hit demand for the greenback. However, any falls southwards could be seen as buying opportunities. While the Fed intends to hike rates aggressively and for longer, the USD is likely to remain supported.
EUR/USD is falling as ZEW German economic sentiment remains weak in October. Sentiment did tick higher from September to 59.2, up from 61.9. However, this remains weak on a historical basis as fears over surging energy prices continue to weigh on sentiment.
GBPUSD is coming under pressure to snap a two-day winning as investors start to reprice the possibility of a large rate hike in November after the Chancellor’s U-turn on tax cuts. Earlier in the month BoE Governor Andrew Bailey had said that the central bank could raise rates by 1%, this may not now be necessary. Following high levels of volatility in the pound and the gilt market, things are starting to calm. That said, the outlook for the UK economy is still weak
GBP/USD -0.5% at 1.13
EUR/USD -0.14% at 0.9827
Oil slips for a third day
Oil prices are slipping lower for a third straight session. Oil has fallen around 5% over the past 3 sessions. While OPEC+ cutting oil output has helped to support the price, rising fears of a recession is hurting the demand outlook.
The fall in the USD yesterday failed to lift the price of oil. A weaker USD makes oil cheaper for buyers of other currencies.
Instead, China’s fuel demand outlook was also dragging on the price after the world’s largest oil importer announced that it would not be releasing Q3 GDP, retail sales or trade data. This is most likely due to the 20th Communist National Congress taking place this week.
US crude oil stockpile data is due to be released later and is expected to have risen for a second straight week.
WTI crude trades -1.1% at $84.90
Brent trades -1.2% at $91.10
Looking ahead
N/A
US futures
Dow futures +2% at 30825
S&P futures +2.2% at 3760
Nasdaq futures +2.5% at 11340
In Europe
FTSE +1.3% at 7011
Dax +2% at 12912
Learn more about trading indices
Netflix is due after the close
US stocks are set to head higher, extending gains from the previous session as earnings remain in focus.
Stocks posted strong gains yesterday, with the Nasdaq rising 3,4% and the S&P500 booking gains of 2.6% after upbeat banking results and as investors positioned themselves for tech earnings.
Corporate earnings are stealing the show and overshadowing recession concerns. Those same recession fears had meant that the bar was low heading into earnings, raising the likelihood of beating estimates.
The macroeconomic calendar is quiet, with just US industrial output due to be released.
Even though stocks are rising, as earnings provide a welcomed distraction, this move higher is still a bear market rally rather than anything more meaningful. Cheap valuations and positive results have seen investors jump back into the market.
However, with inflation, hawkish central banks, and recession fears still providing headwinds to the market, there are questions about how high this rally can go. Inflation has proved to be stickier than initially expected, and the Fed could still take the terminal interest rate higher, making any meaningful recovery in stocks unlikely at this point.
Corporate news:
Goldman Sachs is rising over 2% pre-market after earnings and revenue beat forecasts. The investment bank also announced that it would be reorganizing its business into three units as part of a significant restructuring.
Netflix is due to report after the market close. Expectations are for 1 million new subscribers. EPS is expected to fall to $2.75 from $3.19 a year earlier. Revenue is expected to rise to $7.84 billion from $7.48 billion a year earlier.
Where next for the S&P500?
The S&P has risen out of the falling channel within which it has traded since mid-August. The break above the falling trendline, and the 20 sma, combined with the RSI moving back up to the 50 level keeps buyers hopeful of further upside. Buyers will now look to re-take the 3800 October high to expose the 50 sma at 3910. Meanwhile, sellers could look for a move below 3690 to re-entre the falling channel, bringing 3560 The October 3 low back into play.

FX markets – USD rises, GBP falls
The USD is rising after losses in the previous session. The upbeat market mood hit demand for the greenback. However, any falls southwards could be seen as buying opportunities. While the Fed intends to hike rates aggressively and for longer, the USD is likely to remain supported.
EUR/USD is falling as ZEW German economic sentiment remains weak in October. Sentiment did tick higher from September to 59.2, up from 61.9. However, this remains weak on a historical basis as fears over surging energy prices continue to weigh on sentiment.
GBPUSD is coming under pressure to snap a two-day winning as investors start to reprice the possibility of a large rate hike in November after the Chancellor’s U-turn on tax cuts. Earlier in the month BoE Governor Andrew Bailey had said that the central bank could raise rates by 1%, this may not now be necessary. Following high levels of volatility in the pound and the gilt market, things are starting to calm. That said, the outlook for the UK economy is still weak
GBP/USD -0.5% at 1.13
EUR/USD -0.14% at 0.9827
Oil slips for a third day
Oil prices are slipping lower for a third straight session. Oil has fallen around 5% over the past 3 sessions. While OPEC+ cutting oil output has helped to support the price, rising fears of a recession is hurting the demand outlook.
The fall in the USD yesterday failed to lift the price of oil. A weaker USD makes oil cheaper for buyers of other currencies.
Instead, China’s fuel demand outlook was also dragging on the price after the world’s largest oil importer announced that it would not be releasing Q3 GDP, retail sales or trade data. This is most likely due to the 20th Communist National Congress taking place this week.
US crude oil stockpile data is due to be released later and is expected to have risen for a second straight week.
WTI crude trades -1% at $84.90
Brent trades -1.2% at $91.10
Learn more about trading oil here.
Looking ahead
N/A
Related tags:
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
Gold forecast: XAU/USD could take a larger dive after the big rise in yields
Gold prices have been falling in the last few days after last week’s post-FOMC pop faded amid rising interest rate expectations, higher oil prices and a strengthening US dollar. As before, I wasn’t convinced gold would thrive in the current macro backdrop.

Gold, silver slammed as hawkish Fed repricing reignites dollar upside
Gold and silver had held up surprisingly well against surging US yields. Wednesday’s DXY breakout may have changed that equation.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.