


USD/JPY and DXY Price Forecast: Bullish Rebound Faces Overbought Risks
Despite mounting geopolitical risks, crude oil prices have declined more than 10% from their monthly highs. Combined with overbought momentum readings on the DXY and dollar pairs, this increases the risk of a near-term reversal.
Share this:
Despite mounting geopolitical risks, crude oil prices have declined more than 10% from their monthly highs. Combined with overbought momentum readings on the DXY and dollar pairs, this increases the risk of a near-term reversal.
The DXY is also testing the lower boundary of its previous 2026 uptrend from below, creating a critical technical juncture.
The drawdown in crude may reflect market expectations of near-term resolutions, alongside increased Saudi Gulf exports following the disruption to the East-West pipeline. Related article: Crude Oil Weekly Outlook: Saudi–Houthi Escalation vs Key Resistance
This setup challenges hawkish Fed expectations for the October meeting, particularly if crude prices continue to decline below recent lows near $90 for WTI and $96 for Brent.
I analyzed these charts in my latest webinar
Register here for the next session
For USD/JPY, the divergence in central-bank guidance remains important. Hawkish Fed expectations, with rate-hike odds above 50% for October, contrast with expectations that the Bank of Japan may hold rates at its next meeting. This divergence continues to support the dollar against the yen unless broad-based dollar weakness emerges alongside a reversal in rate-hike expectations.
DXY Daily Time Frame — Log Scale
Source: TradingView
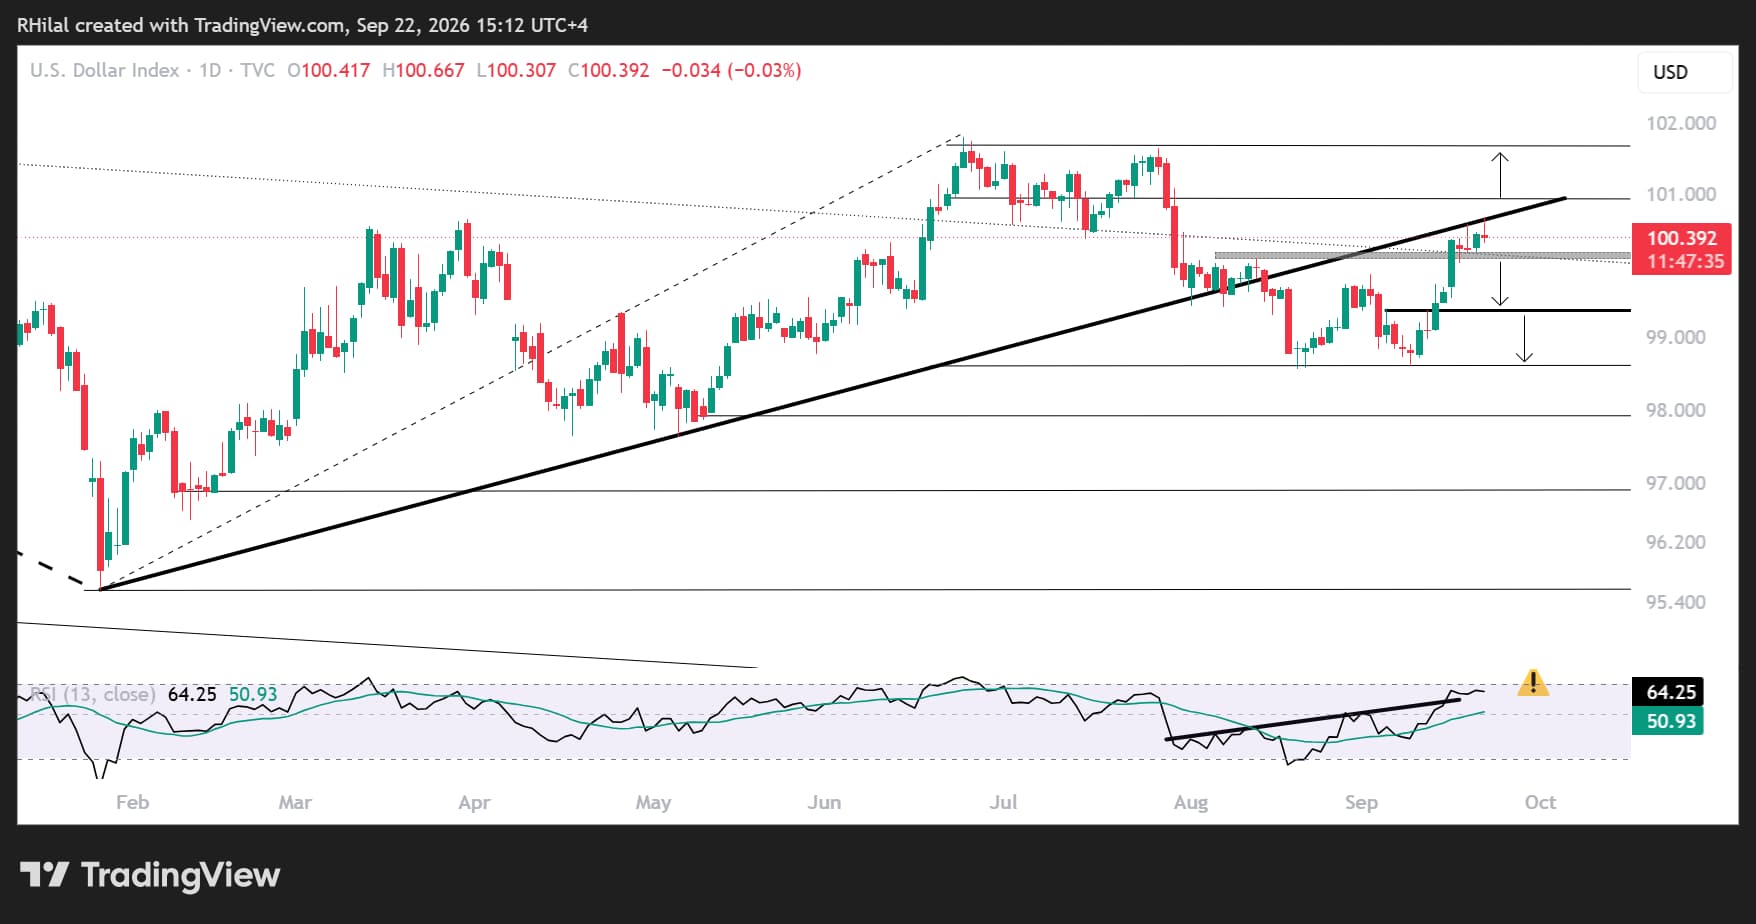
On the daily time frame, the DXY’s bullish rebound from the 98.50 support level—the 50% retracement of the 2026 advance—is currently retesting the 2026 uptrend from below near 100.50. However, daily momentum is becoming overbought, similar to readings observed near previous yearly highs.
A breakout above 100.50 would place the DXY back within the 2026 uptrend, targeting 101.00 and 101.80 before confirming new yearly highs. Such a move could extend pressure on precious metals and FX pairs facing a stronger dollar.
On the downside, a reversal below 100.00 would expose support at 99.30 and 98.50 once again, before confirming a potential return toward the yearly lows.
DXY Monthly Time Frame — Log Scale
Source: TradingView
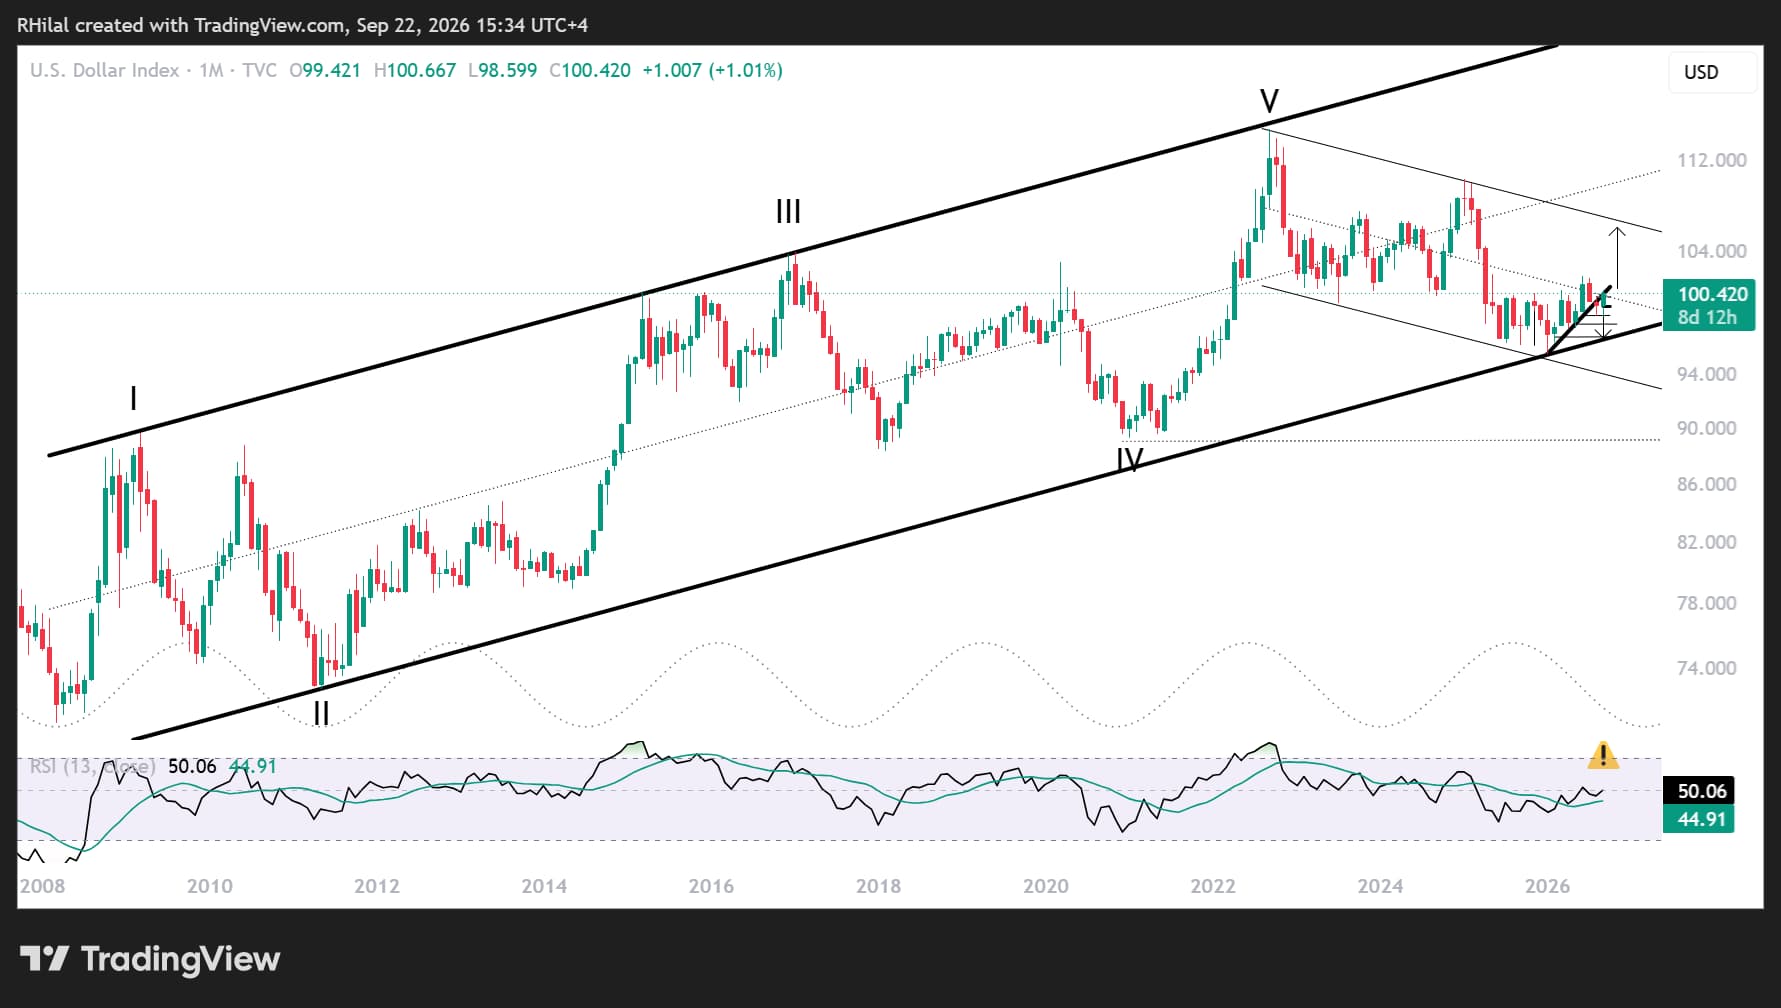
Although a drawdown toward the yearly lows may appear significant, it would remain consistent with the boundaries of the uptrend established since 2008. The 95.00 area therefore represents a critical long-term level between a potential bearish structural shift in the dollar and bullish continuation.
This perspective also aligns the DXY with the midpoint of the declining channel established since 2022. A clean monthly close above 101.80 could open the door toward the channel’s upper boundary near 107.00.
USD/JPY Weekly Time Frame — Log Scale
Source: TradingView
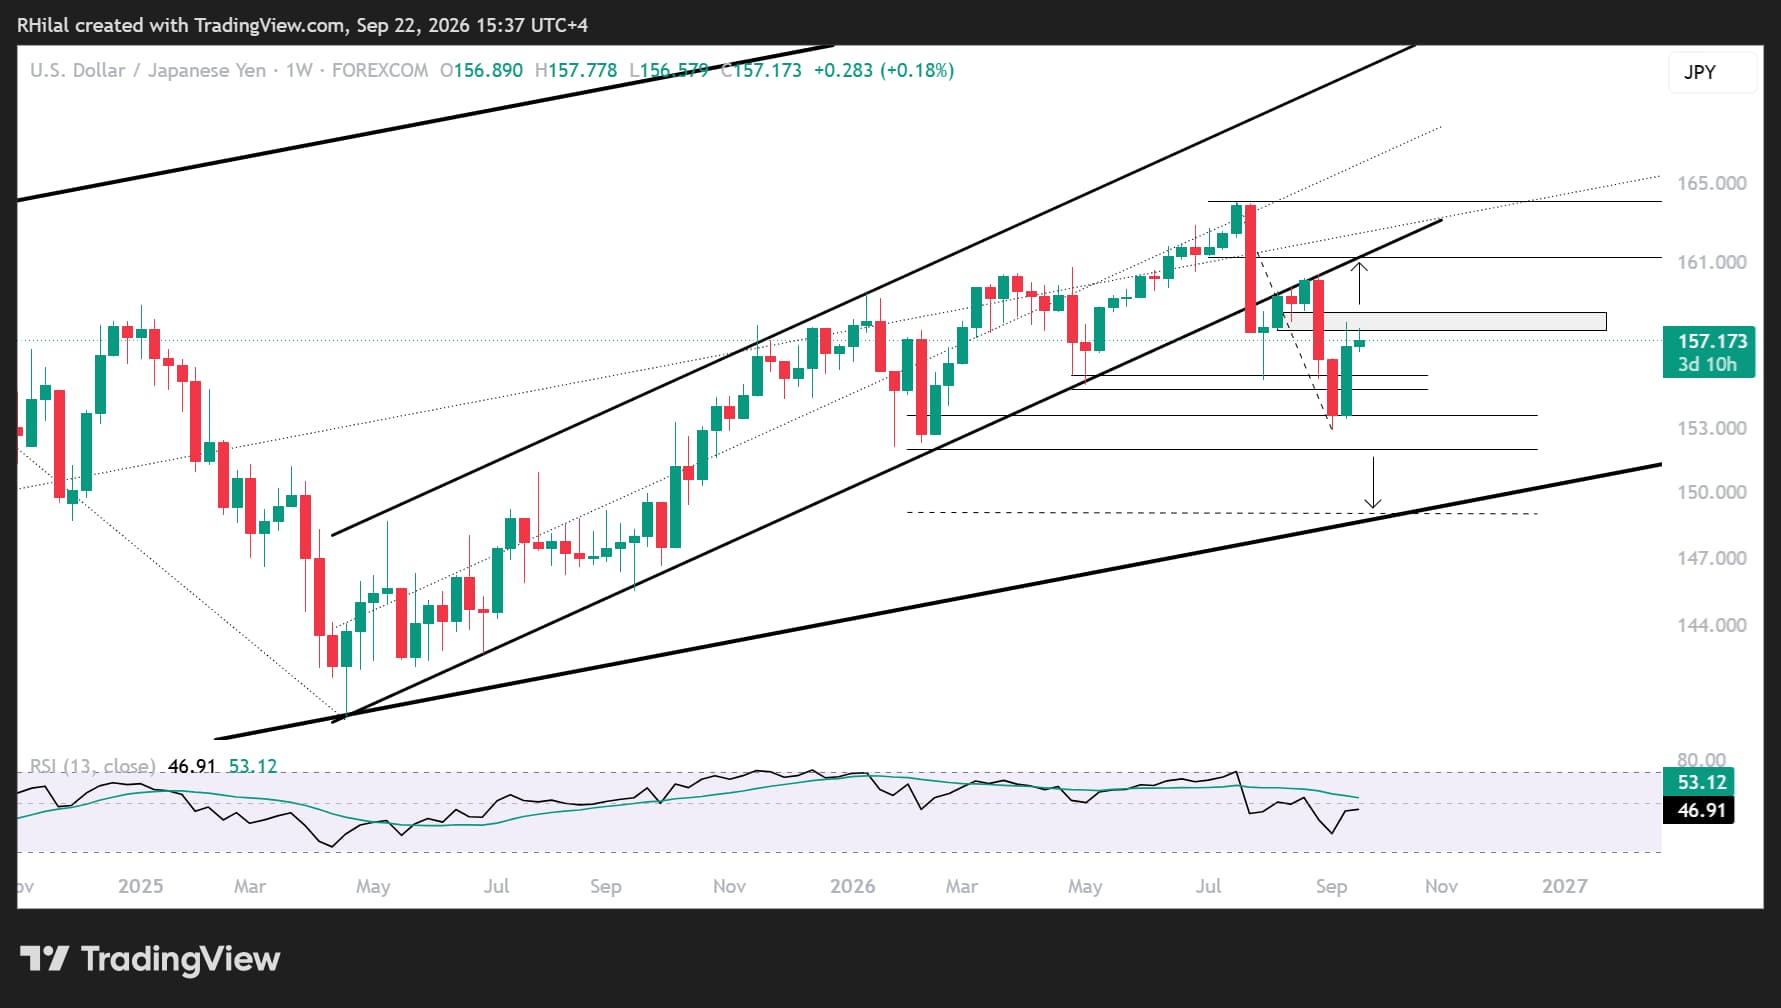
From a weekly perspective, USD/JPY’s breakdown below the April 2025–July 2026 uptrend channel puts the latest decline into context. The pair is now approaching the lower boundary of the broader uptrend established since 2023.
This reinforces the short-term downside risk while maintaining a longer-term bullish outlook. That outlook would weaken if USD/JPY closes below 152.00 and 149.00, corresponding approximately to the 61.8% and 78.6% retracement levels of the 2025–2026 advance.
On the upside, sustained closes above the Fibonacci extension levels at 154.80 and 158.40 would expose resistance at 161.30. This would place the pair back within the year-long uptrend and potentially open the way toward yearly highs near 164.00, raising the possibility of decade highs and renewed pressure on the Bank of Japan and the yen.
Dollar resistance levels, alongside declining crude prices, remain key to establishing the final-quarter outlook as the U.S. midterm elections approach and geopolitical signals remain mixed.
A renewed rise in crude and Treasury yields above their September highs, combined with renewed dollar strength, would be required to confirm a re-escalation in geopolitical risk and a broader risk-off sentiment toward year-end.
Written by Razan Hilal, CMT
Follow on X: @Rh_waves


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
GBP/USD, DJIA Outlook: Support Levels Meet Oversold Risks
GBP/USD and the Dow test key support levels as rising Treasury yields, Fed rate-hike expectations and oversold momentum increase reversal risks.

Gold forecast: XAU/USD could take a larger dive after the big rise in yields
Gold prices have been falling in the last few days after last week’s post-FOMC pop faded amid rising interest rate expectations, higher oil prices and a strengthening US dollar. As before, I wasn’t convinced gold would thrive in the current macro backdrop.


Oil, USD/JPY Forecast: Two trades to watch
Oil recovers above $90 amid a lack of progress in US-Iran diplomacy. USD/JPY rises to 158 on widening Fed-BoJ policy outlook.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.