



USD/JPY outlook: Hawkish Fed recalibration pressures the yen
Stronger US growth momentum and rising Treasury yields are keeping USD/JPY pointed higher, even as Japanese policymakers try to limit the pressure building across domestic markets.
Share this:
- USD/JPY correlations with front-end US yields remain historically elevated
- US economic surprises rebound as Japan’s growth momentum cools
- Intervention remains the clearest threat to the bullish trend
USD/JPY has clawed back a significant chunk of the intervention-driven collapse seen at the start of this month, reclaiming 158 on Wednesday ahead of the return of Japanese markets following a five-day long weekend.
While much has been made of the Bank of Japan’s hawkish tilt seen recently and the ongoing threat of intervention, not only from Japan’s Ministry of Finance but also the US Treasury, make no mistake: it’s the US side of the equation that’s driving the bus right now.
Treasury yields have ripped higher again as markets respond to a strengthening nominal growth outlook, which is seeing markets move to price in the risk of three and a half additional rate hikes from the Federal Reserve by June next year.
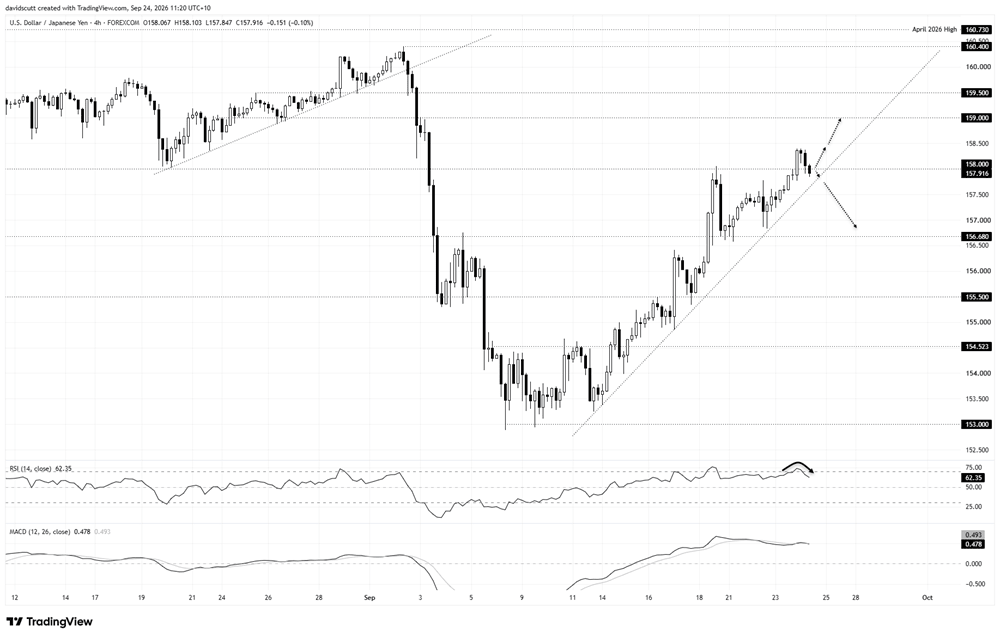
USD/JPY has followed almost mechanically in response to that hawkish shift, with the recovery from beneath the 153 support zone developing into yet another sustained series of higher highs and higher lows on the four-hour chart below.
Source: TradingView
US rates dominate the directional signal
Correlation analysis underscores the linkage between Treasury yields and USD/JPY, with its relationship with US two-year yields climbing to +0.85 over the past week and roughly +0.90 against US-Japan two-year yield spreads.
While neither are extreme for the five-day window, they are very elevated compared to historical norms. What we're seeing over the past month is a gradual strengthening in the relationship between USD/JPY and front-end yields, with the influence of the intervention episode at the start of September fading into the distance.
Without that in the mix, it suggests USD/JPY traders should have their eyes fixated on shifts in the front of the US Treasury curve.
US growth momentum widens the gap
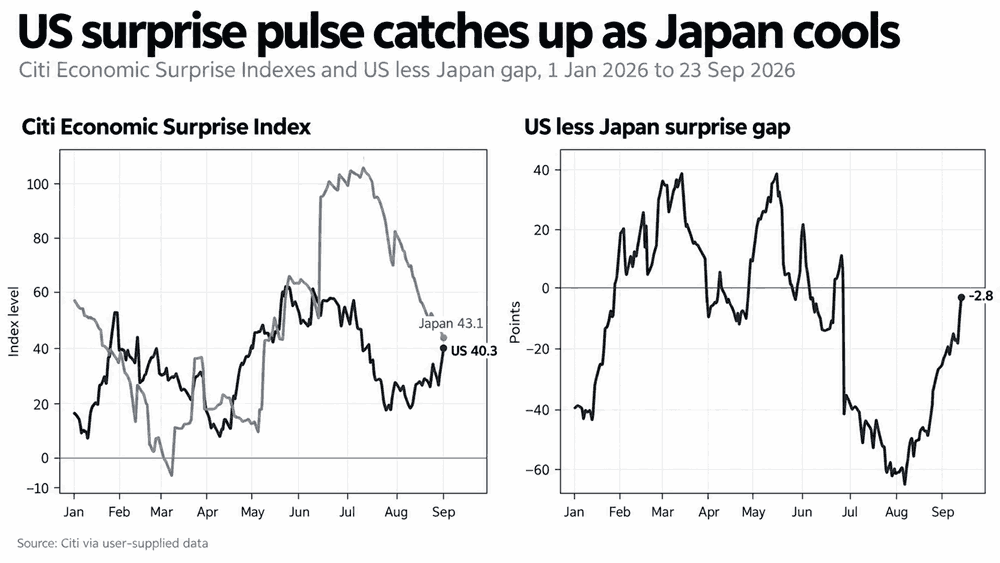
The improved nominal growth outlook is also showing up in measures that track data performance relative to market expectations. As seen in the next graphic, Citi’s US Economic Surprise Index has rebounded sharply recently, and while Japan’s equivalent index remains positive, it has come off the boil, leaving the gap between the two narrowing sharply.
Source: LSEG
Even though Japan still has a slight edge on the United States in terms of the aggregate surprises, beats and misses relative to expectations are one thing, aggregate performance is another. And it is clear the US economy is not only holding up well, but arguably accelerating away from the rest of the pack when it comes to developed economies.
That underscores that while the Fed is hiking to bring down inflationary pressures, it’s doing so for largely good reasons because the economy is strong, rather than pre-emptively like we’re seeing in other economies such as Europe, where policymakers are attempting to eliminate the threat of second-round effects.
Japan’s data pulse loses momentum
Strengthening the view of US economic exceptionalism, the latest flash PMI data for Japan revealed growth slowing to multi-month lows in September, while inflationary pressures remained intense, providing more than a whiff of stagflation in the air.
Meanwhile, speculation Japanese fiscal policymakers may reduce issuance of certain medium-term debt will do little to ease concerns that authorities remain reluctant to let market forces fully play out.
The Ministry of Finance is reportedly considering cutting liquidity-enhancement issuance in the 5-to-11-year sector, which would reduce bond supply and could help limit the rise in yields.
It probably won’t have much impact on the yen while the US side remains so dominant. But if authorities keep trying to suppress the rise in Japanese yields, the adjustment has to show up somewhere, and the currency remains the obvious release valve to do it.
158 remains the key near-term pivot
Turning back to the four-hourly chart at the top, USD/JPY finds itself in a strong uptrend after bottoming beneath 153 earlier this month, with the latest thrust higher taking the pair above 158, an important technical level that has acted as both support and resistance at times this year.
However, following a pronounced unwind of the bullish move in crude seen overnight during early Asian trade, the price has now moved back beneath it, making 158 the immediate focal point for anyone trading the pair.
On the downside, the levels to watch include the uptrend in place since the middle of the month, currently found around 157.60, with 156.68 the next level of note after that. Not only does it mark the August 7 swing low, but also the 50% retracement of the September 2 to September 8 high-low move.
Overhead, the pair struggled to break above 158.40 in overnight trade, with the 200-day simple moving average located just above at 158.45 currently. That’s the immediate reference point overhead, with a push above that and extension of the current bullish trend bringing a retest of 159 or even 159.50 into play.
The message from the oscillators continues to favour buying dips and bullish breaks, although we have seen RSI (14) move back from overbought territory, indicating that the upside momentum that had been building has dissipated slightly. It doesn’t dissuade the view that a bullish bias is favoured, but it does mean bulls should be selective when assessing risk-reward from setups.
Of course, given recent form and the current trajectory for the pair, the risk of intervention remains elevated. We saw a suspected rate check late Friday that resulted in a significant unwind, and it would not surprise to see something similar on this occasion should we see another abbreviated scoot higher in the near term.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.