



Week Ahead Coronavirus Contagion in Focus
The main focus is going to unfortunately be on the cononavirus.
Share this:
What a wild week! After terrible GDP data out of Japan on Monday, yen pairs were all the rage on Tuesday and Wednesday as pairs such as EUR/JPY traded up over 2% and USD/JPY traded up over 1.6%. After speculation the move was a post poor GDP move or because of coronavirus fears in Japan, it seems as though Japan’s Government Pension Investment Fund (GPIF) was the main seller of Yen, reallocated funds to buy foreign bonds. Thursday and Friday were a wake-up call for equity markets as more cases of the coronavirus had been discovered outside of China, particularly in Iran, Lebanon, and South Korea. This led to concerns of further manufacturing disruption. Oddly enough, earlier in the week, lowered guidance from AAPL and WMT couldn’t even spook the market! The S&P 500 is down nearly 1.5% on the week. One more thing….GOLD. Gold was leading the risk off move all week, trading higher all 4 days this week (Monday was a US holiday), and is up almost 4% this week!!!
Next Week
With a light economic calendar most of this week, the main focus is going to unfortunately be on the cononavirus. After cases were reported in Iran and Lebanon, the World Health Organization’s (WHO) Tedros Adhanom Ghebreyesus said the virus can still be contained however “the window of opportunity is narrowing, so we need to act quickly before it closes.” The virus will be closely monitored this weekend and throughout next week. If it continues to spread, stocks could continue to weaken, especially if more cases are identified in the Europe and the US. Other large companies that rely on manufacturing from China are also likely to warn on Q1 earnings. Ironically, as stocks sold off toward the end of the week, yen pairs were only down slightly (and still closed up a large amount for the week). This indicates that there are still sellers of yen in the market. (Yen pairs are highly correlated with risk. As stocks sold off, yen pairs should have sold off as well). Watch for more yen selling next week. As we discussed Thursday, if USD/JPY closes about 112.40, it could run to 115.60!
The US caucuses and primaries take a back seat next week; however, the Nevada caucuses are this Saturday, February 22nd. Next weekend is the South Carolina primary on Saturday February 29th. Candidates will be gearing up this week for the Super Tuesday on March 3rd, when 15 primaries will be held! In addition, Super Tuesday will also be the first of the primaries which will have Michael Bloomberg’s name on the ballot.
Earnings season is just about over, however take note of BIDU and JD this week as these 2 Chinese companies may provide lower guidance and discuss their outlook on the coronavirus.
Expected economic highlights include:
Monday
- New Zealand: Retail Sales Q4
- Germany: IFO Business Climate Feb
Tuesday
- Germany: GDP Q4 Final
- US: Consumer Confidence Feb
Wednesday
- Crude Oil Inventories
Thursday
- New Zealand: Trade Balance Jan
- New Zealand: ANZ Business Confidence Jan
- EU: Business Confidence
- EU: Consumer Confidence
- US: GDP 2nd estimate Q4
- US Durable Goods Orders Jan
Friday
- Japan: Unemployment Rate Jan
- Japan: Industrial Production Jan
- Japan: Retail Sales Jan
- Germany: Unemployment Change Feb
- Germany: Inflation Rate
- Canada: GDP Q4
- Canada: PPI Jan
- US PCE Price Index Jan
- Core PCE Price Index Jan
Saturday, February 29th
- China: NBS Manufacturing PMI Feb
- China: Non-Manufacturing PMI Feb
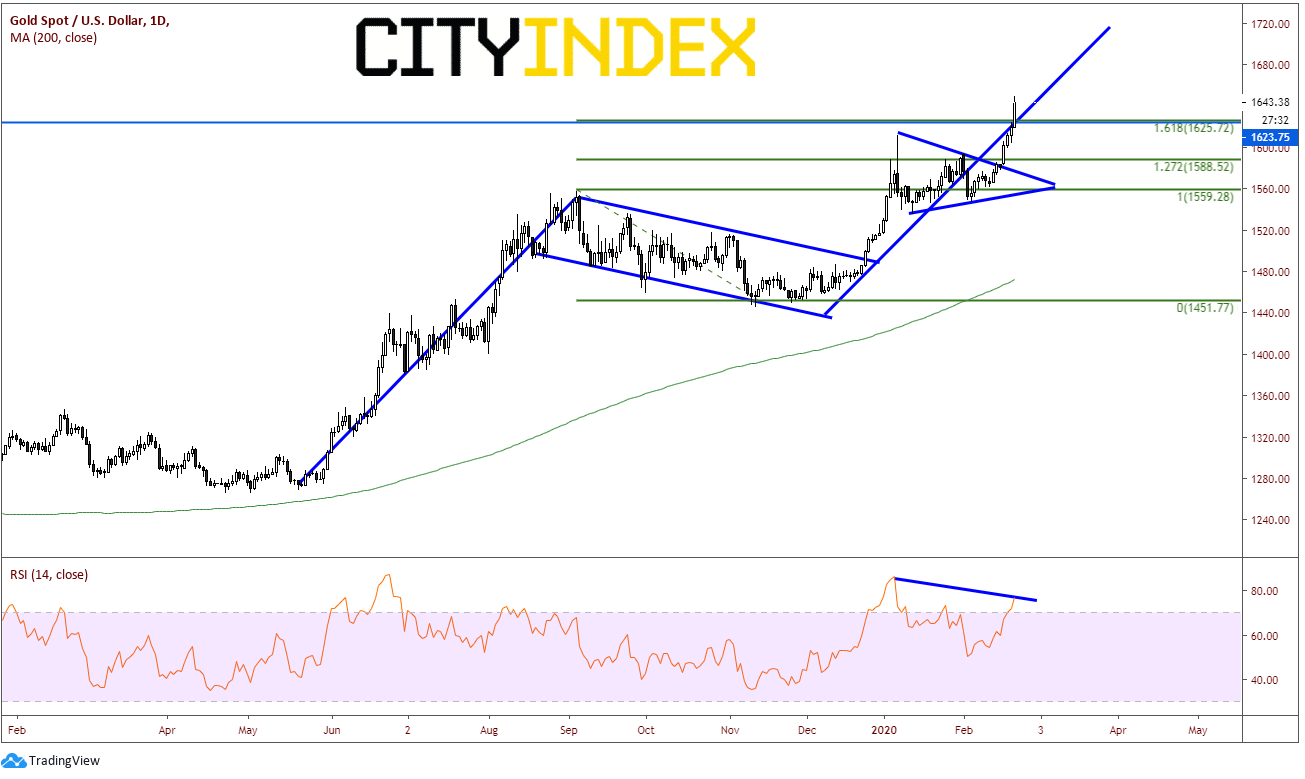
Chart to Watch: Daily Gold
Source: Tradingview, City Index
What a massive 4% move on the week for the precious metal! But can it continue? Technically, price is trading beautifully, as it broke out of a flag pattern in December and paused at the 127.2% Fibonacci extension level from the September 3rd high to the November 12th low near 1588. Price then formed a symmetrical triangle at that level, only to bust higher this week and continue on its path toward the larger flag target near 1720. Price may pause as the RSI is overbought and diverging, however if stocks continue to sell off next week, funds may continue to flow into gold and push price higher.
What a wild week! After terrible GDP data out of Japan on Monday, yen pairs were all the rage on Tuesday and Wednesday as pairs such as EUR/JPY traded up over 2% and USD/JPY traded up over 1.6%. After speculation the move was a post poor GDP move or because of coronavirus fears in Japan, it seems as though Japan’s Government Pension Investment Fund (GPIF) was the main seller of Yen, reallocated funds to buy foreign bonds. Thursday and Friday were a wake-up call for equity markets as more cases of the coronavirus had been discovered outside of China, particularly in Iran, Lebanon, and South Korea. This led to concerns of further manufacturing disruption. Oddly enough, earlier in the week, lowered guidance from AAPL and WMT couldn’t even spook the market! The S&P 500 is down nearly 1.5% on the week. One more thing….GOLD. Gold was leading the risk off move all week, trading higher all 4 days this week (Monday was a US holiday), and is up almost 4% this week!!!
Next Week
With a light economic calendar most of this week, the main focus is going to unfortunately be on the cononavirus. After cases were reported in Iran and Lebanon, the World Health Organization’s (WHO) Tedros Adhanom Ghebreyesus said the virus can still be contained however “the window of opportunity is narrowing, so we need to act quickly before it closes.” The virus will be closely monitored this weekend and throughout next week. If it continues to spread, stocks could continue to weaken, especially if more cases are identified in the Europe and the US. Other large companies that rely on manufacturing from China are also likely to warn on Q1 earnings. Ironically, as stocks sold off toward the end of the week, yen pairs were only down slightly (and still closed up a large amount for the week). This indicates that there are still sellers of yen in the market. (Yen pairs are highly correlated with risk. As stocks sold off, yen pairs should have sold off as well). Watch for more yen selling next week. As we discussed Thursday, if USD/JPY closes about 112.40, it could run to 115.60!
The US caucuses and primaries take a back seat next week; however, the Nevada caucuses are this Saturday, February 22nd. Next weekend is the South Carolina primary on Saturday February 29th. Candidates will be gearing up this week for the Super Tuesday on March 3rd, when 15 primaries will be held! In addition, Super Tuesday will also be the first of the primaries which will have Michael Bloomberg’s name on the ballot.
Earnings season is just about over, however take note of BIDU and JD this week as these 2 Chinese companies may provide lower guidance and discuss their outlook on the coronavirus.
Expected economic highlights include:
Monday
- New Zealand: Retail Sales Q4
- Germany: IFO Business Climate Feb
Tuesday
- Germany: GDP Q4 Final
- US: Consumer Confidence Feb
Wednesday
- Crude Oil Inventories
Thursday
- New Zealand: Trade Balance Jan
- New Zealand: ANZ Business Confidence Jan
- EU: Business Confidence
- EU: Consumer Confidence
- US: GDP 2nd estimate Q4
- US Durable Goods Orders Jan
Friday
- Japan: Unemployment Rate Jan
- Japan: Industrial Production Jan
- Japan: Retail Sales Jan
- Germany: Unemployment Change Feb
- Germany: Inflation Rate
- Canada: GDP Q4
- Canada: PPI Jan
- US PCE Price Index Jan
- Core PCE Price Index Jan
Saturday, February 29th
- China: NBS Manufacturing PMI Feb
- China: Non-Manufacturing PMI Feb
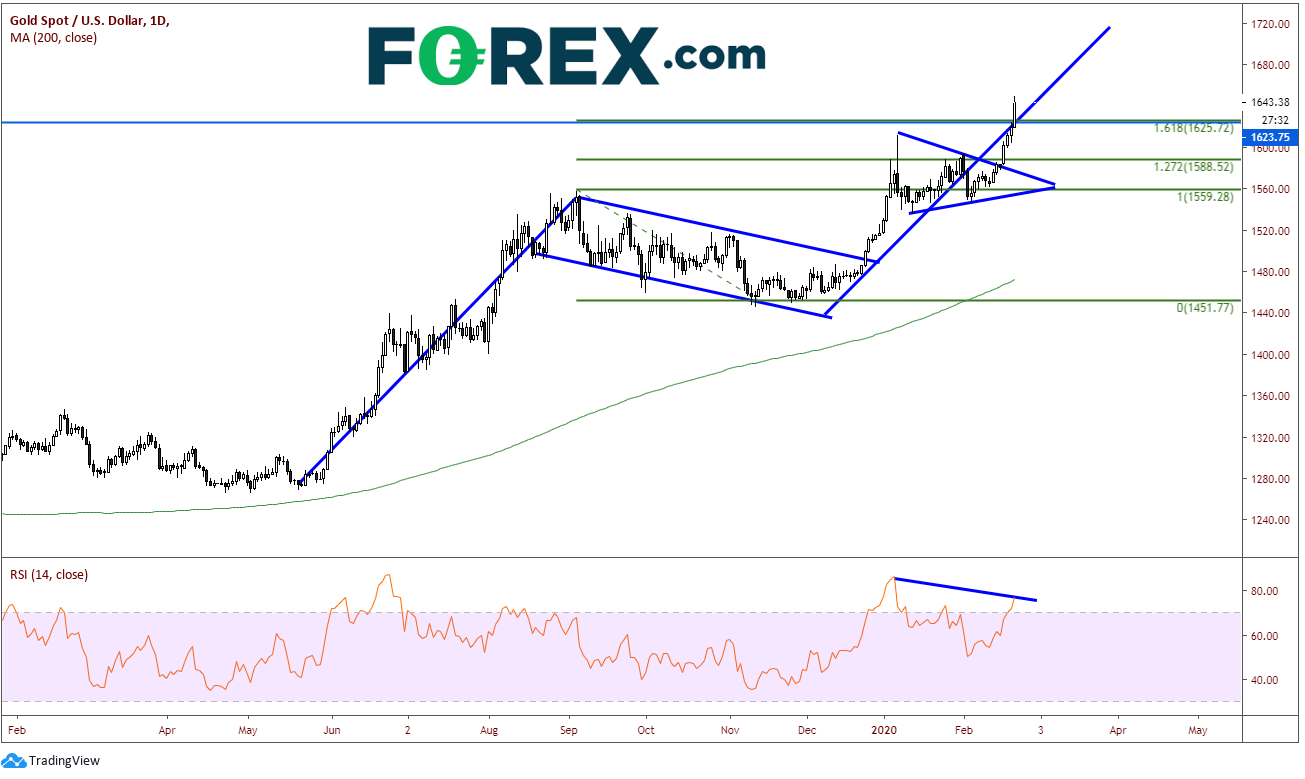
Chart to Watch: Daily Gold
Source: Tradingview, FOREX.com
What a massive 4% move on the week for the precious metal! But can it continue? Technically, price is trading beautifully, as it broke out of a flag pattern in December and paused at the 127.2% Fibonacci extension level from the September 3rd high to the November 12th low near 1588. Price then formed a symmetrical triangle at that level, only to bust higher this week and continue on its path toward the larger flag target near 1720. Price may pause as the RSI is overbought and diverging, however if stocks continue to sell off next week, funds may continue to flow into gold and push price higher.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

Gold forecast: XAU/USD could take a larger dive after the big rise in yields
Gold prices have been falling in the last few days after last week’s post-FOMC pop faded amid rising interest rate expectations, higher oil prices and a strengthening US dollar. As before, I wasn’t convinced gold would thrive in the current macro backdrop.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.