




Whats moving the markets on Monday
The FTSE, along with its European peer are heading for a higher start boosted by vaccine optimism and ahead of a key day in Parliament for the Internal Markets Bill.
Share this:
The FTSE, along with its European peer are heading for a higher start boosted by vaccine optimism and ahead of a key day in Parliament for the Internal Markets Bill.
Vaccine trials restart
Over the weekend, Oxford University announced that the joint AstraZeneca covid vaccine trial will restart this week after a routine pause n the previous week. News that the trial is back on track is music to the ears of the market. A vaccine is the surest and quickest, and possibly the only way for the economy to recover to pre-pandemic growth levels. The vaccine news comes as the “Rule of 6” comes into force in the UK, banning meetings of groups of over 6. AstraZeneca shares are on the rise in early trade.
Adding to the upbeat vaccine news Pfizer In Chief executive officer Albert Bourla said its likely that a covid vaccine will be deployed in the US by the end of the year. A more optimistic view than health authorities.
Over the weekend, Oxford University announced that the joint AstraZeneca covid vaccine trial will restart this week after a routine pause n the previous week. News that the trial is back on track is music to the ears of the market. A vaccine is the surest and quickest, and possibly the only way for the economy to recover to pre-pandemic growth levels. The vaccine news comes as the “Rule of 6” comes into force in the UK, banning meetings of groups of over 6. AstraZeneca shares are on the rise in early trade.
Adding to the upbeat vaccine news Pfizer In Chief executive officer Albert Bourla said its likely that a covid vaccine will be deployed in the US by the end of the year. A more optimistic view than health authorities.
Internal Markets Bill debate
Markets and the Pound are braced for another big Brexit week. The controversial internal markets bill will start to be discussed today in the House of Commons. It is not certain whether the bill will make it through the Commons or even the Lords given that it breaks international law. However, if it does clear Parliaments the Justice Secretary Robert Buckland has already said he will resign. The Pound was the worst performer across the previous week, shedding 3.7% versus the USD in its worst weekly performance since early March. GBP is one of the of performing majors this morning ahead of the debate.
Markets and the Pound are braced for another big Brexit week. The controversial internal markets bill will start to be discussed today in the House of Commons. It is not certain whether the bill will make it through the Commons or even the Lords given that it breaks international law. However, if it does clear Parliaments the Justice Secretary Robert Buckland has already said he will resign. The Pound was the worst performer across the previous week, shedding 3.7% versus the USD in its worst weekly performance since early March. GBP is one of the of performing majors this morning ahead of the debate.
Whilst the 8th round of Brexit talks ended with unsurprisingly little progress, informal Brexit talks are set to continue across the week, ahead of the 9th round beginning on 25th September.
TikTok to partner Oracle, Nvidia buys ARM
Rumours are swirling that TiKTok is choosing to partner up with Oracle rather than Microsoft. Microsoft hasn’t been asked to revise its initial offer amid opposition to the deal from the Chinese government. Has Microsoft managed to dodge a bullet? Could be so according to Bloomberg reports that the deal no longer includes key underlying technologies and the prospect of Chinese government approval is unclear at best.
Nvidia has agreed to buy ARM Holding, SoftBank’s chip division for $40 billion 4 years after the Japanese bank bought it for $32 billion.
Eurozone industrial production
Looking ahead, Eurozone industrial production data will provide some clues as to the health of the sector. Expectations are for growth 10% mom in July, up from 9.1% in June as the sector outperforms services in its recovery.
Looking ahead, Eurozone industrial production data will provide some clues as to the health of the sector. Expectations are for growth 10% mom in July, up from 9.1% in June as the sector outperforms services in its recovery.
FTSE Chart
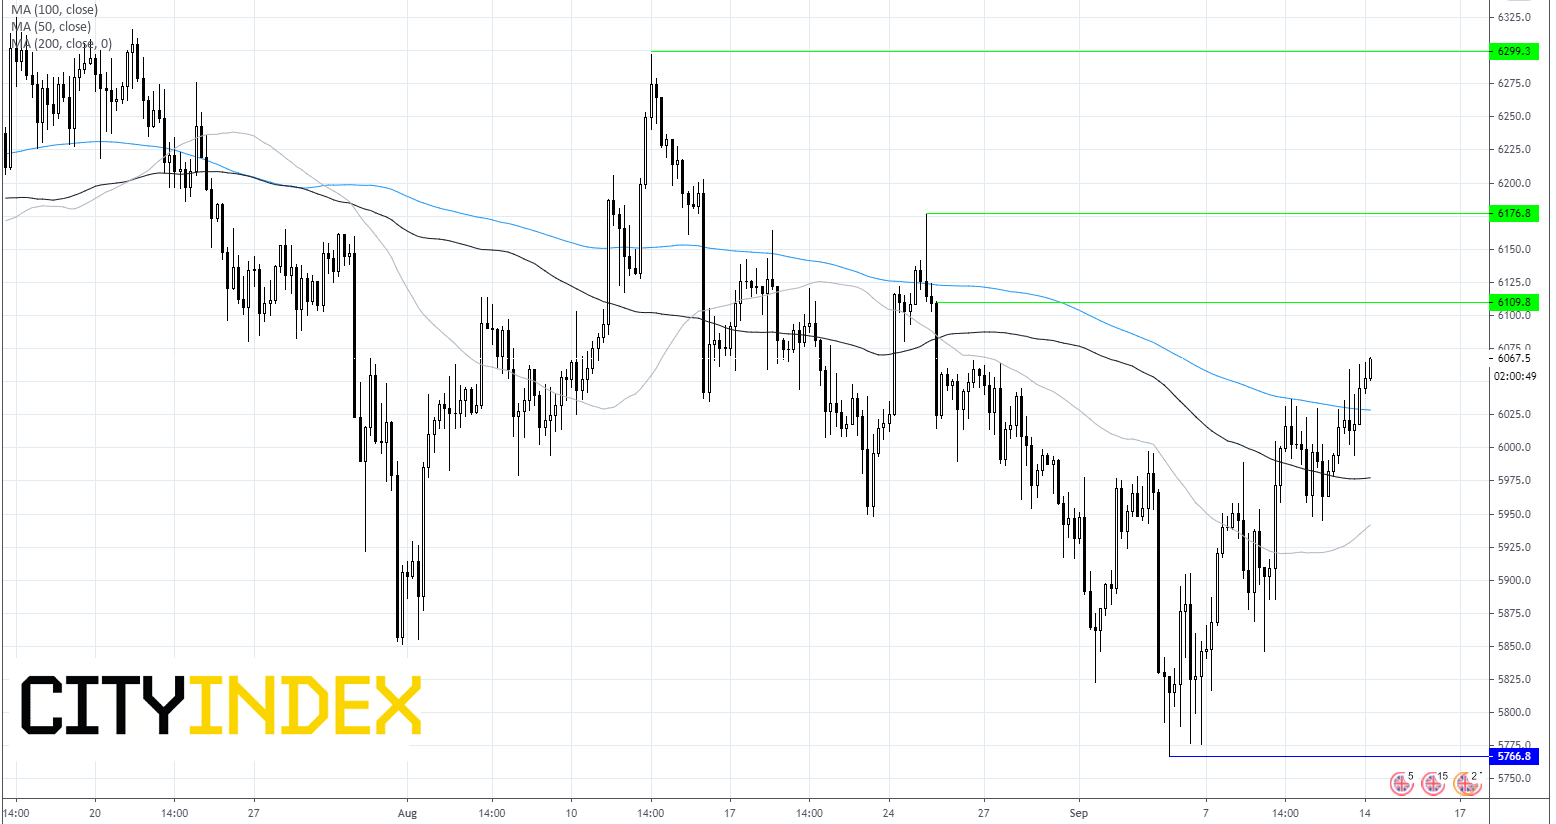
The FTSE is continuing its rebound from Sept 3rd lows, pishing above 50,100 and 200 sma on 4 hr chart. Immediate resistance can be seen at 6110 prior to 6180 (high 25th Aug).
Support can be seen at 6030 200 sma, prior to 5980 (100sma).
The FTSE, along with its European peer are heading for a higher start boosted by vaccine optimism and ahead of a key day in Parliament for the Internal Markets Bill.
Vaccine trials restart
Over the weekend, Oxford University announced that the joint AstraZeneca covid vaccine trial will restart this week after a routine pause n the previous week. News that the trial is back on track is music to the ears of the market. A vaccine is the surest and quickest, and possibly the only way for the economy to recover to pre-pandemic growth levels. The vaccine news comes as the “Rule of 6” comes into force in the UK, banning meetings of groups of over 6. AstraZeneca shares are on the rise in early trade.
Adding to the upbeat vaccine news Pfizer In Chief executive officer Albert Bourla said its likely that a covid vaccine will be deployed in the US by the end of the year. A more optimistic view than health authorities.
Over the weekend, Oxford University announced that the joint AstraZeneca covid vaccine trial will restart this week after a routine pause n the previous week. News that the trial is back on track is music to the ears of the market. A vaccine is the surest and quickest, and possibly the only way for the economy to recover to pre-pandemic growth levels. The vaccine news comes as the “Rule of 6” comes into force in the UK, banning meetings of groups of over 6. AstraZeneca shares are on the rise in early trade.
Adding to the upbeat vaccine news Pfizer In Chief executive officer Albert Bourla said its likely that a covid vaccine will be deployed in the US by the end of the year. A more optimistic view than health authorities.
Internal Markets Bill debate
Markets and the Pound are braced for another big Brexit week. The controversial internal markets bill will start to be discussed today in the House of Commons. It is not certain whether the bill will make it through the Commons or even the Lords given that it breaks international law. However, if it does clear Parliaments the Justice Secretary Robert Buckland has already said he will resign. The Pound was the worst performer across the previous week, shedding 3.7% versus the USD in its worst weekly performance since early March. GBP is one of the of performing majors this morning ahead of the debate.
Markets and the Pound are braced for another big Brexit week. The controversial internal markets bill will start to be discussed today in the House of Commons. It is not certain whether the bill will make it through the Commons or even the Lords given that it breaks international law. However, if it does clear Parliaments the Justice Secretary Robert Buckland has already said he will resign. The Pound was the worst performer across the previous week, shedding 3.7% versus the USD in its worst weekly performance since early March. GBP is one of the of performing majors this morning ahead of the debate.
Whilst the 8th round of Brexit talks ended with unsurprisingly little progress, informal Brexit talks are set to continue across the week, ahead of the 9th round beginning on 25th September.
TikTok to partner Oracle, Nvidia buys ARM
Rumours are swirling that TiKTok is choosing to partner up with Oracle rather than Microsoft. Microsoft hasn’t been asked to revise its initial offer amid opposition to the deal from the Chinese government. Has Microsoft managed to dodge a bullet? Could be so according to Bloomberg reports that the deal no longer includes key underlying technologies and the prospect of Chinese government approval is unclear at best.
Nvidia has agreed to buy ARM Holding, SoftBank’s chip division for $40 billion 4 years after the Japanese bank bought it for $32 billion.
Eurozone industrial production
Looking ahead, Eurozone industrial production data will provide some clues as to the health of the sector. Expectations are for growth 10% mom in July, up from 9.1% in June as the sector outperforms services in its recovery.
Looking ahead, Eurozone industrial production data will provide some clues as to the health of the sector. Expectations are for growth 10% mom in July, up from 9.1% in June as the sector outperforms services in its recovery.
FTSE Chart
The FTSE is continuing its rebound from Sept 3rd lows, pishing above 50,100 and 200 sma on 4 hr chart. Immediate resistance can be seen at 6110 prior to 6180 (high 25th Aug).
Support can be seen at 6030 200 sma, prior to 5980 (100sma).
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD, FTSE 100 Forecast: Two trades to watch 1507
EUR/USD rises after weaker US CPI, PPI up next. FTSE 100 falls as weak China GDP data hits miners.

FTSE 100, USD/JPY Forecast: Two trades to watch
FTSE eases modestly despite inflation unexpectedly holding steady. USD/JPY drifts lower ahead of the FOMC rate decision.
EUR/USD, FTSE 100 Forecast: Two trades to watch 21-05-26
EUR/USD slips below 1.16 as weak eurozone data weighs on sentiment. FTSE 100 slips as oil prices rebound and caution returns.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.