



Asia Morning July 23
Meanwhile, investors seemed to look past escalating tensions between the U.S. and China...
Share this:

On Wednesday, U.S. stocks closed higher. The Dow Jones Industrial Average climbed 165 points (+0.62%) to 27005, the S&P 500 rose 18 points (+0.57%) to 3276, and the Nasdaq 100 was up 37 points (+0.35%) to 10870.
S&P 500 Index: Daily Chart
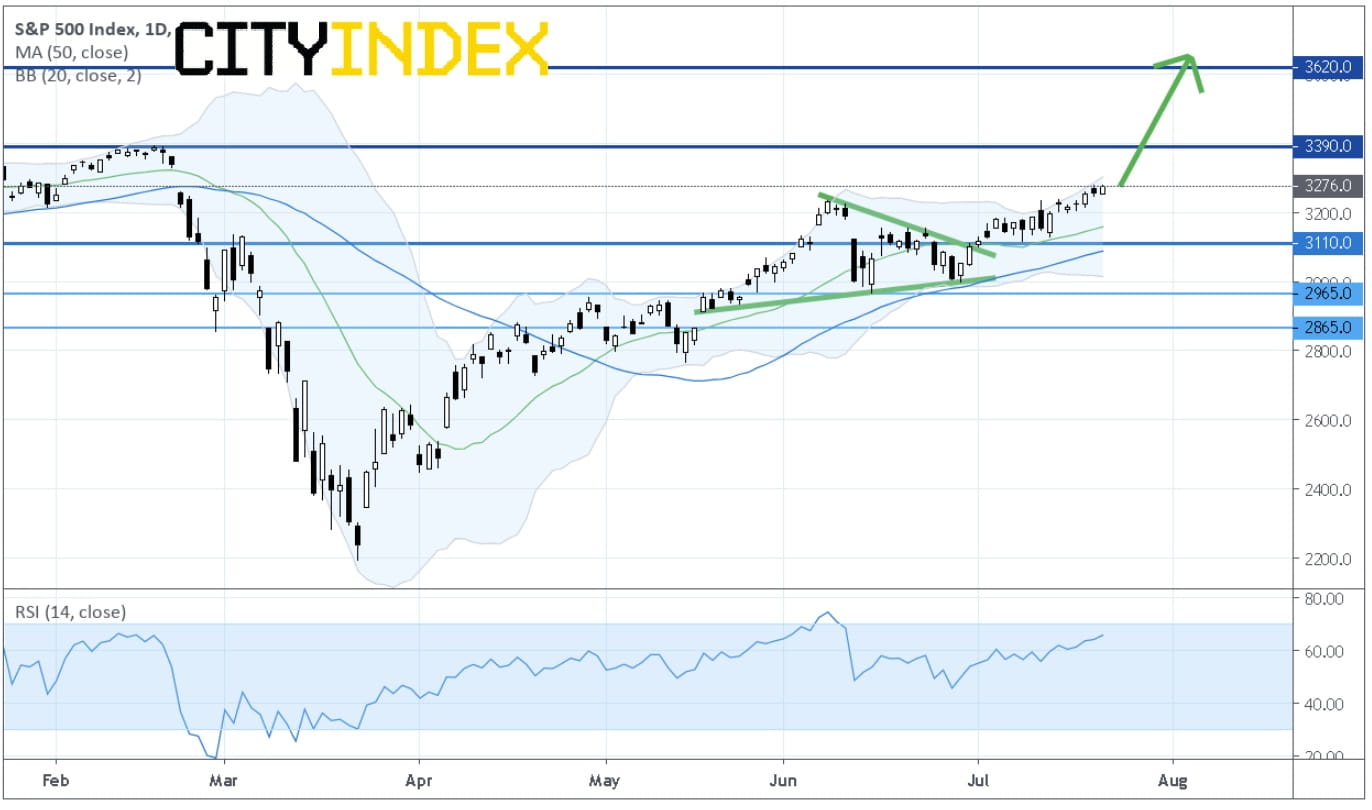
Source: GAIN Capital, TradingView
Investors were encouraged to see that the U.S. government signed a deal worth $1.95 billion with Pfizer (PFE +5.10%) and BioNTech (BNTX +13.72%) for 100 million doses of their experimental COVID-19 vaccine.
Meanwhile, investors seemed to look past escalating tensions between the U.S. and China. The U.S. government demanded that China shut down its consulate in Houston, Texas, within 72 hours amid accusations of spying. Retaliatory measures from Beijing are widely expected.
Consumer Durables & Apparel (+1.76%), Consumer Services (+1.64%) and Utilities (+1.53%) sectors were the best performers. HCA Healthcare (HCA +11.97%), Advanced Micro Devices (AMD +8.40%) and Best Buy (BBY +7.84%) were the top gainers.
On the technical side, about 53.4% (51.8% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 87.5% (77.0% in the prior session) were trading above their 20-day moving average.
In after-marker hours, Tesla (TSLA +1.53%) posted a fourth consecutive quarterly profit saying it earned $0.50 per share in the second quarter, against expectations of a loss of $1.06 per share. Microsoft (MSFT +1.44%) reported a fourth-quarter earnings per share of $1.46 ($1.36 expected).
European stocks closed in negative territory. The Stoxx Europe 600 Index fell 0.87%. Germany's DAX 30 dropped 0.51%, France's CAC 40 lost 1.32%, and the U.K.'s FTSE 100 was down 1.00%.
The benchmark U.S. 10-year Treasury yield slid further to 0.595% from 0.606% Tuesday.
Spot gold price surged a further $29.00 (+1.6%) to $1,871 an ounce, and spot silver soared 8.0% to $23.00 an ounce.
U.S. WTI crude oil futures (August) were little changed at $41.90 a barrel. The U.S. Energy Information Administration reported that crude-oil stockpiles increased 4.90 million barrels last week, contrary to a reduction of 1.95 million barrels expected.
On the forex front, the ICE U.S. Dollar Index slipped 0.2% on day to 94.95, down for a fourth straight session.
EUR/USD advanced 0.4% to 1.1569, the highest level since October 2018. Later today, the eurozone's Consumer Confidence Index for July will be released (-12.0 expected).
GBP/USD was broadly flat at 1.2734, after a three-day rally.
USD/JPY rebounded 0.4% to 107.19.
Meanwhile, AUD/USD gained 0.2% to 0.7142, posting a four-day winning streak.
S&P 500 Index: Daily Chart
Source: GAIN Capital, TradingView
Investors were encouraged to see that the U.S. government signed a deal worth $1.95 billion with Pfizer (PFE +5.10%) and BioNTech (BNTX +13.72%) for 100 million doses of their experimental COVID-19 vaccine.
Meanwhile, investors seemed to look past escalating tensions between the U.S. and China. The U.S. government demanded that China shut down its consulate in Houston, Texas, within 72 hours amid accusations of spying. Retaliatory measures from Beijing are widely expected.
Consumer Durables & Apparel (+1.76%), Consumer Services (+1.64%) and Utilities (+1.53%) sectors were the best performers. HCA Healthcare (HCA +11.97%), Advanced Micro Devices (AMD +8.40%) and Best Buy (BBY +7.84%) were the top gainers.
On the technical side, about 53.4% (51.8% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 87.5% (77.0% in the prior session) were trading above their 20-day moving average.
In after-marker hours, Tesla (TSLA +1.53%) posted a fourth consecutive quarterly profit saying it earned $0.50 per share in the second quarter, against expectations of a loss of $1.06 per share. Microsoft (MSFT +1.44%) reported a fourth-quarter earnings per share of $1.46 ($1.36 expected).
European stocks closed in negative territory. The Stoxx Europe 600 Index fell 0.87%. Germany's DAX 30 dropped 0.51%, France's CAC 40 lost 1.32%, and the U.K.'s FTSE 100 was down 1.00%.
The benchmark U.S. 10-year Treasury yield slid further to 0.595% from 0.606% Tuesday.
Spot gold price surged a further $29.00 (+1.6%) to $1,871 an ounce, and spot silver soared 8.0% to $23.00 an ounce.
U.S. WTI crude oil futures (August) were little changed at $41.90 a barrel. The U.S. Energy Information Administration reported that crude-oil stockpiles increased 4.90 million barrels last week, contrary to a reduction of 1.95 million barrels expected.
On the forex front, the ICE U.S. Dollar Index slipped 0.2% on day to 94.95, down for a fourth straight session.
EUR/USD advanced 0.4% to 1.1569, the highest level since October 2018. Later today, the eurozone's Consumer Confidence Index for July will be released (-12.0 expected).
GBP/USD was broadly flat at 1.2734, after a three-day rally.
USD/JPY rebounded 0.4% to 107.19.
Meanwhile, AUD/USD gained 0.2% to 0.7142, posting a four-day winning streak.
On Wednesday, U.S. stocks closed higher. The Dow Jones Industrial Average climbed 165 points (+0.62%) to 27005, the S&P 500 rose 18 points (+0.57%) to 3276, and the Nasdaq 100 was up 37 points (+0.35%) to 10870.
S&P 500 Index: Daily Chart

Source: GAIN Capital, TradingView
Investors were encouraged to see that the U.S. government signed a deal worth $1.95 billion with Pfizer (PFE +5.10%) and BioNTech (BNTX +13.72%) for 100 million doses of their experimental COVID-19 vaccine.
Meanwhile, investors seemed to look past escalating tensions between the U.S. and China. The U.S. government demanded that China shut down its consulate in Houston, Texas, within 72 hours amid accusations of spying. Retaliatory measures from Beijing are widely expected.
Consumer Durables & Apparel (+1.76%), Consumer Services (+1.64%) and Utilities (+1.53%) sectors were the best performers. HCA Healthcare (HCA +11.97%), Advanced Micro Devices (AMD +8.40%) and Best Buy (BBY +7.84%) were the top gainers.
On the technical side, about 53.4% (51.8% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 87.5% (77.0% in the prior session) were trading above their 20-day moving average.
In after-marker hours, Tesla (TSLA +1.53%) posted a fourth consecutive quarterly profit saying it earned $0.50 per share in the second quarter, against expectations of a loss of $1.06 per share. Microsoft (MSFT +1.44%) reported a fourth-quarter earnings per share of $1.46 ($1.36 expected).
European stocks closed in negative territory. The Stoxx Europe 600 Index fell 0.87%. Germany's DAX 30 dropped 0.51%, France's CAC 40 lost 1.32%, and the U.K.'s FTSE 100 was down 1.00%.
The benchmark U.S. 10-year Treasury yield slid further to 0.595% from 0.606% Tuesday.
Spot gold price surged a further $29.00 (+1.6%) to $1,871 an ounce, and spot silver soared 8.0% to $23.00 an ounce.
U.S. WTI crude oil futures (August) were little changed at $41.90 a barrel. The U.S. Energy Information Administration reported that crude-oil stockpiles increased 4.90 million barrels last week, contrary to a reduction of 1.95 million barrels expected.
On the forex front, the ICE U.S. Dollar Index slipped 0.2% on day to 94.95, down for a fourth straight session.
EUR/USD advanced 0.4% to 1.1569, the highest level since October 2018. Later today, the eurozone's Consumer Confidence Index for July will be released (-12.0 expected).
GBP/USD was broadly flat at 1.2734, after a three-day rally.
USD/JPY rebounded 0.4% to 107.19.
Meanwhile, AUD/USD gained 0.2% to 0.7142, posting a four-day winning streak.
S&P 500 Index: Daily Chart
Source: GAIN Capital, TradingView
Investors were encouraged to see that the U.S. government signed a deal worth $1.95 billion with Pfizer (PFE +5.10%) and BioNTech (BNTX +13.72%) for 100 million doses of their experimental COVID-19 vaccine.
Meanwhile, investors seemed to look past escalating tensions between the U.S. and China. The U.S. government demanded that China shut down its consulate in Houston, Texas, within 72 hours amid accusations of spying. Retaliatory measures from Beijing are widely expected.
Consumer Durables & Apparel (+1.76%), Consumer Services (+1.64%) and Utilities (+1.53%) sectors were the best performers. HCA Healthcare (HCA +11.97%), Advanced Micro Devices (AMD +8.40%) and Best Buy (BBY +7.84%) were the top gainers.
On the technical side, about 53.4% (51.8% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 87.5% (77.0% in the prior session) were trading above their 20-day moving average.
In after-marker hours, Tesla (TSLA +1.53%) posted a fourth consecutive quarterly profit saying it earned $0.50 per share in the second quarter, against expectations of a loss of $1.06 per share. Microsoft (MSFT +1.44%) reported a fourth-quarter earnings per share of $1.46 ($1.36 expected).
European stocks closed in negative territory. The Stoxx Europe 600 Index fell 0.87%. Germany's DAX 30 dropped 0.51%, France's CAC 40 lost 1.32%, and the U.K.'s FTSE 100 was down 1.00%.
The benchmark U.S. 10-year Treasury yield slid further to 0.595% from 0.606% Tuesday.
Spot gold price surged a further $29.00 (+1.6%) to $1,871 an ounce, and spot silver soared 8.0% to $23.00 an ounce.
U.S. WTI crude oil futures (August) were little changed at $41.90 a barrel. The U.S. Energy Information Administration reported that crude-oil stockpiles increased 4.90 million barrels last week, contrary to a reduction of 1.95 million barrels expected.
On the forex front, the ICE U.S. Dollar Index slipped 0.2% on day to 94.95, down for a fourth straight session.
EUR/USD advanced 0.4% to 1.1569, the highest level since October 2018. Later today, the eurozone's Consumer Confidence Index for July will be released (-12.0 expected).
GBP/USD was broadly flat at 1.2734, after a three-day rally.
USD/JPY rebounded 0.4% to 107.19.
Meanwhile, AUD/USD gained 0.2% to 0.7142, posting a four-day winning streak.
Related tags:
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Dollar Bulls Return as Euro and Pound Shorts Build | COT Report
US dollar net-longs surged at their fastest pace in seven years as futures traders added bearish exposure to the euro and British pound.

Australian Dollar Outlook: AUD/USD Holds 70c Ahead of RBA and CPI
AUD/USD faces an expected RBA hike and Australian CPI before attention turns to US PCE, ISM and nonfarm payrolls later in the week.

EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.