



AUD/NZD, AUD/USD, ASX 200 Analysis: NZ enters a technical recession
The Fed delivered the hawkish pause with rates remaining at 5.00-5.25%, but warned of another 50bp hikes by December.
Share this:

Market summary
- The Fed delivered the hawkish pause with rates remaining at 5.00-5.25%, but warned of another 50bp hikes by December
- 2023 Forecasts: Fed Fund futures increased to 5.6% (5.1% prior), GDP up to 1% (0.4% prior), unemployment lowered to 4.1% (4.5% prior), PCE inflation lowered to 3.2% (3.5% prior) Core PCE lowered to 3.9% (3.6% prior)
- Fed fund futures currently imply a 64.5% chance of another 25bp hike in July, or a 60.5% chance of one in June
- The 2-year yield rose to a 3-month high of 4.8% before pulling back to close at a 3-month high
- US indices initially fell and the Dow Jones hit a 3-day low, but by the close the Nasdaq had closed above 15k and the S&P 500 had erased earlier losses to close with a Spinning Top candle
- With other central banks facing further pressures to hike, the US dollar was in fact the weakest FX major whilst NZD, AUD and CHF were the strongest
- EUR/USD reached a 3-week high before pulling back to close beneath its 50-week EMA, AUD/USD rose to a 16-week high but closed back below 68c (a key resistance level since the RBA paused in April), USD/JPY handed back most of Wednesday’s gains before closing back above 140 and remaining within its recent consolidation range
- There was no major breakout on gold or oil either, with gold holding above last week’s low and WTI falling back beneath $70 after an intraday break above it
- The DAX closed at a record high, the close was just beneath its intraday high of 16,331.94 after a brief spell above it
- Australian consumer confidence fell -3.1 points to 72.7 after the last RBA hike, with the ANZ-Roy Morgan report citing deteriorating buying conditions
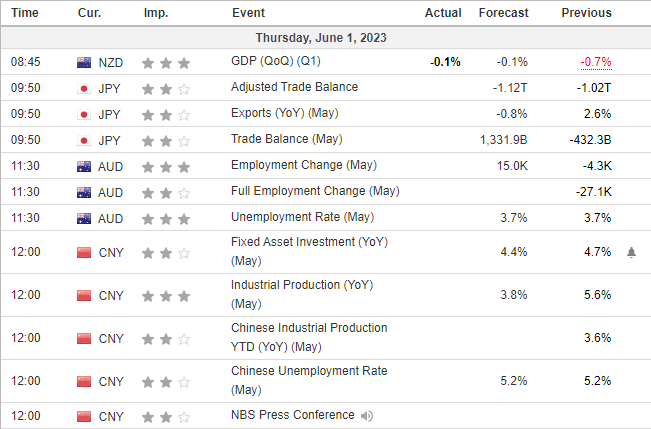
- NZ GDP contracted for a second consecutive quarter to earn the economy a ‘technical recession’ tag
- The IMF warned that the RBNZ may need to hike rates again and keep them elevated for some time


Events in focus (AEDT):
- 08:45 – New Zealand GDP
- 09:50 Japan’s trade balance
- 11:30 – Australia’s employment report
- 12:00 – China’s industrial production, investment, unemployment, NBS press conference
AUD/NZD daily chart:

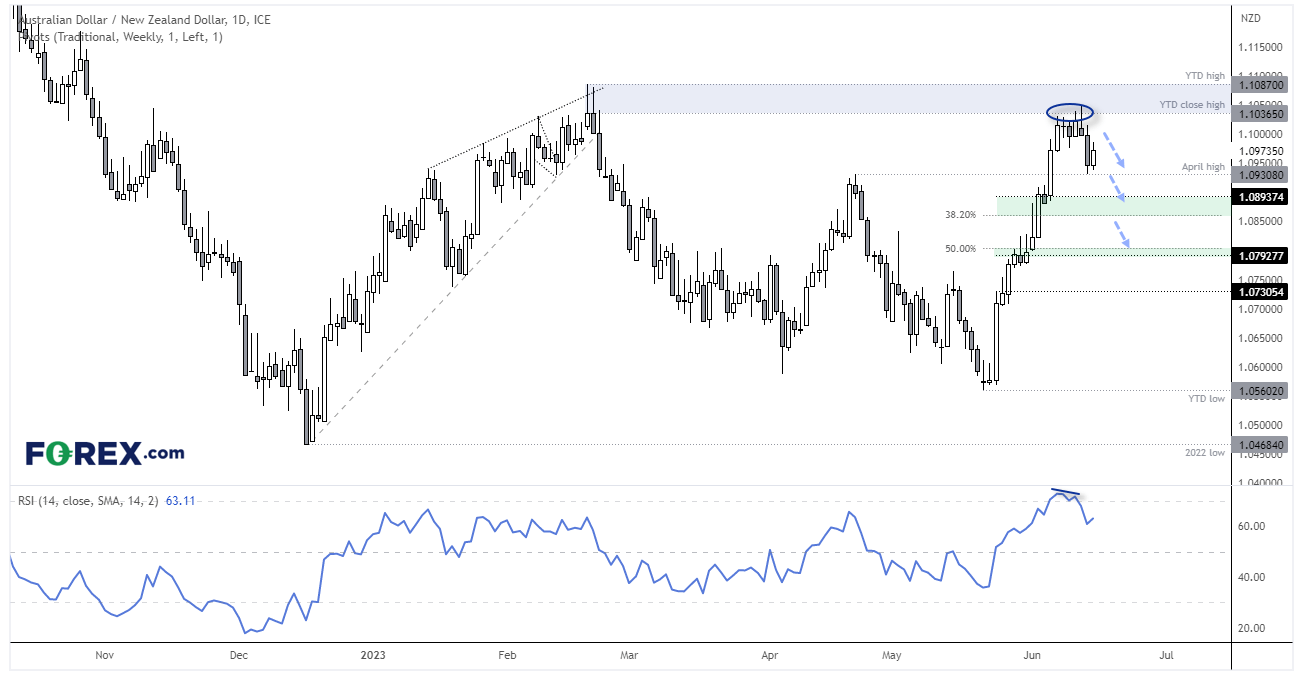
AUD/NZD failed to close above the YTD close high (despite several attempts) or even retest the actual YTD high before momentum turned lower on the daily chart. Prices fell towards the April low ahead of today’s GDP report, where the negative quarterly print weakened the NZD and helped recoup much of yesterday’s losses. Whether it can bounce further is likely down to how strong today’s Australian employment print is, but with the RBNZ holding the higher interest rate (and the IMF hinting that further hikes may be needed) then it may struggle to break back above this week’s high.
From here, we’re looking for evidence of an intraday lower high (beneath this week’s high) to assume the next leg lower, which could be confirmed with a break of the April high. A break of which brings the support zones around 1.0850 and 1.0800 into focus for bears. A weak Australian employment report could help it move bac towards the daily lows in a few hours.
AUD/USD 1-hour chart

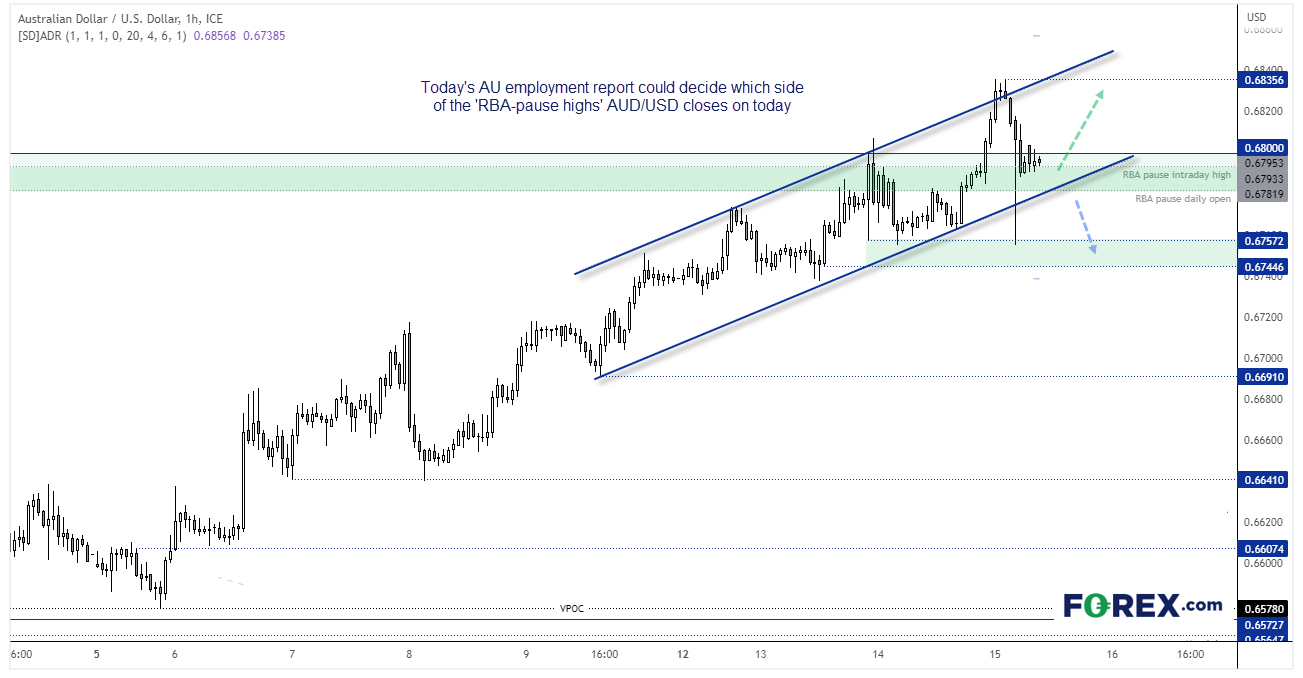
We noted the importance of the 0.68 handle earlier this week, as AUD/USD has tried (but failed) several times to break and hold above it. But the market has also struggled around the April 4th highs just below 0.68 as it marks the day the RBA first held rates steady, yet AUD/USD has struggled to break above this key level despite two further RBA hikes. Whilst the Fed’s hawkish pause keeps the pressure on the RBA to hike further and helped the Aussie break above these key levels, it is likely down to today’s employment repot as to which side of the 0.6720 – 0.6733 zone (or 0.6800 handle) it closes on. As another strong employment report likely tips the RBA’s hand to hike, given the Fed’s latest hawkish message. The 0.6835 comes into focus for bulls but the 20-day average daily range sits around 0.6850, whilst a break beneath trend support brings the low around 0.6750 into focus.
ASX 200 at a glance:
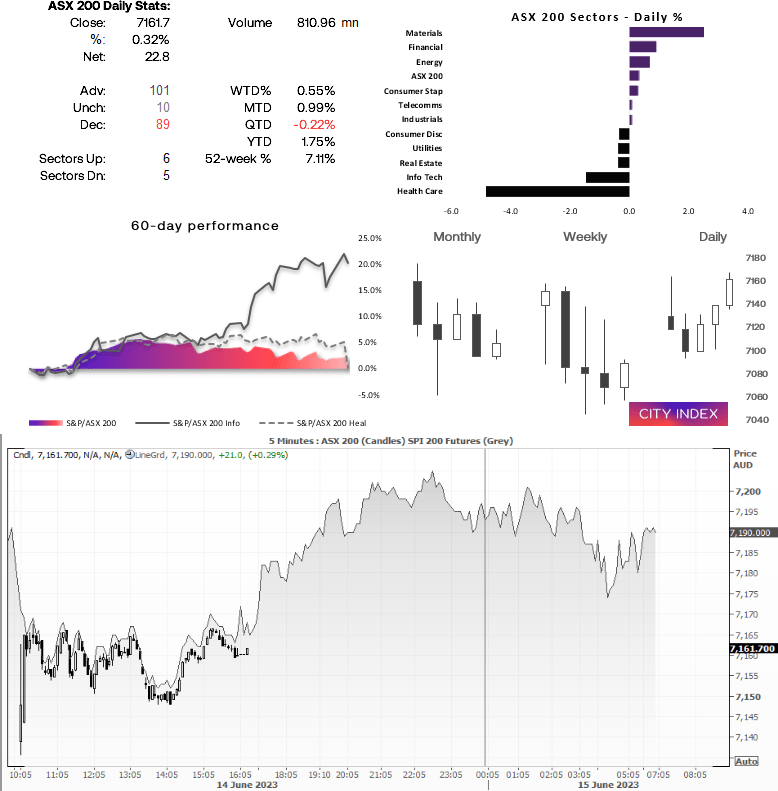
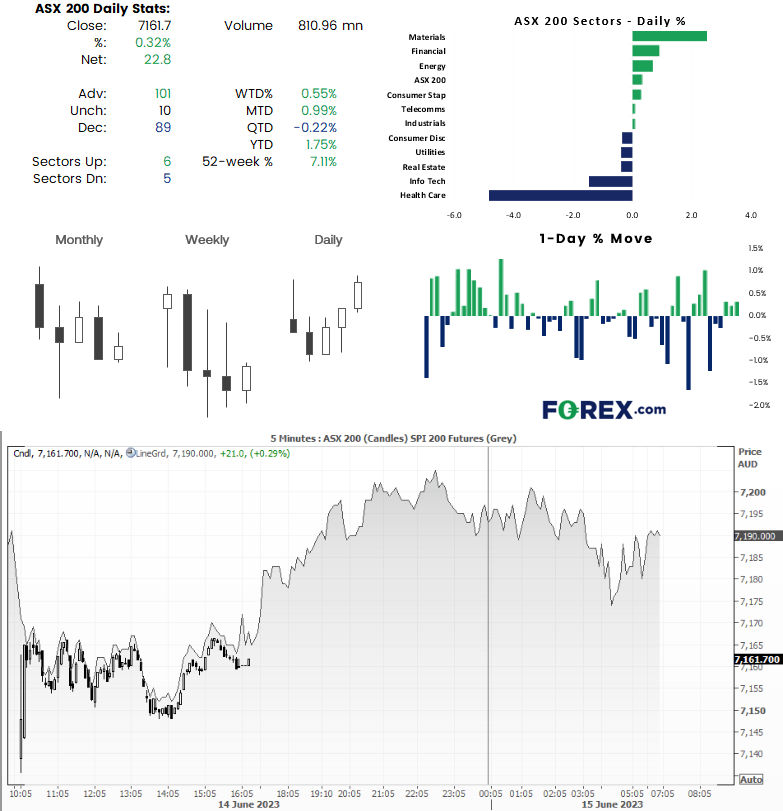
- Third day higher for the ASX 200
- SPI futures rose 0.29% overnight
- Intraday support: 7148, 7131.2, 7100-7102
- Intraday resistance: 7160-7165, 7185, 7200
Asia Data Calendar (AEDT):
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:

Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Dollar Bulls Return as Euro and Pound Shorts Build | COT Report
US dollar net-longs surged at their fastest pace in seven years as futures traders added bearish exposure to the euro and British pound.

Gold Outlook: XAU/USD hit hard as US yields, dollar resume ascent
A stronger dollar, surging front-end yields and renewed geopolitical tension have combined to push gold back towards key technical support.


Australian Dollar Outlook: AUD/USD Holds 70c Ahead of RBA and CPI
AUD/USD faces an expected RBA hike and Australian CPI before attention turns to US PCE, ISM and nonfarm payrolls later in the week.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.