



Asian Open: Commodities weigh on commodity FX, ASX set to mean revert?
Commodities were broadly lower overnight ahead of highly anticipated peace talks between Ukraine and Russia, dragging NZD and AUD lower along the way.
Share this:

Monday US cash market close:
- The Dow Jones Industrial rose 233.09 points (0.27%) to close at 34,955.89
- The S&P 500 index rose 32.46 points (2.51%) to close at 34,058.75
- The Nasdaq 100 index rose 233.094 points (1.58%) to close at 14,987.40
Asian futures:
- Australia's ASX 200 futures are down 0 points (-0.07%), the cash market is currently estimated to open at 7,412.40
- Japan's Nikkei 225 futures are up 310 points (1.12%), the cash market is currently estimated to open at 28,253.89
- Hong Kong's Hang Seng futures are up 48 points (0.22%), the cash market is currently estimated to open at 21,732.97
- China's A50 Index futures are up 59 points (0.44%), the cash market is currently estimated to open at 13,479.67
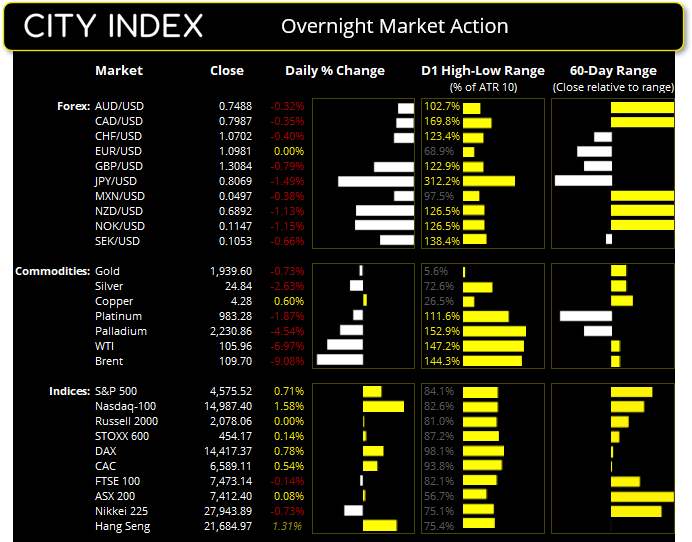
Wall Street continued to climb despite higher interest rates. Yet dwindling volume with higher prices suggests the rally could be related to short covering as opposed to the initiation of fresh bullish bets. The S&P 500 is not less than a day’s trade from out 4600 target. Tech stocks led the advance and the Nasdaq 100 rose 1.6% to close just shy of 15,000.
ASX 200:


The ASX 200 is grinding higher but a bit of mean reversion almost seems inevitable. Yesterday’s bearish pinbar closed within the upper keltner band following a failed break above it earlier in the session. And half of Friday’s bullish session was the upper wick, which ultimately shows a change in mind at the high of the day. Whether that merits a countertrend trade is up for debate, but we would urge caution at these levels for bulls. And there would be nothing wrong with stepping aside and waiting to see if mean reversion kicks in, then seeking fresh longs around support zones such as 7340/58.
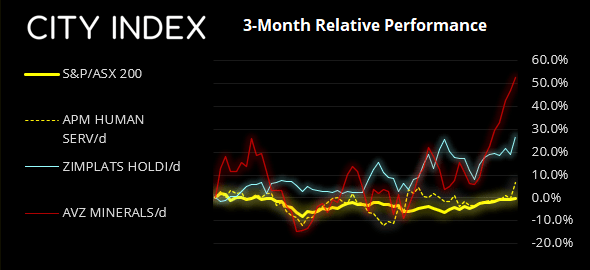
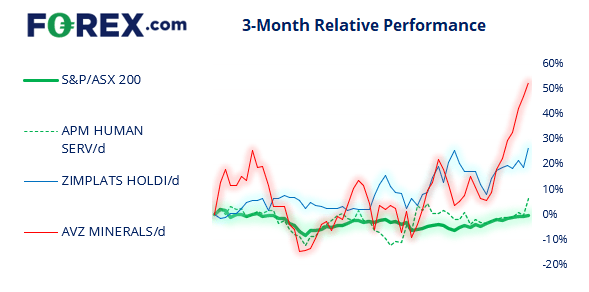
ASX 200: 7412.4 (0.08%), 28 March 2022
- Materials (1.29%) was the strongest sector and Info Tech (-2.67%) was the weakest
- 4 out of the 11 sectors closed higher
- 7 out of the 11 sectors closed lower
- 4 out of the 11 sectors outperformed the index
- 79 (39.50%) stocks advanced, 110 (55.00%) stocks declined
Outperformers:
- +7.04% - APM Human Services International Ltd (APM.AX)
- +6.58% - Zimplats Holdings Ltd (ZIM.AX)
- +3.95% - AVZ Minerals Ltd (AVZ.AX)
Underperformers:
- -6.02% - Paladin Energy Ltd (PDN.AX)
- -5.35% - Lake Resources NL (LKE.AX)
- -5.16% - Xero Ltd (XRO.AX)
Gold-demand dented ahead of peace talks
Currently down around -2%, its has been gold’s worst day in two weeks. Safe-haven demand has taken a knock ahead of peace talks which will be the first in two weeks. And it is worth noting that gold hit a low two weeks ago when it became apparent that peace talks did not live up to expectations. Given that Putin seems unwilling to compromise to end the war, we may find gold hits bid again if peace talks fail to live up to their name. Prices are holding above the June 2021 high of 1916 and it remains a key level to watch today. A daily close below 1900 would be constructive for a bear case.
WTI falls to a 5-day low
Oil prices fell over -8% yesterday during its worst day in 13. And that day would take some beating, given prices plunged up to -22% in a single session. And such levels of volatility may help explain why net-long exposure on WTI futures has fallen for a third week as it wreaks havoc on portfolios which just seek nice and steady returns.
BOE and BOJ send their currencies lower
The yen continued to fall in spectacular fashion after the BOJ announced they’ll buy an “unlimited” amount of bonds to maintain their yield curve control. This only further widened yield differentials and allowed USD/JPY to rise above 123 to a fresh 6-year high. It seems only a matter of time before we hear thinly veiled threats of FX intervention fore the yen.
The British pound was lower against the euro and US dollar as BOE governor reiterated their less-hawkish stance presented at their last meeting. GBP/USD fell to an 8-day low and suggests a corrective high was seen on Wednesday. EUR/GBP also broke above Friday’s bearish hammer which has invalidated our bearish bias outlined in Friday’s and yesterday’s report.
Weak commodity markets weighed on commodity FX but, in particular, the New Zealand dollar. NZD/USD fell over -1.1% during its worst session in a month. AUD/NZD had its most bullish day in two-moths and broke above key resistance to touch a 1-year high. We expect dips above 1.0812 to be bought, in line with its dominant trend.
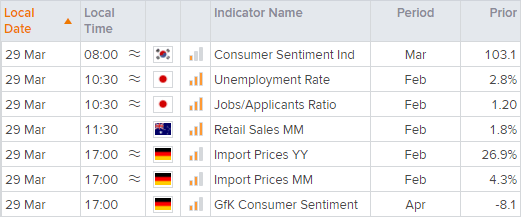
Up Next (Times in AEDT)
How to trade with City Index
You can easily trade with City Index by using these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Dollar Bulls Return as Euro and Pound Shorts Build | COT Report
US dollar net-longs surged at their fastest pace in seven years as futures traders added bearish exposure to the euro and British pound.

Gold Outlook: XAU/USD hit hard as US yields, dollar resume ascent
A stronger dollar, surging front-end yields and renewed geopolitical tension have combined to push gold back towards key technical support.


Australian Dollar Outlook: AUD/USD Holds 70c Ahead of RBA and CPI
AUD/USD faces an expected RBA hike and Australian CPI before attention turns to US PCE, ISM and nonfarm payrolls later in the week.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.