




Asian Open Mild Gain on Wall Street GBPCAD Ready to Drop
Wall Street posted minor gains and European bourses hovered near their highs during a mildly positive session ahead of tomorrow’s Nonfarm payroll report.
Share this:

US futures
Dow futures +0.36% at 34328
S&P futures +0.5% at 4178
Nasdaq futures +0.8% at 13521
In Europe
FTSE +0.1% at 7026
Dax +0.35% at 15491
Euro Stoxx +0.2% at 4029
Learn more about trading indices
Tech stocks set to lead gains as inflation fears ebb
US futures are pointing to a stronger start on Monday, after a mixed closed on Friday. Amid a weekend of light news flow and with an empty economic calendar today, the mood in the market is cautiously optimistic.
Concerns have faded surrounding runaway inflation and the Fed tightening policy sooner. The reaction to those FOMC minutes last week which revealed that some policy makers were ready to talk about tapering support was short lived.
China cracks down on commodity prices
A move by China to crackdown on commodity prices, excessive speculation in the commodity market and spreading of fake news appears to be helping to calm inflation fears further. Commodity prices had been surging in recent weeks with copper hitting an all time high as well as strong gains in base metals. The rally in commodity prices had raised questions over how transitory inflation would actually be.
PCE figures on Friday
This is unlikely to be the end of the inflation story that has stalked the markets. With PCE figures, the Fed’s preferred gauge of inflation, due on Friday inflation jitters are bound to return as the week progresses.
The economic calendar is very quiet across the start of the week giving investors little to sink their teeth into. Sentiment is likely to be a principal driving force which could be a positive given the stabilization within cryptocurrencies.
Bitcoin has bounced higher although the mood surrounding the crypto currency remains weak.
Equities
Earning season is winding up with few companies reporting on Monday. Later in the week Costco, Nordstrom and Best Buy are set to report.
AMC Entertainment could be in focus after Cineworld, the world’s second largest cinema chain said it saw a strong reopening weekend thanks to the release of Peter Rabbit 2.
Where next for the S&P 500?
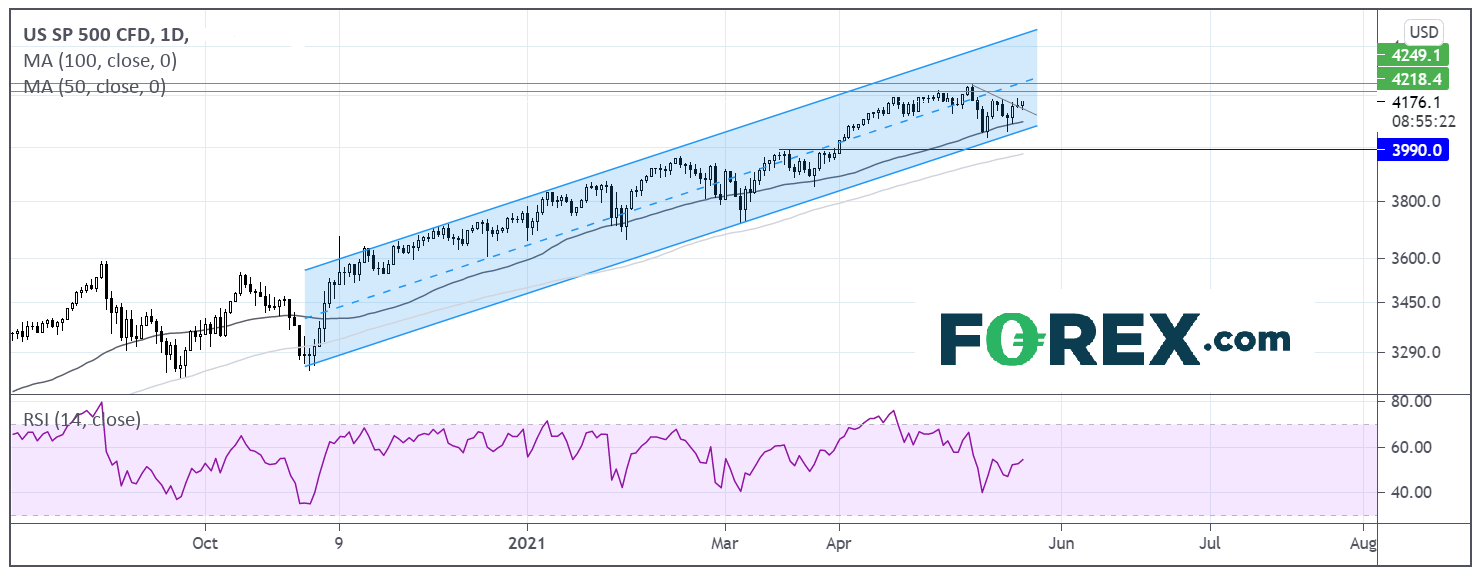
The S&P has traded within an ascending channel since early November. After hitting an all time high in early May of 4250, the price had been trending lower. Friday’s jump higher, saw the S&P 500 push back above the two descending trendline. Whilst the price remains above that trendline and within the ascending channel, the buyers could be optimistic of a move back towards 4215 and 4250.
FX – USD weakens, GBP trades under pressure
The US Dollar is trading lower as concerns fade over inflation and the Fed acting sooner to tighten policy. The USD had spiked higher after the release of the Fed minutes. However, the effect as short lived. The start of the week is quiet as far as data is concerned. Attention will turn to Fed speak Brainard for further clues over the Fed’s next moves.
GBP/USD trades lower whilst UK reopening optimism underpins the Pound, Brexit jitters and concerns over rising covid cases are dragging on demand. Andrew Baily is due to speak shortly.
GBP/USD -0.2% at 1.4126
EUR/USD +0.2% at 1.2206
Oil rebounds as revival of Iran nuclear deal encounters problems
Oil is rebounding on Monday after falling over 2.5% last week. Reports of the Iran US nuclear talks running into trouble have eased concerns that Iran will be supplying the oil market again soon. Whilst talks are set to continue between the two sides, Iran prepares to end UN watchdog’s access to nuclear sites which will throw a dampener on progress. Furthermore, the US Secretary of State Blinken stated that there was no sign that Iran is willing to comply with nuclear commitments, raising doubts over progress.
Elsewhere re-opening optimism in the West continues to support the outlook for demand. However, rising covid cases in Japan and tighter restrictions could keep a lid on gains.
US crude trades +1.3% at $64.45
Brent trades +1.42% at $67.32
Learn more about trading oil here.
The complete guide to trading oil markets
Looking ahead
14:00 Fed Brainard speech
US futures
Dow futures +0.36% at 34328
S&P futures +0.5% at 4178
Nasdaq futures +0.8% at 13521
In Europe
FTSE +0.1% at 7026
Dax +0.35% at 15491
Euro Stoxx +0.2% at 4029
Learn more about trading indices
Tech stocks lead the risers as inflation fears fade
US futures are pointing to a stronger start on Monday, after a mixed closed on Friday. Amid a weekend of light news flow and with an empty economic calendar today, the mood in the market is cautiously optimistic.
Concerns have faded surrounding runaway inflation and the Fed tightening policy sooner. The reaction to those FOMC minutes last week which revealed that some policy makers were ready to talk about tapering support was short lived. The high growth tech sector looks set to outperform.
China cracks down on commodity prices
A move by China to crackdown on commodity prices, excessive speculation in the commodity market and spreading of fake news appears to be helping to calm inflation fears further. Commodity prices had been surging in recent weeks with copper hitting an all time high as well as strong gains in base metals. The rally in commodity prices had raised questions over how transitory inflation would actually be.
PCE figures on Friday
This is unlikely to be the end of the inflation story that has stalked the markets. With PCE figures, the Fed’s preferred gauge of inflation, due on Friday inflation jitters are bound to return as the week progresses.
The economic calendar is very quiet across the start of the week giving investors little to sink their teeth into. Sentiment is likely to be a principal driving force which could be a positive given the stabilization within cryptocurrencies.
Bitcoin has bounced higher although the mood surrounding the crypto currency remains weak.
Equities
Earning season is winding up with few companies reporting on Monday. Later in the week Costco, Nordstrom and Best Buy are set to report.
AMC Entertainment could be in focus after Cineworld, the world’s second largest cinema chain said it saw a strong reopening weekend thanks to the release of Peter Rabbit 2.
Where next for the S&P 500?
The S&P has traded within an ascending channel since early November. After hitting an all time high in early May of 4250, the price had been trending lower. Friday’s jump higher, saw the S&P 500 push back above the two descending trendline. Whilst the price remains above that trendline and within the ascending channel, the buyers could be optimistic of a move back towards 4215 and 4250.
FX – USD weakens, GBP trades under pressure
The US Dollar is trading lower as concerns fade over inflation and the Fed acting sooner to tighten policy. The USD had spiked higher after the release of the Fed minutes. However, the effect as short lived. The start of the week is quiet as far as data is concerned. Attention will turn to Fed speak Brainard for further clues over the Fed’s next moves.
GBP/USD trades lower whilst UK reopening optimism underpins the Pound, Brexit jitters and concerns over rising covid cases are dragging on demand. Andrew Bailey is due to speak shortly.
GBP/USD -0.2% at 1.4126
EUR/USD +0.2% at 1.2206
Oil rebounds as revival of Iran nuclear deal encounters problems
Oil is rebounding on Monday after falling over 2.5% last week. Reports of the Iran US nuclear talks running into trouble have eased concerns that Iran will be supplying the oil market again soon. Whilst talks are set to continue between the two sides, Iran prepares to end UN watchdog’s access to nuclear sites which will throw a dampener on progress. Furthermore, the US Secretary of State Blinken stated that there was no sign that Iran is willing to comply with nuclear commitments, raising doubts over progress.
Elsewhere re-opening optimism in the West continues to support the outlook for demand. However, rising covid cases in Japan and tighter restrictions could keep a lid on gains.
US crude trades +1.3% at $64.45
Brent trades +1.42% at $67.32
Learn more about trading oil here.
The complete guide to trading oil markets
Looking ahead
14:00 Fed Brainard speech
How to trade with City Index
Follow these easy steps to start trading with City Index today:
- Open a City Index account, or log-in if you’re already a customer.
- Search for the market you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 Forecast: SPX Continues to Drift Away from Record Highs
Recent trading sessions have done little to restore confidence in the equity market. Over the last four sessions, the S&P 500 has declined by nearly 1.00%, a move that highlights growing short-term weakness and keeps the index moving further away from its record-high territory.
EUR/USD Forecast: Euro Struggles to Find Support Even After U.S. PCE Data
The euro continues to face a challenging environment in the short term. The currency has struggled to regain ground against a U.S. dollar that remains firmly supported, a dynamic reflected in EUR/USD, which has now recorded three consecutive losing sessions and a decline of roughly 0.6%.
Canadian Dollar Forecast: USD/CAD Four-Week Rally Eyes Yearly Highs 9 30 2026
USD/CAD has advanced in 14 of the past 15 sessions, but stretched momentum raises the stakes as major resistance and NFP come into focus.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.