




Asian Open: USD Correction to Help Oil and AUD hold key support?
The dollar has had a good run but, now momentum has turned lower, a healthy retracement appears to now be underway.
Share this:
- Korean PPI producing the (inflationary) goods
- The Kiwi dollar rises with NZ Inflation forecasts
- Japan’s CPI going for a hat-trick of weak data?
- Retail sales remains a key theme today
- The October 2018 high remains pivotal for oil
- USD enter corrective phase
- ASX 200 bullish inside day to nowhere

Asian Futures:
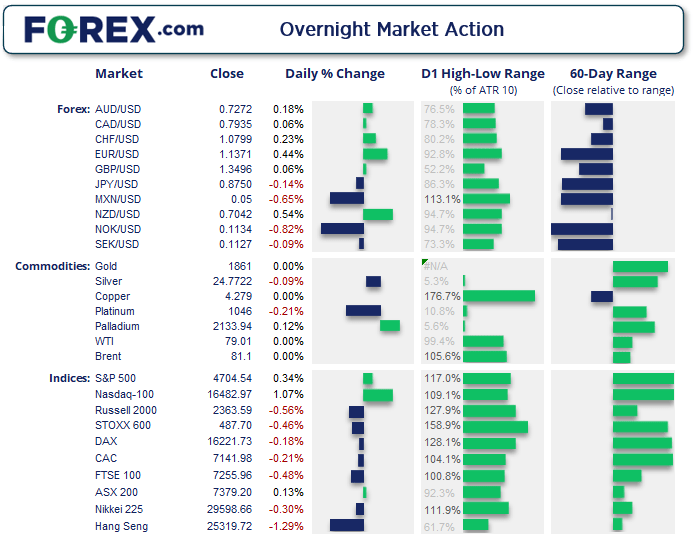
- Australia's ASX 200 futures are up 8 points (0.11%), the cash market is currently estimated to open at 7,387.20
- Japan's Nikkei 225 futures are up 40 points (0.14%), the cash market is currently estimated to open at 29,638.66
- Hong Kong's Hang Seng futures are down -383 points (-1.51%), the cash market is currently estimated to open at 24,936.72
- China's A50 Index futures are down -65 points (-0.42%), the cash market is currently estimated to open at 15,350.42
UK and Europe:
- UK's FTSE 100 index fell -35.24 points (-0.48%) to close at 7,255.96
- Europe's Euro STOXX 50 index fell -17.11 points (-0.39%) to close at 4,383.70
- Germany's DAX index fell -29.4 points (-0.18%) to close at 16,221.73
- France's CAC 40 index fell -14.87 points (-0.21%) to close at 7,141.98
Thursday US Close:
- The Dow Jones Industrial fell -60.1 points (-0.17%) to close at 35,870.95
- The S&P 500 index rose 15.87 points (0.34%) to close at 4,704.54
- The Nasdaq 100 index rose 174.903 points (1.07%) to close at 16,482.97
The Kiwi dollar rises with NZ Inflation forecasts
RBNZ raised their inflation forecasts to 11-year highs yesterday, which places the +1 year CPI expectation to 3.7% y/y (3.02% prior) and the +2 year to 2.96% (2.27% prior). As the one-year remain elevated relative to the two, they’re clearly sticking to the “inflation is transitory” mantra, yet that their targets are rising and realised inflation is already above these they seem to be playing for time as they kick their forecasting can down the road.
AUD/NZD has fallen -1.2% over the past two days and now sits at a 2-month low, and its YTD low at 1.0280 seems an easy target given the market’s hawkish expectations of RBNZ relative to a dovish-as-hell RBA.
AUD/USD has found support at the August trendline, yet whilst commodity prices (specifically steel and Iron ore) continue to plunge then it’s hard to muster up a decent bullish case over the near-term.
Korean PPI producing the goods
If ‘goods’ are higher prices for producers, that is. Rising 8.9% y/y producer prices are at their highest levels since 2008, and the trend is clearly higher. On the month they rose 0.8%, which is its 12th consecutive rise. Whilst the basing effect explains a part of it, inflation is clearly persistent looking at the monthly figures. Add that alongside China’s rising producer prices and the theme is apparent for Asian and the rest of the world who purchase their goods.
Japan’s CPI going for a hat-trick of weak data?
It’s not been a great data week for Japan, with annualised and quarterly growth contracted much more than estimated whilst exports sank to an 8-month low. AT 10:30 AEDT we’ll see if inflation data can make it a hat-trick. Still, for an economy that has been struggling to reflate for decades you’d think they’d welcome the inflationary forces that are present, although that it comes with negative growth means the timing is off. Yet with annualised CPI sat at around 0.2% it is hardly setting the world alight, so the key here is to see that it remains above zero.
Retail sales remains a key theme today
As we enter the European session the UK release retail sales at 18:00. They somehow managed to contract in September despite raging energy costs, and another disappointing print could shake a few GBP bulls out at their highs after a solid week of rate-hike bets. But it would likely need to be a shocker of a print to markedly diminish the odds of no hike in our view. Canada also release retail sales at 0:30 but it may not be such a big event since the BOC are already taming expectations for a hike in H1 next year. Yesterday the Assistant Governor said that a hike in the ‘middle quarters’ doesn’t necessarily mean it will be Q2.
USD enter corrective phase
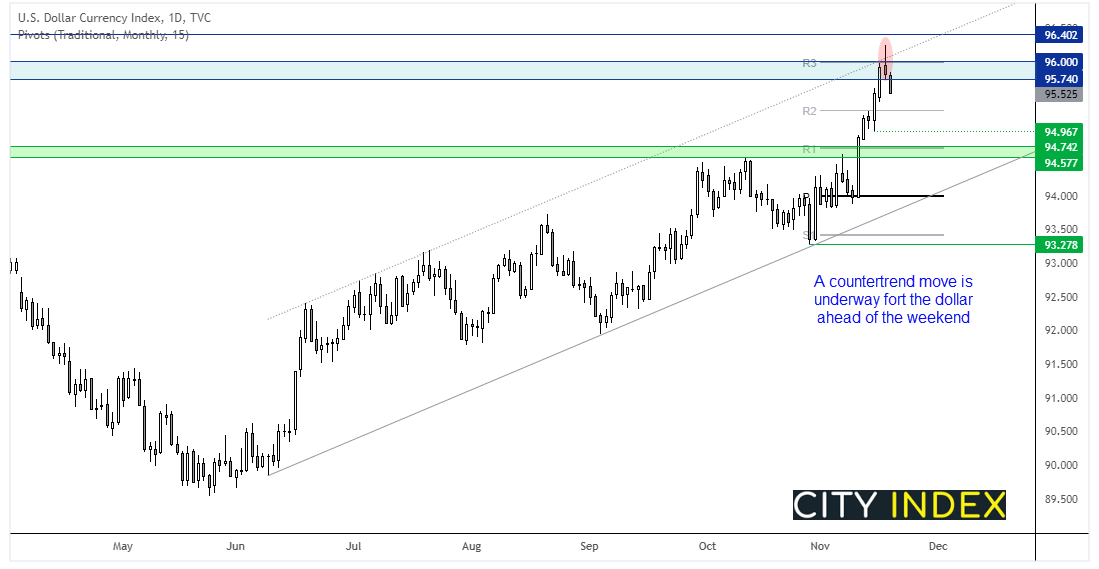

The dollar stalled around 96.0 as we suspected, given the plethora of technical levels in the area. Although it made one final (and failed) attempt to push higher on Wednesday, resulting in a bearish hammer at resistance with yesterday’s decline forming part of a 3-day reversal at said highs. We now anticipated dollar weakness which should help WTI and AUD remain above their support levels seen at yesterday’s lows. It could help WTI move back towards $80 today, but it would likely require a new catalyst to close above it given prices gaped below it at Wednesday’s open.
The October 2018 high remains pivotal for oil
Prices dipped below this key level briefly yesterday but managed to close back above it and finish the session 1% higher, making the importance of this ley level quite apparent in the process. But the weaker dollar could potentially help it rebound from these lows heading into the weekend as traders square up their books for the week. For today we suspect a bounce towards $80 could be on the cards, but take note that most of the volume from yesterday was at 78.58 which makes it a potential resistance level.
ASX 200 bullish inside day to nowhere

The ASX 200 took the dullest route to nowhere yesterday, as it held above the September trend support and below 7400. Therefore 7400 remains an important level for bulls to break and regain our bullish interest, whilst a break of yesterday’s lows brings the 7300 – 7311 support zone (not too far away) into focus.
ASX 200: 7379.2 (0.13%), 18 November 2021
- Real Estate (1.23%) was the strongest sector and Energy (-1.46%) was the weakest
- 7 out of the 11 sectors closed higher
- 112 (56.00%) stocks advanced 76 (38.00%) stocks declined
- 65.5% of stocks closed above their 200-day average
- 56.5% of stocks closed above their 50-day average
- 52% of stocks closed above their 20-day average
Outperformers:
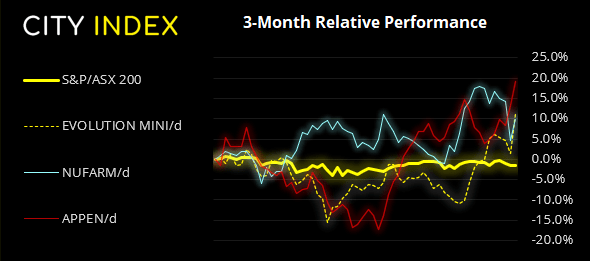
- + 9.73%-Evolution Mining Ltd(EVN.AX)
- + 5.23%-Nufarm Ltd(NUF.AX)
- + 5.19%-Appen Ltd(APX.AX)
Underperformers:
- -4.47%-Whitehaven Coal Ltd(WHC.AX)
- -4.17%-Mesoblast Ltd(MSB.AX)
- -4.05%-ALS Ltd(ALQ.AX)
Up Next (Times in AEDT)
How to trade with City Index
You can easily trade with City Index by using these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:
Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Gold forecast: XAU/USD could take a larger dive after the big rise in yields
Gold prices have been falling in the last few days after last week’s post-FOMC pop faded amid rising interest rate expectations, higher oil prices and a strengthening US dollar. As before, I wasn’t convinced gold would thrive in the current macro backdrop.


WTI Crude Oil Mulls Bounce from $90
Having fallen 17% from its cycle highs in just five days and now holding above $90, perhaps it could be time for crude oil to bounce over the near term.

USD/JPY outlook: Hawkish Fed recalibration pressures the yen
Stronger US growth momentum and rising Treasury yields are keeping USD/JPY pointed higher, even as Japanese policymakers try to limit the pressure building across domestic markets.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.