



Asian Open Vaccine Approval Boosts Sentiment Gold Breaks Higher
News that the FDA had fully approved the Pfizer-BioNTech COVID-19 vaccine helped stocks to extend Friday’s rally, whilst USD weakness saw commodity FX dominate the session.
Share this:

Market Overview
The Nasdaq 100 and S&P 500 ended yesterday's hectic session up, but the Dow Jones and Russell 2000 are still down. The DAX closed down in yesterday's trading session, but opened up with a current gain of 0.35%.
We also had the expected presidential debate, which took place overnight for us here in Europe. Many opinions were expressed by traders on the outcome, but Kamala Harris and Donald Trump remained unchanged at the top of the race.
The most important event this week is today's US inflation report, the CPI, which will show us how much the economy is being slowed down. This is the last inflation report before the FED's interest rate decision next week. In this respect, this report could have the opportunity to influence the extent to which the FED will lower interest rates next week.
I have written more about this in this article: (https://www.forex.com/ie/news-and-analysis/us-cpi-countdown-how-septembers-report-could-shape-economic-policy/)
Monthly price increases are expected to remain moderate and continue to slow year-on-year. UK GDP did not rise by 0.2% in July as expected, but remained at 0.0%.
Corporate news
To avert a possible strike, Boeing has offered unionised employees additional benefits and a 25 per cent wage increase.
With new AI features, Apple introduced its iPhone 16 range; however, after previous losses, shares closed almost unchanged. In addition, Apple was ordered by the EU to refund 13 billion euros in overdue taxes.
Oracle's first-quarter revenue of $13.31 billion exceeded expectations of 8% year-on-year, leading to a 9% rise in shares.
Ahead of its Tuesday launch, Huawei said it had 3 million pre-orders for its new triple-foldable smartphone, posing a threat to Apple in China.
Brian Niccol, the new CEO of Starbucks, started his first day on the job.
The US government is targeting Google over its Google Ads division, which accounted for around 78% of the company's revenue in 2023. Google's Ads division could be split off if the Department of Justice gets its way again, which would have a significant impact on the company's profits.
Among the S&P 500, Palantir and Dell are two newcomers to the index. American Airlines and Etsy have left the S&P 500.
On the agenda for Wednesday 11 September – London Time
13:30 USD core CPI (MoM) (Aug)
13:30 USD core CPI (YoY) (Aug)
13:30 USD CPI (YoY) (Aug)
13:30 USD CPI (MoM) (Aug)
15:30 USD Crude Oil Inventories
DAX- Technical Analysis
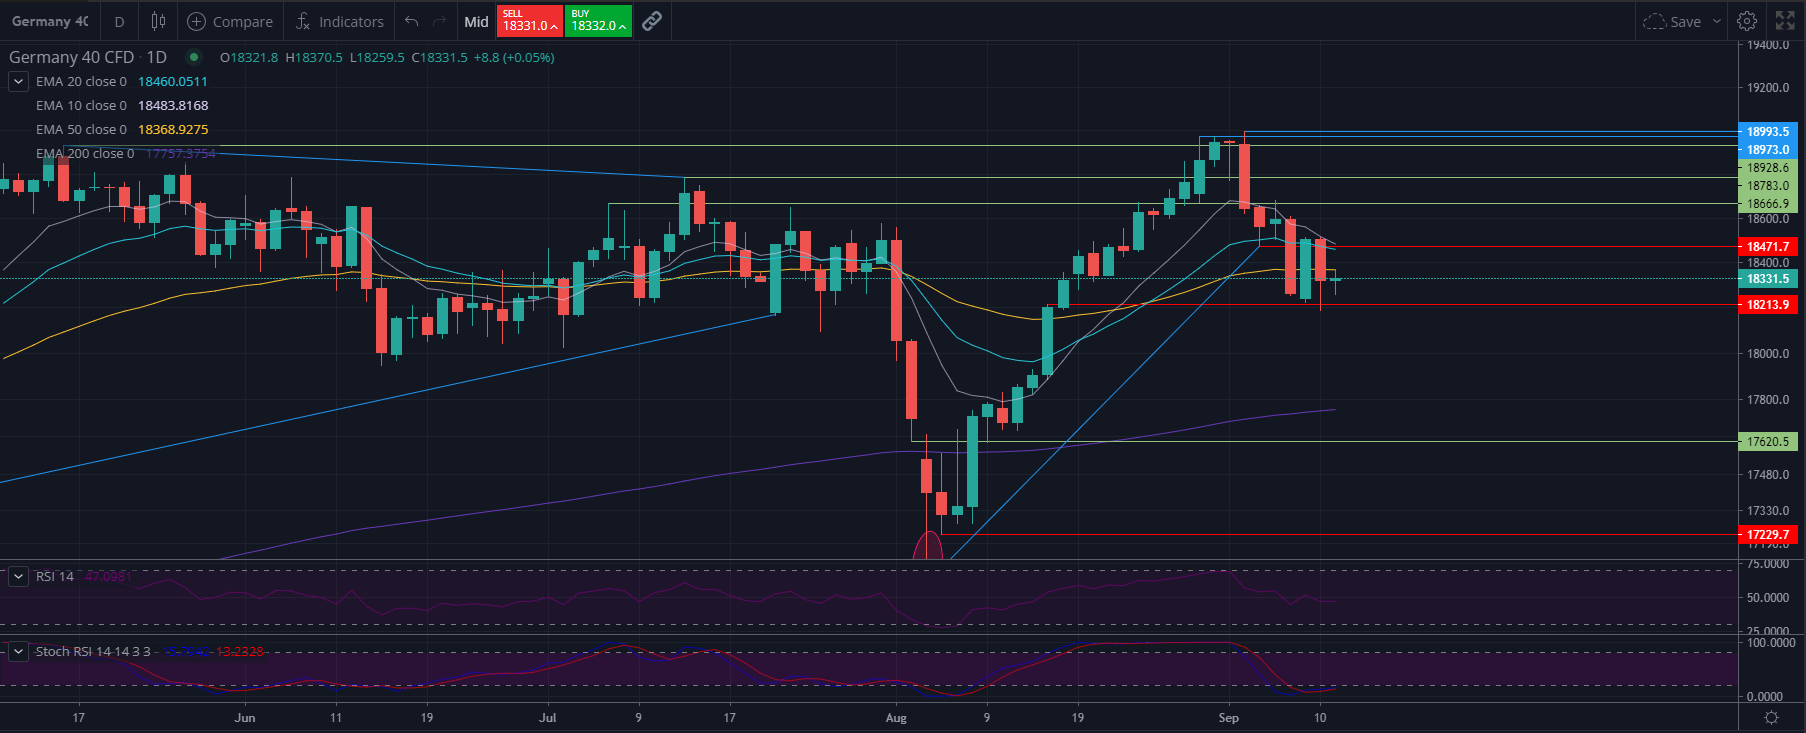
After last week's NFP scare, the price dropped to -1.77%. However, in Monday's trading session, the price was able to recover at least +1.33%. In yesterday's trading session, the price was in the range of Monday's highs and lows and did not deviate too much from the norm.
Currently, we are moving within the range of 18472 and 18213, which appear to be strong levels as they are previous highs and lows, and thus levels that must be broken through in order to advance.
On the daily chart, the price is currently trying to break the 50EMA as it is slightly below this level, but the candle is green and possibly forming a bottom tweezers formation. However, it is still early in the day, and given today's CPI and tomorrow's ECB interest rate decision, the market seems to remain cautious.
At tomorrow's ECB meeting, the ECB is expected to cut rates by 25 basis points, or 0.25%, which could support stock markets.
Other technical indicators such as the RSI are hovering around the neutral level of 50, while the stochastic RSI is currently oversold and a potential crossover is forming, which could indicate an increasing bullish momentum.
With high impact releases scheduled for today and tomorrow, traders seem to be cautious overall, and perhaps rightly so.
I will be back with more,
Kind regards,
Philip Papageorgiou
Follow me on X for daily insights: @Philipforexcom
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.

Gold Price Forecast: XAU/USD Avoids Breakdown as Yields Surged but Can it Continue?
Surging Treasury yields sent a jolt across markets last week but, so far, gold prices have held above the FOMC low. The big question now is whether that can continue and, if not, will bulls show up at $4100 or $4k like they did in June and July?

Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.