


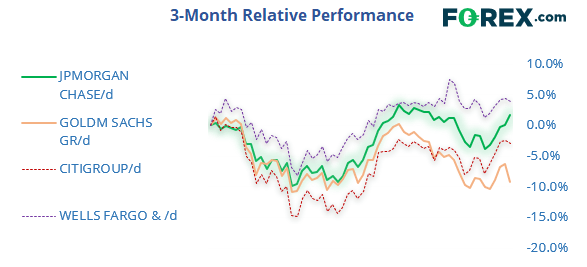


JPM Stands Out Among Big Banks Earnings Reports
For traders anticipating the worst, this morning’s bank earnings onslaught was not as bad as feared
Share this:

Yesterday, my colleague Ken Odeluga highlighted that falling interest rates (and the associated drop in lending revenues) would be a major theme as big US banks reported this quarter’s earnings.
Today, those fears were borne out in the reports of Goldman Sachs and Wells Fargo, though JP Morgan and Citigroup were able to navigate the headwinds successfully:
- Goldman Sachs reported EPS of $4.79, below estimates of $4.86, as the company works to transition away from proprietary trading to a more traditional retail bank.
- Wells Fargo also missed estimates at $1.07 in EPS vs. $1.14 expected in the first report after naming Charles Scharf as its new CEO. In a clear example of negative impact of falling interest rates, the consumer-focused bank reported worse-than-anticipated Net Interest Income despite 2% growth in total loans.
- JP Morgan beat estimates, reporting $2.68 in EPS vs. $2.46 eyed. The company also beat revenue estimates on the back of decent results from its investment banking division.
- Citigroup narrowly outperformed analysts’ expectations, with $1.97 in EPS vs. $19.5 eyed. Solid trading revenue figures helped the firm beat headline revenue expectations as well.
For traders anticipating the worst, this morning’s bank earnings onslaught was not as bad as feared. At the open, major indices are edging higher and the big banks are trading roughly in line with their earnings results:
- Goldman Sachs (GS) is trading down more than -3%.
- Wells Fargo (WFC) is dipping less than -1%
- JP Morgan (JPM) is tacking on nearly 2%.
- Citigroup (C) is essentially flat.
Looking ahead, the Federal Reserve appears likely to cut interest rates further this quarter, with futures traders pricing in an 80% chance of at least one interest rate cut by the end of the year and about a 25% probability of two cuts according to the CME’s FedWatch tool. If interest rates more broadly continue to trend lower, Wells Fargo’s large mortgage business could be a casuality.
Market volatility will also play a key role in the banks’ trading revenue; with geopolitical tensions on the rise, Brexit looming, and lingering concerns about the state of play between the US and China, a spike in volatility could benefit banks in Q4.
In addition to falling interest rates and market volatility, one key factor to watch moving forward will be buybacks. According to Barclays, large banks have reduced their outstanding shares by 2% over the last quarter, and after the Fed approved a record $173B in buybacks and dividends for the banks, this may be just the tip of the proverbial buyback iceberg. Citigroup alone reduced its share count by 11% over the past year!
While the broader economy may prefer banks to grow revenues through more traditional means, big banks’ investors will no doubt benefit from the firms returning capital to their shareholders.
Yesterday, my colleague Ken Odeluga highlighted that falling interest rates (and the associated drop in lending revenues) would be a major theme as big US banks reported this quarter’s earnings.
Today, those fears were borne out in the reports of Goldman Sachs and Wells Fargo, though JP Morgan and Citigroup were able to navigate the headwinds successfully:
- Goldman Sachs reported EPS of $4.79, below estimates of $4.86, as the company works to transition away from proprietary trading to a more traditional retail bank.
- Wells Fargo also missed estimates at $1.07 in EPS vs. $1.14 expected in the first report after naming Charles Scharf as its new CEO. In a clear example of negative impact of falling interest rates, the consumer-focused bank reported worse-than-anticipated Net Interest Income despite 2% growth in total loans.
- JP Morgan beat estimates, reporting $2.68 in EPS vs. $2.46 eyed. The company also beat revenue estimates on the back of decent results from its investment banking division.
- Citigroup narrowly outperformed analysts’ expectations, with $1.97 in EPS vs. $19.5 eyed. Solid trading revenue figures helped the firm beat headline revenue expectations as well.
For traders anticipating the worst, this morning’s bank earnings onslaught was not as bad as feared. At the open, major indices are edging higher and the big banks are trading roughly in line with their earnings results:
- Goldman Sachs (GS) is trading down more than -3%.
- Wells Fargo (WFC) is dipping less than -1%
- JP Morgan (JPM) is tacking on nearly 2%.
- Citigroup (C) is essentially flat.
Looking ahead, the Federal Reserve appears likely to cut interest rates further this quarter, with futures traders pricing in an 80% chance of at least one interest rate cut by the end of the year and about a 25% probability of two cuts according to the CME’s FedWatch tool. If interest rates more broadly continue to trend lower, Wells Fargo’s large mortgage business could be a casuality.
Market volatility will also play a key role in the banks’ trading revenue; with geopolitical tensions on the rise, Brexit looming, and lingering concerns about the state of play between the US and China, a spike in volatility could benefit banks in Q4.
In addition to falling interest rates and market volatility, one key factor to watch moving forward will be buybacks. According to Barclays, large banks have reduced their outstanding shares by 2% over the last quarter, and after the Fed approved a record $173B in buybacks and dividends for the banks, this may be just the tip of the proverbial buyback iceberg. Citigroup alone reduced its share count by 11% over the past year!
While the broader economy may prefer banks to grow revenues through more traditional means, big banks’ investors will no doubt benefit from the firms returning capital to their shareholders.
Related tags:
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
GBP/USD, Dow Jones Forecast: Key Technical Scenarios to Watch
GBP/USD and the Dow Jones are approaching critical technical levels amid earning optimism, Fed rate hike expectations, US-Iran developments, and persistent geopolitical risks.

The U.S. Dollar Is Rising Again and Nasdaq Is Feeling It
Nasdaq, the U.S. Dollar Index and Federal Reserve expectations are driving market sentiment ahead of a pivotal FOMC meeting. Razan Hilal, StoneX Market Analyst, explains how rising expectations for a hawkish Federal Reserve, persistent U.S.-Iran tensions and key technical levels on the U.S. Dollar Index could influence currencies, equities and precious metals in the weeks ahead.
US Dollar and Nasdaq Forecast: Fed, Microsoft, Meta, and Iran Talks in Focus
The US Dollar Index (DXY) continues to hold above the 101.00 mark, reinforcing its bullish structure, while the Nasdaq remains capped below the 29,000 resistance and its June-July consolidation range, reflecting cautious risk appetite ahead of the Federal Reserve's policy decision and major earnings releases on Wednesday.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.