



Market Brief Risk off may not be over yet
A summary of the FX & stock market trends & highlights from today's Asian mid-session.
Share this:

FX & Stock market snapshots as of [15/08/2019 0420 GMT]
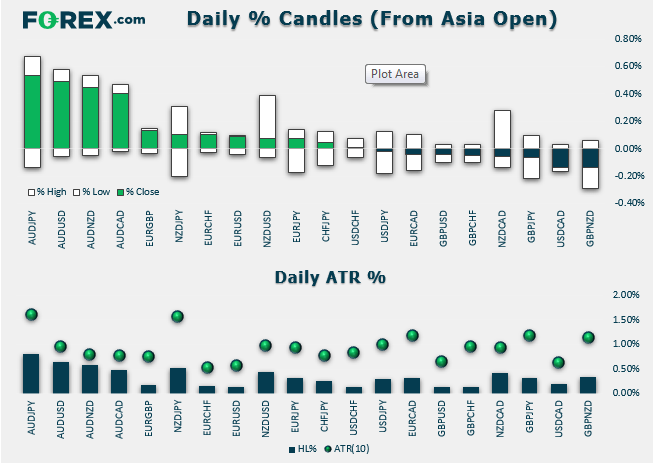
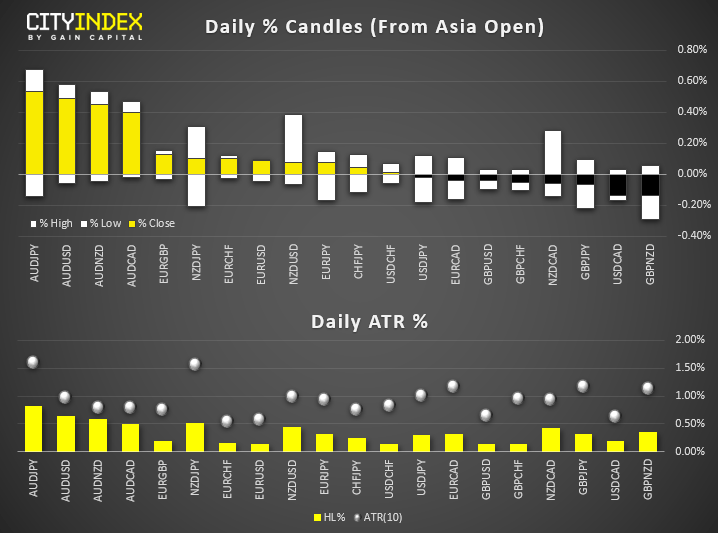
- Despite the mounting risks of a global economic recession reinforced by the U.S. Treasuries yield curve inversion between the 10-year and 2-year tenure, the risk sensitive AUD is the top performer in today’s Asian session. The AUD/USD, AUD/JPY and AUD/NZD have rallied by 0.40%.
- The catalyst for this rare outperformance seen in the Aussie was a better than expected AU jobs data for Jul. Employment change came in at +41.1K above consensus of +14.0K. In addition, the interest rate futures market has also pared down expectations of an RBA rate cut in Sep from a probability of 38% to 18%.
- Despite the intra-session stellar performance of the AUD/USD, the pair is still trading below its intermediate range resistance of 0.6820 in place since last Thurs, 08 Aug.
- Another risk sensitive pair, USD/JPY is also not showing much significant movement in today’s Asian session where it has traded in a tight range of around 0.20% below its 10-day ATR of 1.00%. From a technical analysis perspective, the pair is evolving within a minor “Pennant” range consolidation after a slide from its 13 Aug high of 106.97.
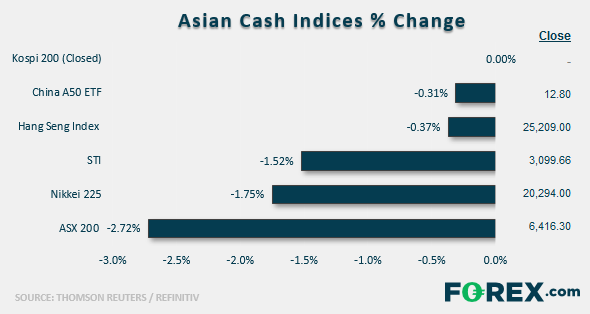
- In contrast seen in the FX markets, the worst performer in today’s Asian mid-session is Australia’s ASX 200 which has recorded a decline of -2.70% that broke below last Tues, 06 Aug low of 6444.
- The underperformance seen in the ASX 200 has been dragged down by external demand and growth-related sectors where Industrials, Technology and Energy stocks have tumbled by-3.19%, -4.55% and -5.01% respectively.
- The Korea’s Kospi 200 is closed today for a public holiday.
- Also, geopolitical risk in the Asian region, specifically in Hong Kong remains on red alert. U.S. politicians have raised the concerns of the sightings of Chinese armed police personnel and vehicles on the Hong Kong border where the China officials have reiterated that the on-going Hong Kong’s protests have resembled terrorism.
- Based on the latest tweets from U.S. President Trump yesterday, these tweets implied indirectly that the U.S. administration is trying to tie a trade agreement with China to the protests in Hong Kong being resolved “humanely”. Thus, with such implicit backing from the U.S, the Hong Kong protesters are not likely to be backing down soon which may see further weakness in the Hong Kong’s stock market that can trigger a contagion effect to the rest of the world.
- After a -2.9% tumble seen in the S&P500, the E-min futures is now trading higher by 0.45% to print a current intraday high of 2857 in today’s Asian session.
Up Next
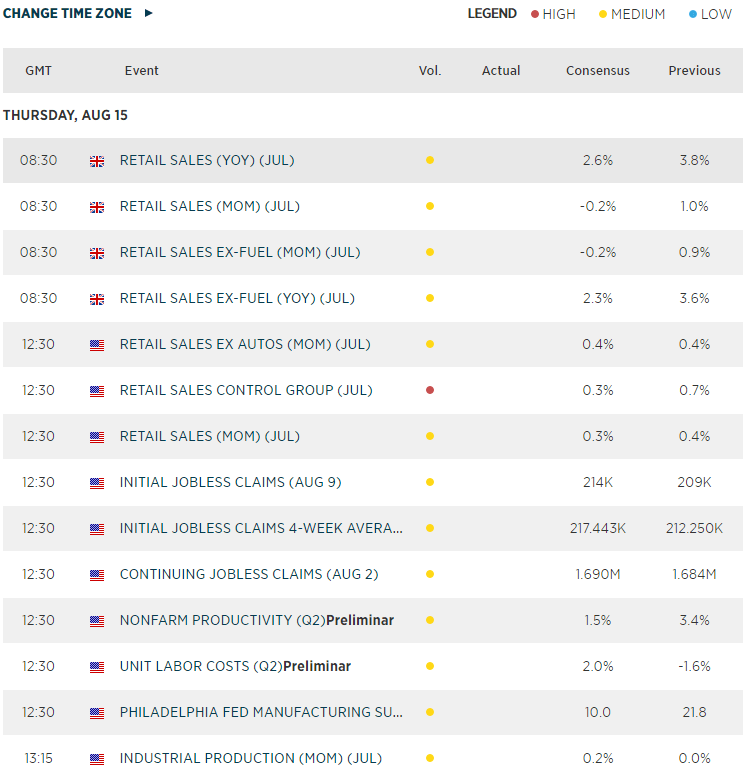
- U.K. retail sales for Jul out at 830 GMT where consensus is set at 2.6% y/y down from 3.8% y/y seen in Jun.
- U.S. retail sales (control group) for Jul out at 1230 GMT where consensus is set at 0.3% m/m down from 0.7% m/m seen in Jun.
- U.S. industrial production for Jul out at 1315 GMT where consensus is set at 0.2% m/m up from 0% m/m in Jun.
Macroeconomic Calendar
*Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.
FX & Stock market snapshots as of [15/08/2019 0420 GMT]
- Despite the mounting risks of a global economic recession reinforced by the U.S. Treasuries yield curve inversion between the 10-year and 2-year tenure, the risk sensitive AUD is the top performer in today’s Asian session. The AUD/USD, AUD/JPY and AUD/NZD have rallied by 0.40%.
- The catalyst for this rare outperformance seen in the Aussie was a better than expected AU jobs data for Jul. Employment change came in at +41.1K above consensus of +14.0K. In addition, the interest rate futures market has also pared down expectations of an RBA rate cut in Sep from a probability of 38% to 18%.
- Despite the intra-session stellar performance of the AUD/USD, the pair is still trading below its intermediate range resistance of 0.6820 in place since last Thurs, 08 Aug.
- Another risk sensitive pair, USD/JPY is also not showing much significant movement in today’s Asian session where it has traded in a tight range of around 0.20% below its 10-day ATR of 1.00%. From a technical analysis perspective, the pair is evolving within a minor “Pennant” range consolidation after a slide from its 13 Aug high of 106.97.
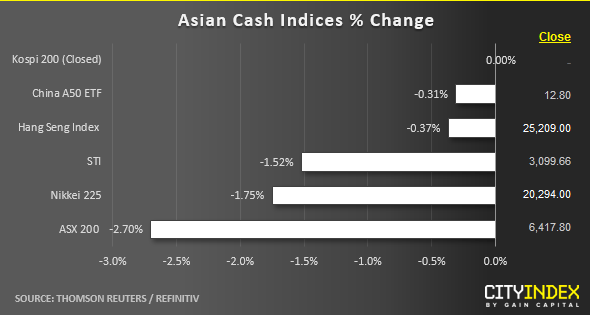
- In contrast seen in the FX markets, the worst performer in today’s Asian mid-session is Australia’s ASX 200 which has recorded a decline of -2.70% that broke below last Tues, 06 Aug low of 6444.
- The underperformance seen in the ASX 200 has been dragged down by external demand and growth-related sectors where Industrials, Technology and Energy stocks have tumbled by-3.19%, -4.55% and -5.01% respectively.
- The Korea’s Kospi 200 is closed today for a public holiday.
- Also, geopolitical risk in the Asian region, specifically in Hong Kong remains on red alert. U.S. politicians have raised the concerns of the sightings of Chinese armed police personnel and vehicles on the Hong Kong border where the China officials have reiterated that the on-going Hong Kong’s protests have resembled terrorism.
- Based on the latest tweets from U.S. President Trump yesterday, these tweets implied indirectly that the U.S. administration is trying to tie a trade agreement with China to the protests in Hong Kong being resolved “humanely”. Thus, with such implicit backing from the U.S, the Hong Kong protesters are not likely to be backing down soon which may see further weakness in the Hong Kong’s stock market that can trigger a contagion effect to the rest of the world.
- After a -2.9% tumble seen in the S&P500, the E-min futures is now trading higher by 0.45% to print a current intraday high of 2857 in today’s Asian session.
Up Next
- U.K. retail sales for Jul out at 830 GMT where consensus is set at 2.6% y/y down from 3.8% y/y seen in Jun.
- U.S. retail sales (control group) for Jul out at 1230 GMT where consensus is set at 0.3% m/m down from 0.7% m/m seen in Jun.
- U.S. industrial production for Jul out at 1315 GMT where consensus is set at 0.2% m/m up from 0% m/m in Jun.
Macroeconomic Calendar
*Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

ASX 200 Rebound Stalls Despite Wall Street Surge
The ASX 200 rebound is struggling for traction despite a powerful Wall Street rally, leaving 8800 resistance and downside risks in focus.


Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.