



Q4 2021 US Reporting Season Preview
Q4 reporting season picks up speed this evening with reports from financial heavyweights JP Morgan, Wells Fargo, Citigroup, and Blackrock, before 114 companies report next week. See below the key themes and trends we'll be monitoring.
Share this:
Macro Overview
2021 saw the S&P500 hit fresh record highs on an astonishing 70 separate days. It is noticeable that the first two weeks of 2022 have seen a continuation of the volatility that marked the final months of 2021.
US inflation recently reached an almost 40 year high, hitting an annualised 7% in December. To counter this, the Federal Reserve has become increasingly hawkish.
In response, market expectations have shifted towards faster balance sheet normalization, with "quantitative tightening" to begin in September after Fed lift-off in June or possibly as early as March. A prospect that has rattled tech stocks.
Meanwhile, surging Omicron cases have left hospitals straining under the weight of numbers, disrupting global supply chains and grocery shelves empty. A development that will weigh on Q1 growth, likely to be reflected in some company's forward guidance.
Earnings
Despite the headwinds outlined above, S&P500 companies are expected to deliver strong earnings growth again. According to Factset, "For Q4 2021, the estimated earnings growth rate for the S&P 500 is 21.7%."
Presuming this is the confirmed growth rate for the quarter, it will mark the fourth straight quarter of earnings growth above 20% and lift full years earning growth to more than 40% for the full year.
Guidance
As noted by FactSet in the first week of January, "93 S&P 500 companies have issued EPS guidance for the fourth quarter. This number is slightly below the 5-year average of 100. Of these 93 companies, 56 have issued negative EPS guidance, and 37 have issued positive EPS guidance."
This marks the first time since Q2 2020 that S&P500 companies have issued more negative EPS guidance than positive guidance. Despite this, the estimated (year over year) earnings growth for Q4 2021 is above the expectations from the start of Q4.
Sector Performance
As noted by Factset, the Energy sector led by companies such as Exxon Mobil and Chevron have recorded the largest percentage increase in estimated (dollar-level) earnings of all eleven sectors since the start of the quarter at 40.8% (to $28.1 billion from $20.0 billion).
The Consumer Discretionary sector led by Amazon.com has recorded the largest percentage decrease in estimated (dollar-level) earnings of all eleven sectors since the start of the quarter at -15.1% (to $27.1 billion from $32.0 billion).
S&P500 Technical Outlook
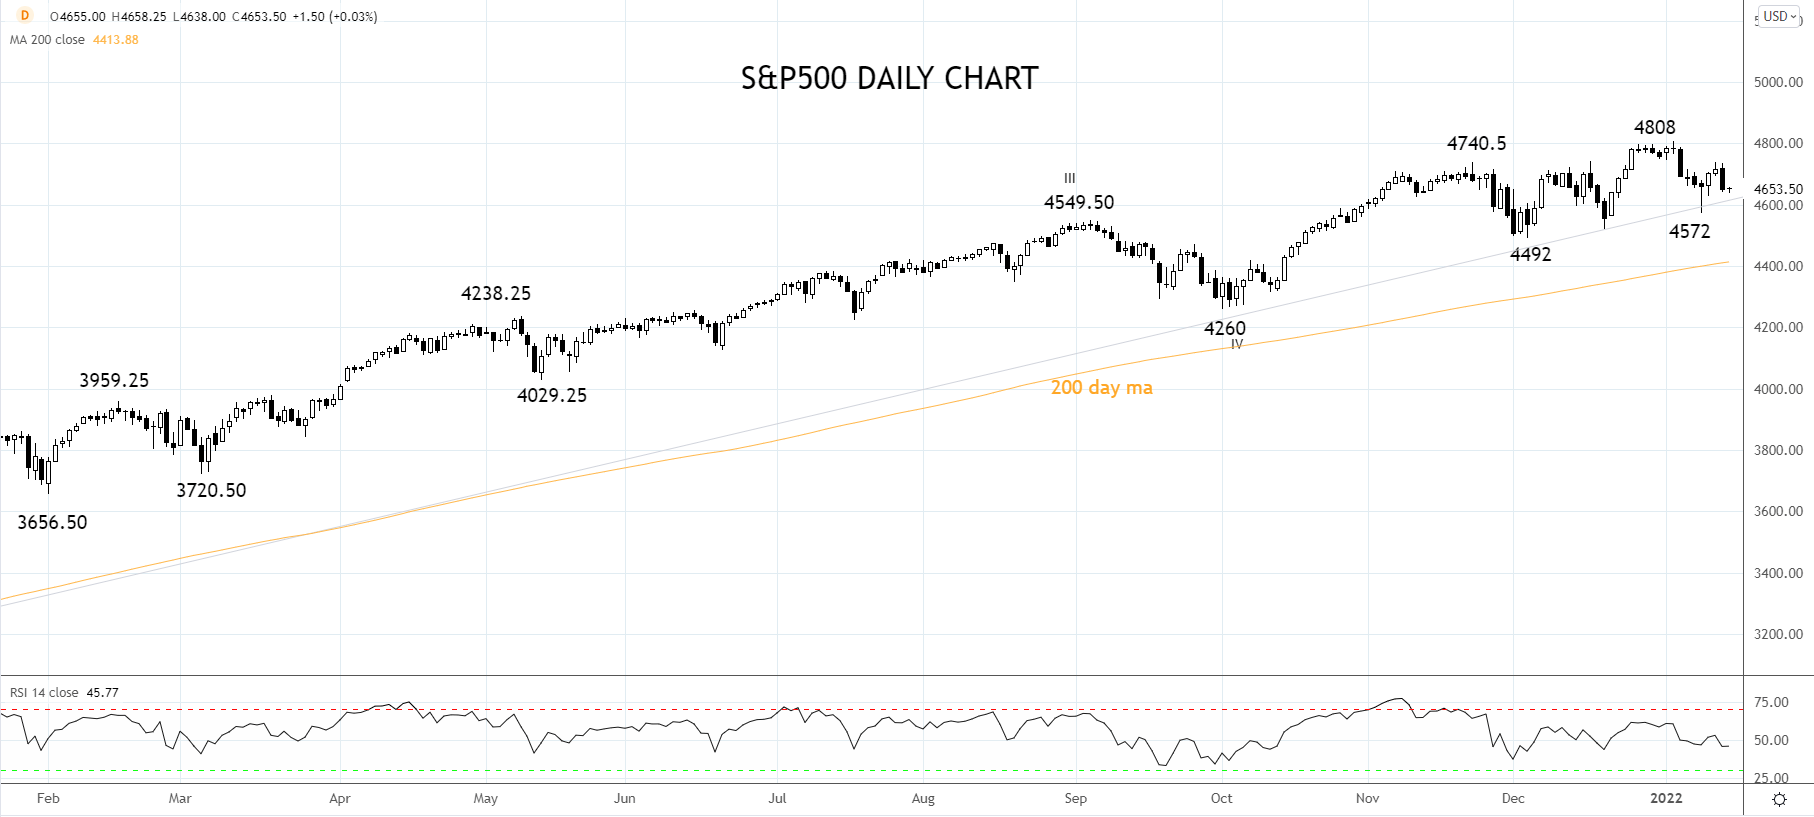
The overnight decline has the S&P500 eyeing important trendline support at 4620/00ish from the March 2020, 2174 low.
Providing the S&P500 remains above 4620/00 (closing basis), look for a push towards 5000 during the first quarter of 2022.
However, should a sustained break below 4620/00ish occur, the risks are for a deeper pullback towards 4400.
Source Tradingview. The figures stated areas of January 14th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Macro Overview
2021 saw the S&P500 hit fresh record highs on an astonishing 70 separate days. It is noticeable that the first two weeks of 2022 have seen a continuation of the volatility that marked the final months of 2021.
US inflation recently reached an almost 40 year high, hitting an annualised 7% in December. To counter this, the Federal Reserve has become increasingly hawkish.
In response, market expectations have shifted towards faster balance sheet normalization, with "quantitative tightening" to begin in September after Fed lift-off in June or possibly as early as March. A prospect that has rattled tech stocks.
Meanwhile, surging Omicron cases have left hospitals straining under the weight of numbers, disrupting global supply chains and grocery shelves empty. A development that will weigh on Q1 growth, likely to be reflected in some company's forward guidance.
Earnings
Despite the headwinds outlined above, S&P500 companies are expected to deliver strong earnings growth again. According to Factset, "For Q4 2021, the estimated earnings growth rate for the S&P 500 is 21.7%."
Presuming this is the confirmed growth rate for the quarter, it will mark the fourth straight quarter of earnings growth above 20% and lift full years earning growth to more than 40% for the full year.
Guidance
As noted by FactSet in the first week of January, "93 S&P 500 companies have issued EPS guidance for the fourth quarter. This number is slightly below the 5-year average of 100. Of these 93 companies, 56 have issued negative EPS guidance, and 37 have issued positive EPS guidance."
This marks the first time since Q2 2020 that S&P500 companies have issued more negative EPS guidance than positive guidance. Despite this, the estimated (year over year) earnings growth for Q4 2021 is above the expectations from the start of Q4.
Sector Performance
As noted by Factset, the Energy sector led by companies such as Exxon Mobil and Chevron have recorded the largest percentage increase in estimated (dollar-level) earnings of all eleven sectors since the start of the quarter at 40.8% (to $28.1 billion from $20.0 billion).
The Consumer Discretionary sector led by Amazon.com has recorded the largest percentage decrease in estimated (dollar-level) earnings of all eleven sectors since the start of the quarter at -15.1% (to $27.1 billion from $32.0 billion).
S&P500 Technical Outlook
The overnight decline has the S&P500 eyeing important trendline support at 4620/00ish from the March 2020, 2174 low.
Providing the S&P500 remains above 4620/00 (closing basis), look for a push towards 5000 during the first quarter of 2022.
However, should a sustained break below 4620/00ish occur, the risks are for a deeper pullback towards 4400.
Source Tradingview. The figures stated areas of January 14th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Wall Street Split Widens Into Month-End 9 26 2026
Nasdaq strength contrasts with mounting Dow pressure as rising Treasury yields raise the stakes for stocks heading into the monthly close.

Equity Indices Q4, 2026 Outlook: Cracks Begin to Show
There's still an open door for a melt-up in the S&P 500 and Nasdaq but the Dow and Russell 2000 are looking more vulnerable, and until calm hits the Treasuries market there's a higher probability for volatility. The big question is whether that's a next quarter theme or not.


S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.