




Ryanair holds on with add ons
It’s not a great assessment of Europe’s airline sector when add-ons save the outlook
Share this:

It’s not a great assessment of Europe’s airline sector when add-ons save the outlook
But with Ryanair’s shares down 43% over two years of low-cost operator hell, investors will take it. The stock lifted as much as 4% in Dublin before slipping 2% into the red. No one’s getting carried away. These numbers are promising, not stellar.
- Q1 profit after tax down 21% on the year to €243m
- Revenues up 11% to €2.3bn
- Average fare down 6%
- Ancillary revenues – from sales of food, extra bag space, faster boarding, etc. – up 14%
- Passenger traffic up 11% to 42 million
- Costs up 19%; including fuel costs up 24%
One of the industry’s key challenges remains a years-long face-off during which fare rises have been aggressively curtailed. There’s little sign Ryanair is ready to blink. It notes the 6% average drop in the first quarter “stimulated 11% traffic growth”. And though it still has the lowest unit costs, it hasn’t been immune to rising overall expenses. Its fuel bill leapt 24%, despite hedging that’s widely thought to be favourable relative to peers.
Delayed delivery of Boeing’s 737 MAX adds another dimension. The embattled plane maker is now unlikely to receive a renewed safety certification by September, as mooted. In turn, Ryanair’s in-service date, initially December at the latest, has slipped to January or February. In fact, there’s little true visibility on Boeing’s chances of meeting those dates either. Compensation should offset most of the dent to earnings, but that too lacks clarity for now. Pilot pay rises and hiring to increase the ratio of staff to passengers will reduce leeway further. Little wonder Ryanair sees expected growth for summer 2020 peak of just 3%.
All told, the group has afforded investors some relief by keeping annual profit guidance between €750m-€950m when the fear was a dip towards the lower end. Yet leg room remains tight and could squeeze further. Chiefly, Lufthansa’s Eurowings appears to be on an increasingly do or die course to retain Air Berlin share, selling excess seats below cost. UK and Ireland pilot ballot results are due next week. Ryanair’s premium valuation reflects its industry-leading cash flow generation and balance sheet, but growth worries are less defined. In other words, there’s room for market forecasts to fall, if not plunge. The shares, down 6% so far this year, could level off, though won’t soar.
Chart thoughts
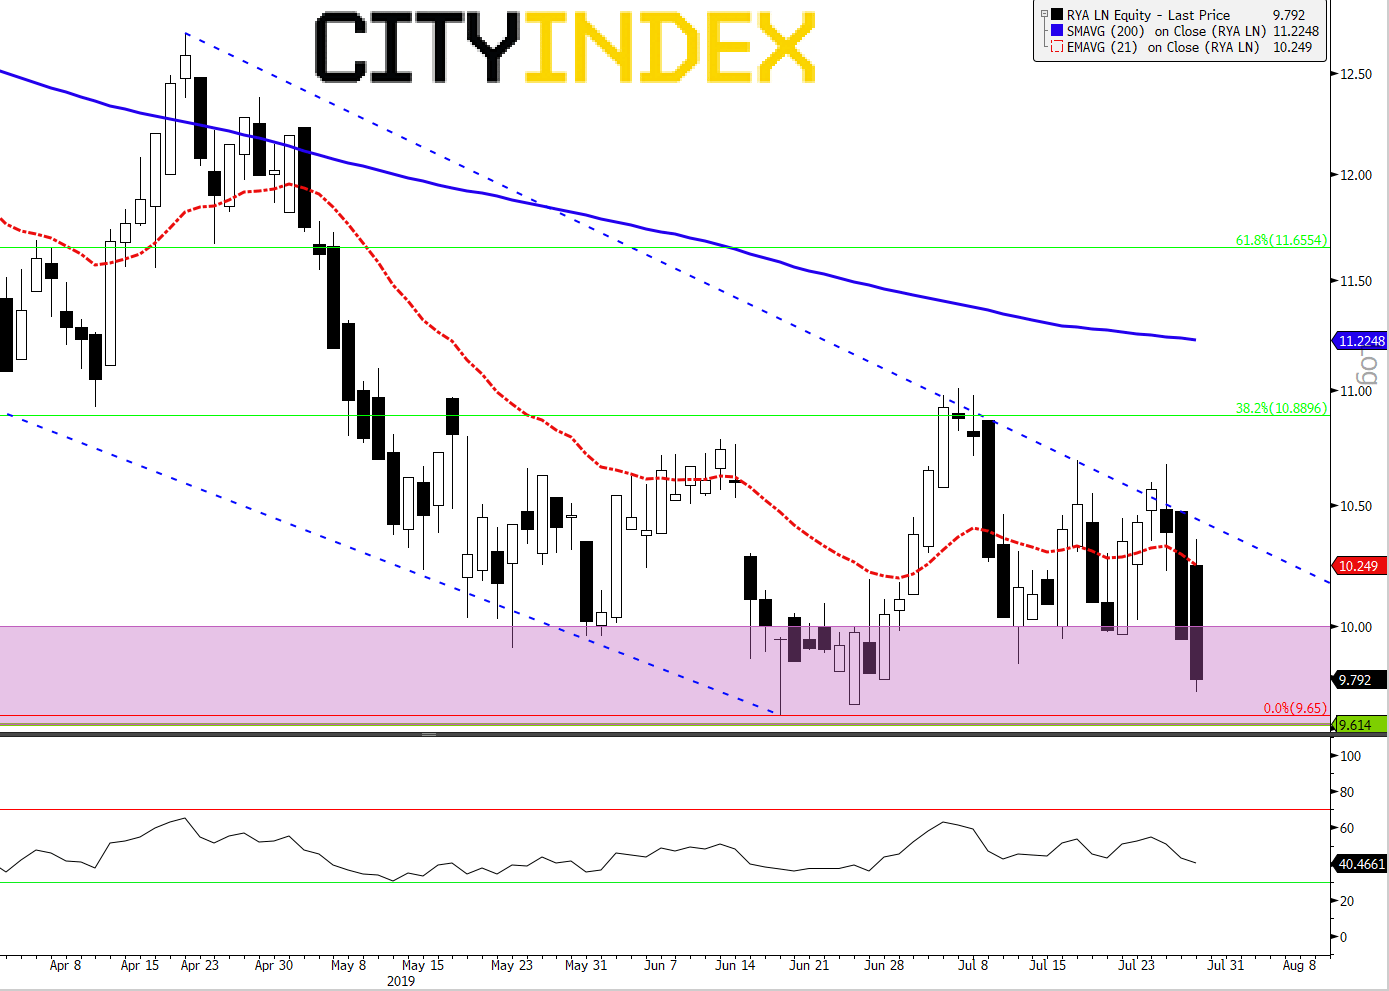
A relatively shallow retracement of the resigned reversal to the downside from April’s highs should warn buyers to keep their sights set low. The bounce up from June's four year lows, the second visit in six months, stalled just above €10.88, which equates to 38.2% of the year’s prior advance. The attempt to climb didn’t definitely breach the upper wall of a channel in place since mid-April, indicating the market remains wary even at these subdued prices. What RYA has going for it here is proven support. Assume the backstop is more of a band over which emphatic rejection of prices below €9.61 was observed in December, January and June. With price currently toying with the upper end of the range (call it €10) equilibrium looks near. A potential break out in a few weeks at the apex of the structure should clarify whether bulls of bears are in control. To be sure though, with price tracking below the 21-day exponential average and a sickly-looking RSI, enthusiasm over a possible upside break, isn’t apparent.
Ryanair Holdings Plc. – daily [29/07/2019 14:43:45]
Source: Bloomberg/FOREX.com
It’s not a great assessment of Europe’s airline sector when add-ons save the outlook
But with Ryanair’s shares down 43% over two years of low-cost operator hell, investors will take it. The stock lifted as much as 4% in Dublin before slipping 2% into the red. No one’s getting carried away. These numbers are promising, not stellar.
- Q1 profit after tax down 21% on the year to €243m
- Revenues up 11% to €2.3bn
- Average fare down 6%
- Ancillary revenues – from sales of food, extra bag space, faster boarding, etc. – up 14%
- Passenger traffic up 11% to 42 million
- Costs up 19%; including fuel costs up 24%
One of the industry’s key challenges remains a years-long face-off during which fare rises have been aggressively curtailed. There’s little sign Ryanair is ready to blink. It notes the 6% average drop in the first quarter “stimulated 11% traffic growth”. And though it still has the lowest unit costs, it hasn’t been immune to rising overall expenses. Its fuel bill leapt 24%, despite hedging that’s widely thought to be favourable relative to peers.
Delayed delivery of Boeing’s 737 MAX adds another dimension. The embattled plane maker is now unlikely to receive a renewed safety certification by September, as mooted. In turn, Ryanair’s in-service date, initially December at the latest, has slipped to January or February. In fact, there’s little true visibility on Boeing’s chances of meeting those dates either. Compensation should offset most of the dent to earnings, but that too lacks clarity for now. Pilot pay rises and hiring to increase the ratio of staff to passengers will reduce leeway further. Little wonder Ryanair sees expected growth for summer 2020 peak of just 3%.
All told, the group has afforded investors some relief by keeping annual profit guidance between €750m-€950m when the fear was a dip towards the lower end. Yet leg room remains tight and could squeeze further. Chiefly, Lufthansa’s Eurowings appears to be on an increasingly do or die course to retain Air Berlin share, selling excess seats below cost. UK and Ireland pilot ballot results are due next week. Ryanair’s premium valuation reflects its industry-leading cash flow generation and balance sheet, but growth worries are less defined. In other words, there’s room for market forecasts to fall, if not plunge. The shares, down 6% so far this year, could level off, though won’t soar.
Chart thoughts
A relatively shallow retracement of the resigned reversal to the downside from April’s highs should warn buyers to keep their sights set low. The bounce up from June's four year lows, the second visit in six months, stalled just above €10.88, which equates to 38.2% of the year’s prior advance. The attempt to climb didn’t definitely breach the upper wall of a channel in place since mid-April, indicating the market remains wary even at these subdued prices. What RYA has going for it here is proven support. Assume the backstop is more of a band over which emphatic rejection of prices below €9.61 was observed in December, January and June. With price currently toying with the upper end of the range (call it €10) equilibrium looks near. A potential break out in a few weeks at the apex of the structure should clarify whether bulls of bears are in control. To be sure though, with price tracking below the 21-day exponential average and a sickly-looking RSI, enthusiasm over a possible upside break, isn’t apparent.
Ryanair Holdings Plc. – daily [29/07/2019 14:43:45]
Source: Bloomberg/City Index
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Update: Will Fed Expectations Keep Pressure on the Euro?
The week continues to present challenges for the euro's short-term strength. This is reflected in the recent performance of EUR/USD, which has declined by nearly 0.6% over the last three trading sessions

EUR/USD Forecast: Euro Extends Losses Ahead of Fed Rate Decision
The euro has started to face a more challenging period in the short term. The EUR/USD pair has already declined by nearly 0.81% over the last four trading sessions, a move that has begun to reinforce a meaningful bearish bias in favor of the U.S. dollar.
EUR/USD Analysis: Euro Attempts to Recover Following the ECB Decision
Today's session has been particularly relevant for the euro's performance in the short term. After the EUR/USD registered a decline of nearly 0.3% during the session, the European currency has managed to recover a large part of its losses.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.