



S&P 500 Forecast For the Week Ahead: Pullback Potential
Stocks got rocked on Friday despite an abysmal PMI print, which suggests that the door may be opening for rate cuts later this year. Perhaps more concerning to the matter is the USD/JPY sell-off.
Share this:

S&P 500 Talking Points:
- Chasing breakouts at ATHs in equities continues to be a challenging strategy and that showed again last week after the S&P 500 reversed shortly after setting a fresh ATH.
- As I had looked at in the equity forecast for this year and the top trade idea for 2025, pullbacks to support can be optimal backdrops for bullish positioning in stocks.
- With USD/JPY breaking below the 150.00 level again, pushed along by an abysmal PMI print on Friday morning, the fear of global de-leveraging is bringing an impact on equities. A reversal is not a foregone conclusion at this point, but bulls should be cautious through next week’s open, and picky with exposure as this could quickly turn into a falling knife situation.
It's been a choppy start to the year for U.S. equities with the S&P 500 holding within a relatively tight trading range. I looked at this on Wednesday, highlighting the fact that despite the back-and-forth price action, there has been opportunity for shorter-term traders as there’s been several smaller-scale dips and rips.
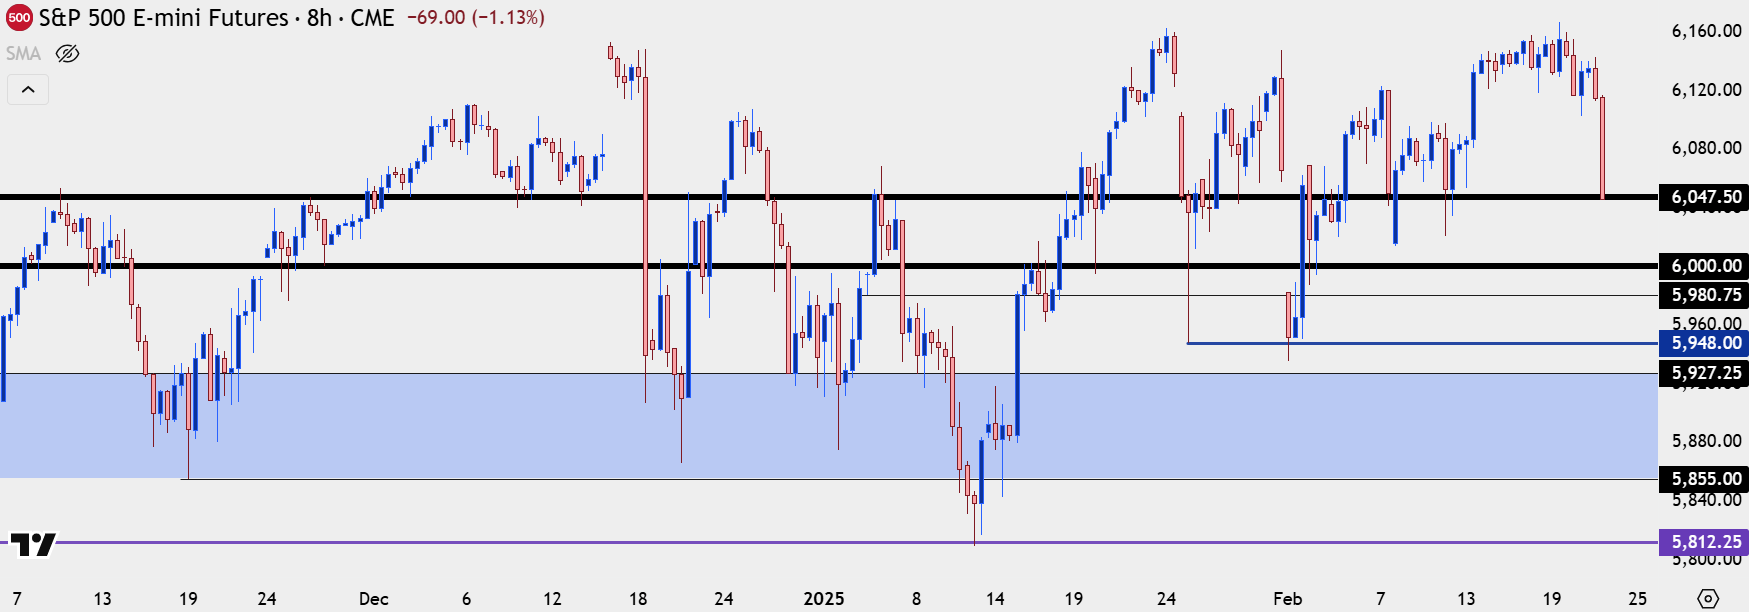
As we wind into the close on Friday, stocks are putting in a sizable dip and as of this writing, S&P 500 futures are re-testing the 6050 level following a failure from bulls to push a breakout at all-time-highs earlier in the week. This has been a big level in the recent past as it was initial resistance back in November, just after the election, before coming in as support and resistance on multiple occasions since.
The challenge as of this writing is what may lie ahead as we near a weekly close, and there could be growing fear of a de-leveraging event as I’ll look at below.
S&P 500 Futures Eight-Hour Chart
 Chart prepared by James Stanley; data derived from Tradingview
S&P 500 and USD/JPY
I’ve been tracking this theme for some time now and there’ve been several bear traps set in USD/JPY as Japanese policy makers have remained non-committal towards future rate hikes. But the fact of the matter is that Japanese inflation has remained firm and the concern is that the BoJ could get caught behind the curve, similar to the Fed in 2021 when they continually said that inflation would abate on its own.
The carry trade that build in 2021 and 2022 was a driver of global leverage as large investors could borrow money at cheap rates in Japan, and then invest that capital elsewhere where rates and investment returns were higher. As long as the rate paradigm remains tilted in the direction of the high-yielder, that increasing leverage component can continue.
But when that shifts, matters can change quickly, especially if the trade has become crowded. This is what we saw last July, when lower-than-expected CPI in the U.S. brought along realistic hopes for rate cuts from the FOMC. And at the time, the BoJ had started to shift, as well, highlighting the potential for change ahead in USD/JPY. It didn’t take long but U.S. equities soon took a turn for the worse and headlines were rampantly pointing to the unwind of the Yen carry trade as the culprit behind the sell-off.
BoJ members pulled back from hawkish rhetoric and as the USD came back to life in Q4, so did USD/JPY and U.S. equities, helping to erase those prior fears.
At this point USD/JPY remains well-elevated from the lows in early-2021 of below the 103 handle, and logically there’s still a considerable amount of carry trade that hasn’t unwound yet, which could act as a drag on stocks should that theme re-appear.
It’s still early but the sell-off in S&P 500 futures seems to be linked to the breakdown in USD/JPY below the 150-level. And perhaps coincidentally, this driven by an abysmal PMI report from earlier this morning, which normally would be considered a positive for equities as it increases hopes for rate cuts from the FOMC.
S&P 500, USD/JPY Perspective
At this point I think it’s reasonable to assume that neither the Fed nor the Bank of Japan wants to deal with another scenario such as we saw last summer, when panic peaked as the VIX spiked to its third-highest level, ever. So, at this point, I’m assuming bullish potential in stocks until something changes or shifts. But if we see the Yen carry unwind theme grow next week, that shift could happen sooner rather than later. The Core PCE report on Friday could be a big factor as signs of weaker US inflation could further drive rate cut hopes, which could thereby prod further motivation for USD/JPY longs to close positions.
At this point, I’m continuing to track support in the S&P 500 at the 6k level, followed by shorter-term levels at 5980 and 5948. If the 5948 level is traded through on a daily close basis, then I’ll begin to open the door for larger reversal potential and that will point to 5812 and 5721 as next supports, with 6k serving as lower-high resistance potential.
S&P 500 Futures Daily Chart
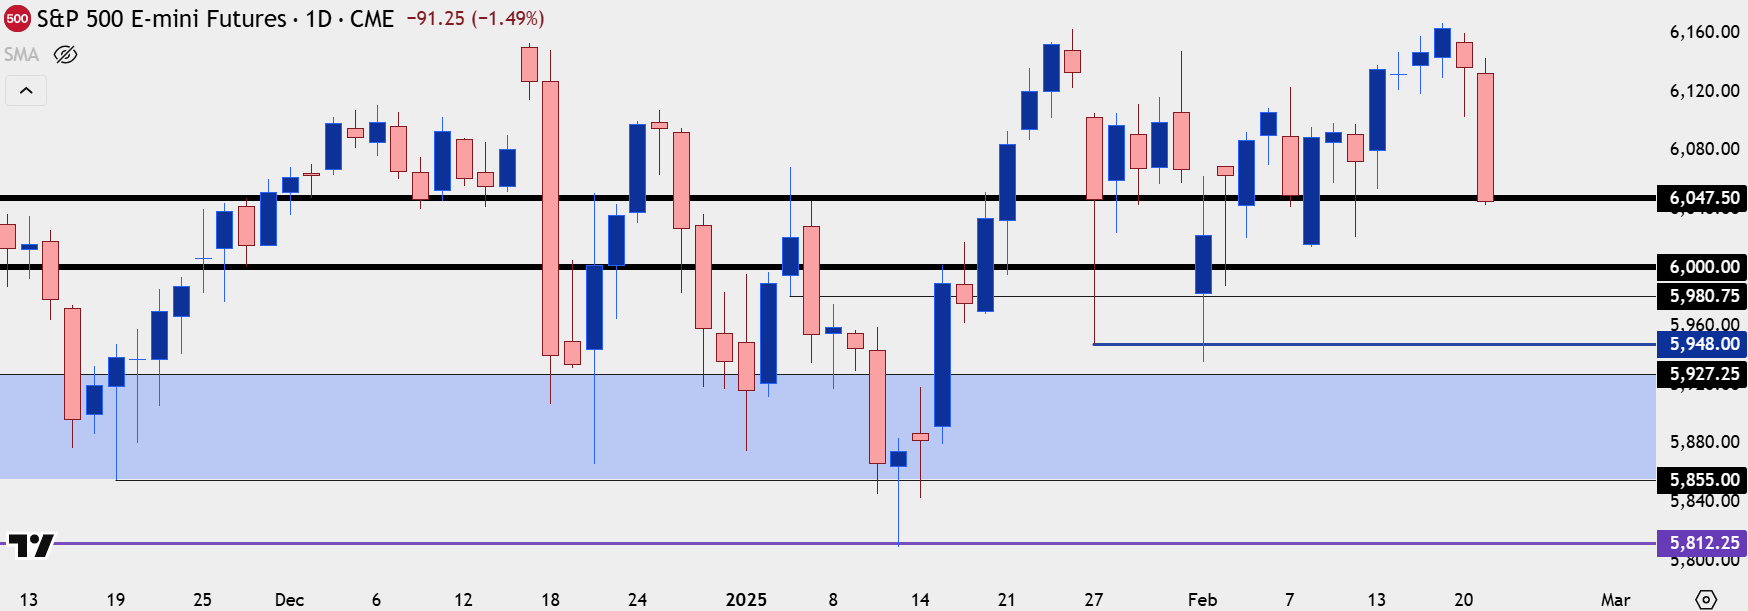 Chart prepared by James Stanley; data derived from Tradingview
--- written by James Stanley, Senior Strategist
S&P 500 Talking Points:
- Chasing breakouts at ATHs in equities continues to be a challenging strategy and that showed again last week after the S&P 500 reversed shortly after setting a fresh ATH.
- As I had looked at in the equity forecast for this year and the top trade idea for 2025, pullbacks to support can be optimal backdrops for bullish positioning in stocks.
- With USD/JPY breaking below the 150.00 level again, pushed along by an abysmal PMI print on Friday morning, the fear of global de-leveraging is bringing an impact on equities. A reversal is not a foregone conclusion at this point, but bulls should be cautious through next week’s open, and picky with exposure as this could quickly turn into a falling knife situation.
It's been a choppy start to the year for U.S. equities with the S&P 500 holding within a relatively tight trading range. I looked at this on Wednesday, highlighting the fact that despite the back-and-forth price action, there has been opportunity for shorter-term traders as there’s been several smaller-scale dips and rips.
As we wind into the close on Friday, stocks are putting in a sizable dip and as of this writing, S&P 500 futures are re-testing the 6050 level following a failure from bulls to push a breakout at all-time-highs earlier in the week. This has been a big level in the recent past as it was initial resistance back in November, just after the election, before coming in as support and resistance on multiple occasions since.
The challenge as of this writing is what may lie ahead as we near a weekly close, and there could be growing fear of a de-leveraging event as I’ll look at below.
S&P 500 Futures Eight-Hour Chart
S&P 500 and USD/JPY
I’ve been tracking this theme for some time now and there’ve been several bear traps set in USD/JPY as Japanese policy makers have remained non-committal towards future rate hikes. But the fact of the matter is that Japanese inflation has remained firm and the concern is that the BoJ could get caught behind the curve, similar to the Fed in 2021 when they continually said that inflation would abate on its own.
The carry trade that build in 2021 and 2022 was a driver of global leverage as large investors could borrow money at cheap rates in Japan, and then invest that capital elsewhere where rates and investment returns were higher. As long as the rate paradigm remains tilted in the direction of the high-yielder, that increasing leverage component can continue.
But when that shifts, matters can change quickly, especially if the trade has become crowded. This is what we saw last July, when lower-than-expected CPI in the U.S. brought along realistic hopes for rate cuts from the FOMC. And at the time, the BoJ had started to shift, as well, highlighting the potential for change ahead in USD/JPY. It didn’t take long but U.S. equities soon took a turn for the worse and headlines were rampantly pointing to the unwind of the Yen carry trade as the culprit behind the sell-off.
BoJ members pulled back from hawkish rhetoric and as the USD came back to life in Q4, so did USD/JPY and U.S. equities, helping to erase those prior fears.
At this point USD/JPY remains well-elevated from the lows in early-2021 of below the 103 handle, and logically there’s still a considerable amount of carry trade that hasn’t unwound yet, which could act as a drag on stocks should that theme re-appear.
It’s still early but the sell-off in S&P 500 futures seems to be linked to the breakdown in USD/JPY below the 150-level. And perhaps coincidentally, this driven by an abysmal PMI report from earlier this morning, which normally would be considered a positive for equities as it increases hopes for rate cuts from the FOMC.
S&P 500, USD/JPY Perspective
At this point I think it’s reasonable to assume that neither the Fed nor the Bank of Japan wants to deal with another scenario such as we saw last summer, when panic peaked as the VIX spiked to its third-highest level, ever. So, at this point, I’m assuming bullish potential in stocks until something changes or shifts. But if we see the Yen carry unwind theme grow next week, that shift could happen sooner rather than later. The Core PCE report on Friday could be a big factor as signs of weaker US inflation could further drive rate cut hopes, which could thereby prod further motivation for USD/JPY longs to close positions.
At this point, I’m continuing to track support in the S&P 500 at the 6k level, followed by shorter-term levels at 5980 and 5948. If the 5948 level is traded through on a daily close basis, then I’ll begin to open the door for larger reversal potential and that will point to 5812 and 5721 as next supports, with 6k serving as lower-high resistance potential.
S&P 500 Futures Daily Chart
--- written by James Stanley, Senior Strategist
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

ASX 200 Rebound Stalls Despite Wall Street Surge
The ASX 200 rebound is struggling for traction despite a powerful Wall Street rally, leaving 8800 resistance and downside risks in focus.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.