




Tariffs Tariffs and More Tariffs
US President Trump decided enough is enough already.
Share this:

Yesterday, US President Trump decided enough is enough already. First, he restored tariffs on Argentina and Brazil for aluminum and steel imports to the United States. He cited a “massive devaluation of their currencies”, which in turn hurts American farmers. Later in the day, it was determined after a five-month investigation that a French digital tax discriminated against American Internet companies. As a result, tariffs of up to $2.4 billion on French consumer imports to the United States was proposed. In addition, ISM Manufacturing Data was worse than expected in the United States. Combine these factors together, and most major stock indices were down near 1% yesterday. In addition, the US Dollar Index was also down 0.5%.
Today, President Trump said, “I have no deadline on China deal and it might be better to wait until after November 2020 election”. And later, Commerce Secretary Wilbur Ross said, “December 15th tariffs on Chinese imports will be applied unless there is some real reason to postpone them, such as substantive progress in talks”. Stocks continued to sell off today, with major indices currently down nearly another 1%.
Source: Tradingview, City Index
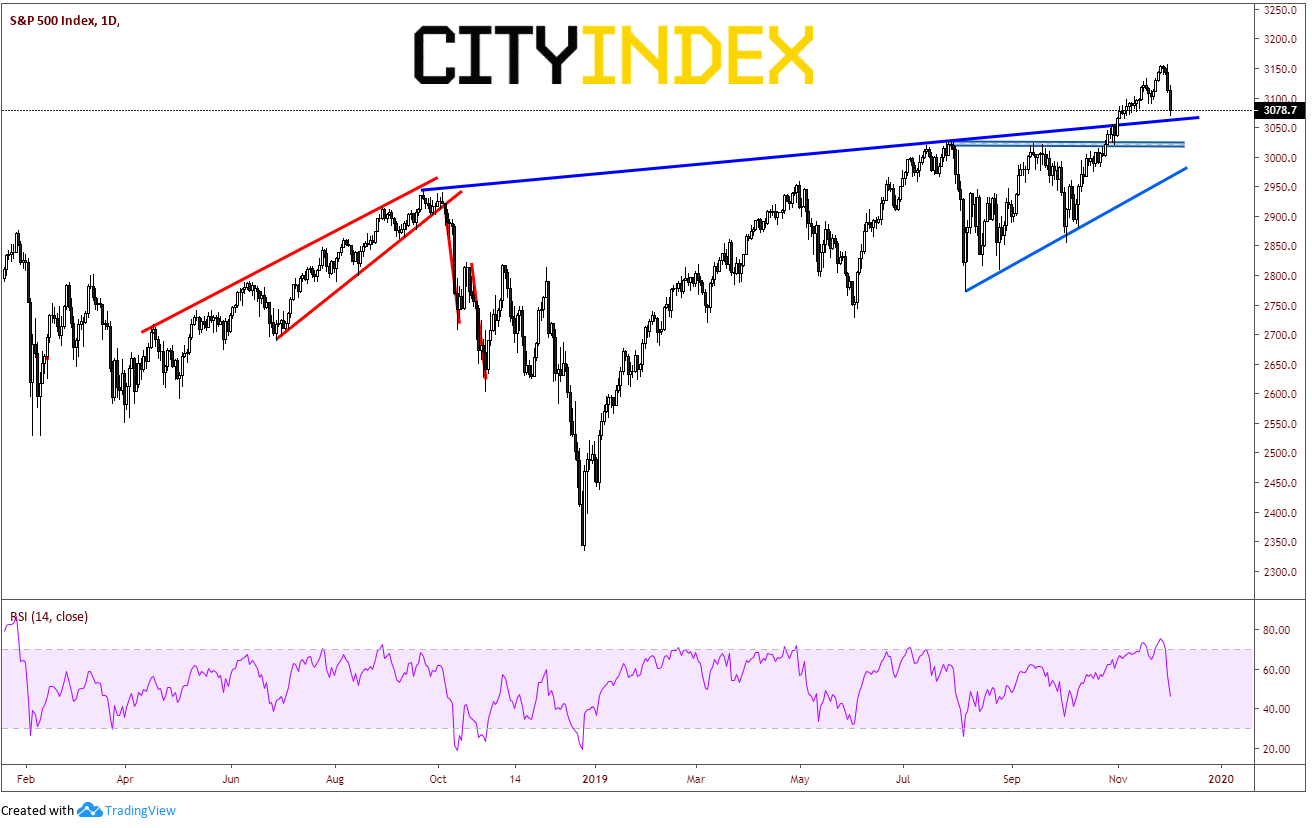
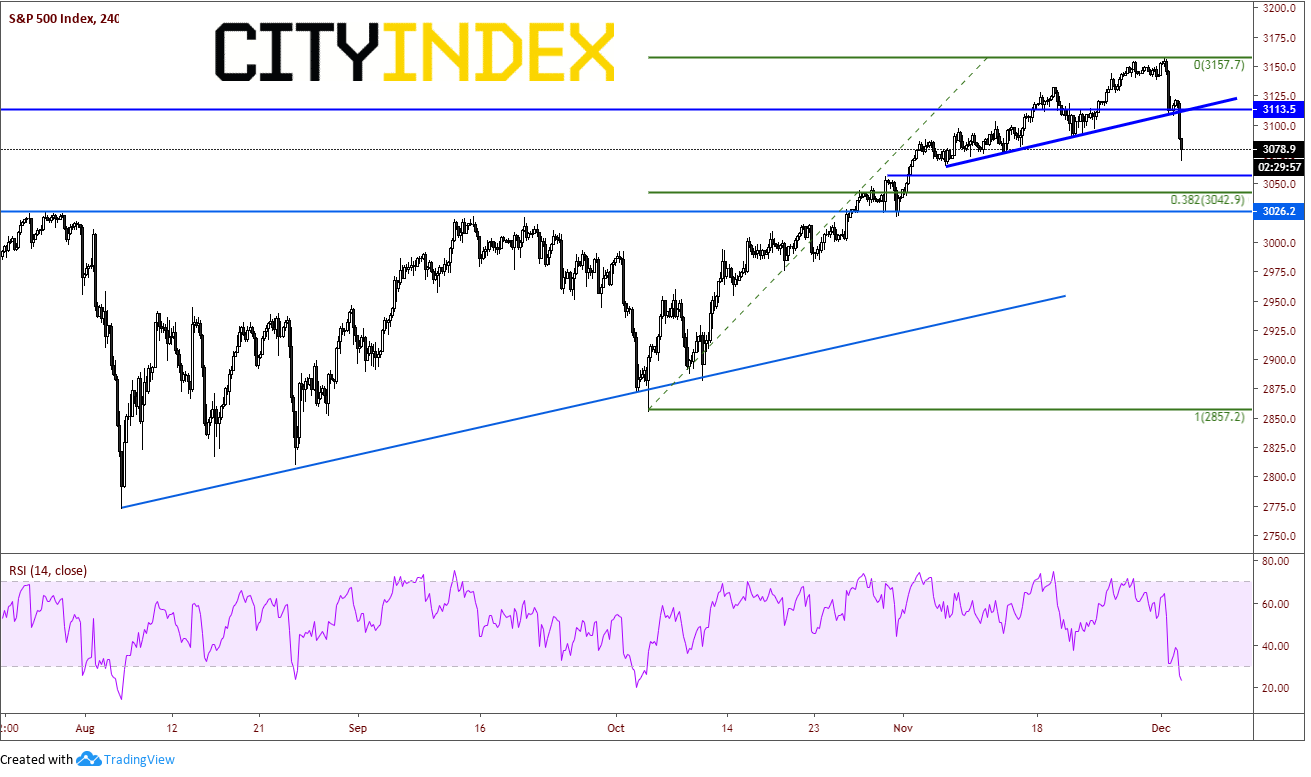
Although the S&P 500 is down nearly 80 handles in two days, price still has room to run down towards 3065, which is the upward sloping trendline dating back to September 2018. There is also horizontal support just below that level near 3060. Psychological resistance now comes across back at 3100, and then horizontal and trendline resistance on the 240-minute timeframe near 3113.
Source: Tradingview, City Index
However, there is one big difference between yesterday and today in terms of market action. Yesterday the DXY participated and sold off. The bond market was relatively muted. Today, the bond market is rallying and the DXY is close to unchanged. Bond prices and yields are inversely related, so as bond prices go bid, yields move lower. US 10 Year Yields are down nearly -5.7% at 1.72. This is the third time yields have tested this level, as it is the 50% retracement level from the lows on October 8th to the highs on November 7th. If bonds continue to rally, yields will continue to fall. The next level of support for yields is the 61.8% Fibonacci retracement level of the previously mentioned timeframe at 1.684.
Source: Tradingview, City Index
As the markets are currently in risk off mode, watch for comments and headlines to try and soften the blow of the tariffs and the possible US-China trade deal delay. With the markets down about 2% in two days, support levels may hold as the market takes a breather ahead of ADP payrolls tomorrow and NFP on Friday.
Yesterday, US President Trump decided enough is enough already. First, he restored tariffs on Argentina and Brazil for aluminum and steel imports to the United States. He cited a “massive devaluation of their currencies”, which in turn hurts American farmers. Later in the day, it was determined after a five-month investigation that a French digital tax discriminated against American Internet companies. As a result, tariffs of up to $2.4 billion on French consumer imports to the United States was proposed. In addition, ISM Manufacturing Data was worse than expected in the United States. Combine these factors together, and most major stock indices were down near 1% yesterday. In addition, the US Dollar Index was also down 0.5%.
Today, President Trump said, “I have no deadline on China deal and it might be better to wait until after November 2020 election”. And later, Commerce Secretary Wilbur Ross said, “December 15th tariffs on Chinese imports will be applied unless there is some real reason to postpone them, such as substantive progress in talks”. Stocks continued to sell off today, with major indices currently down nearly another 1%.
Source: Tradingview, FOREX.com
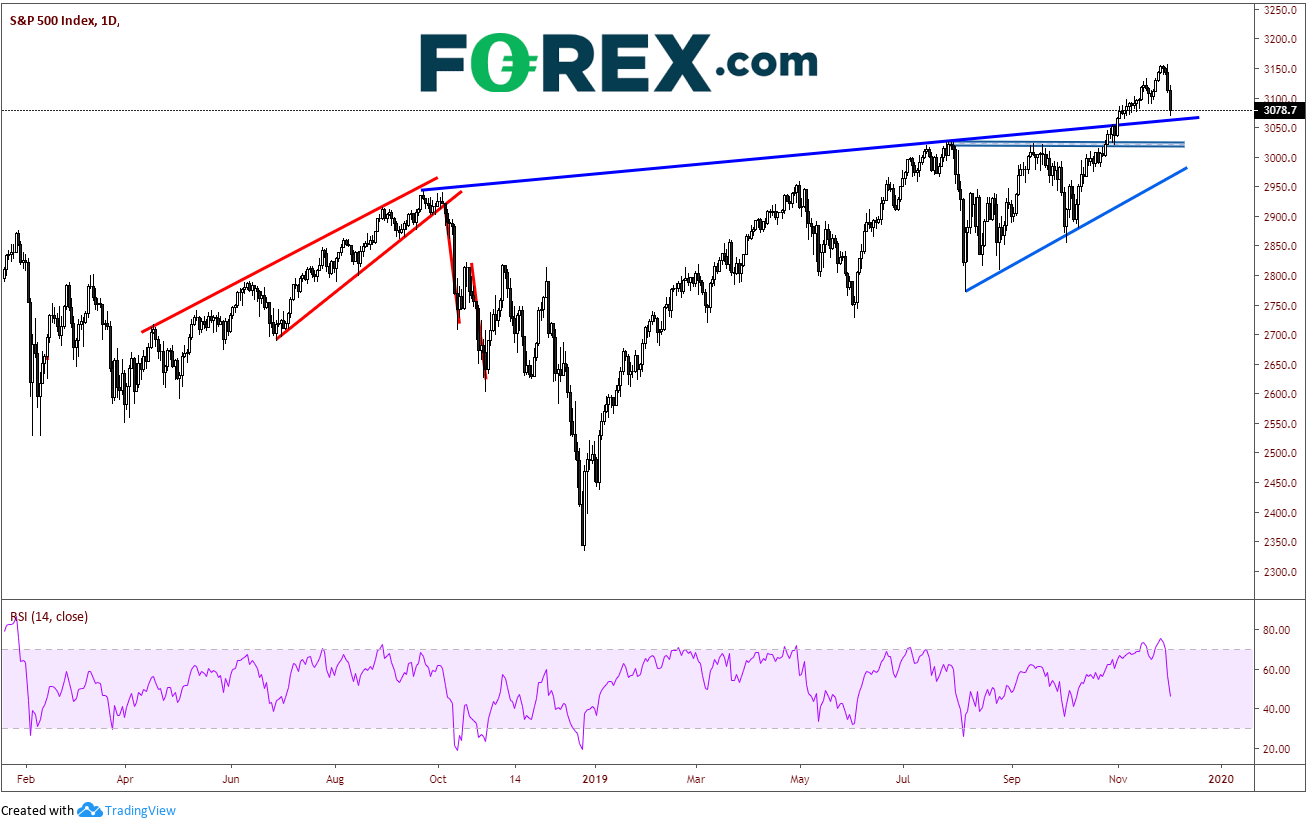
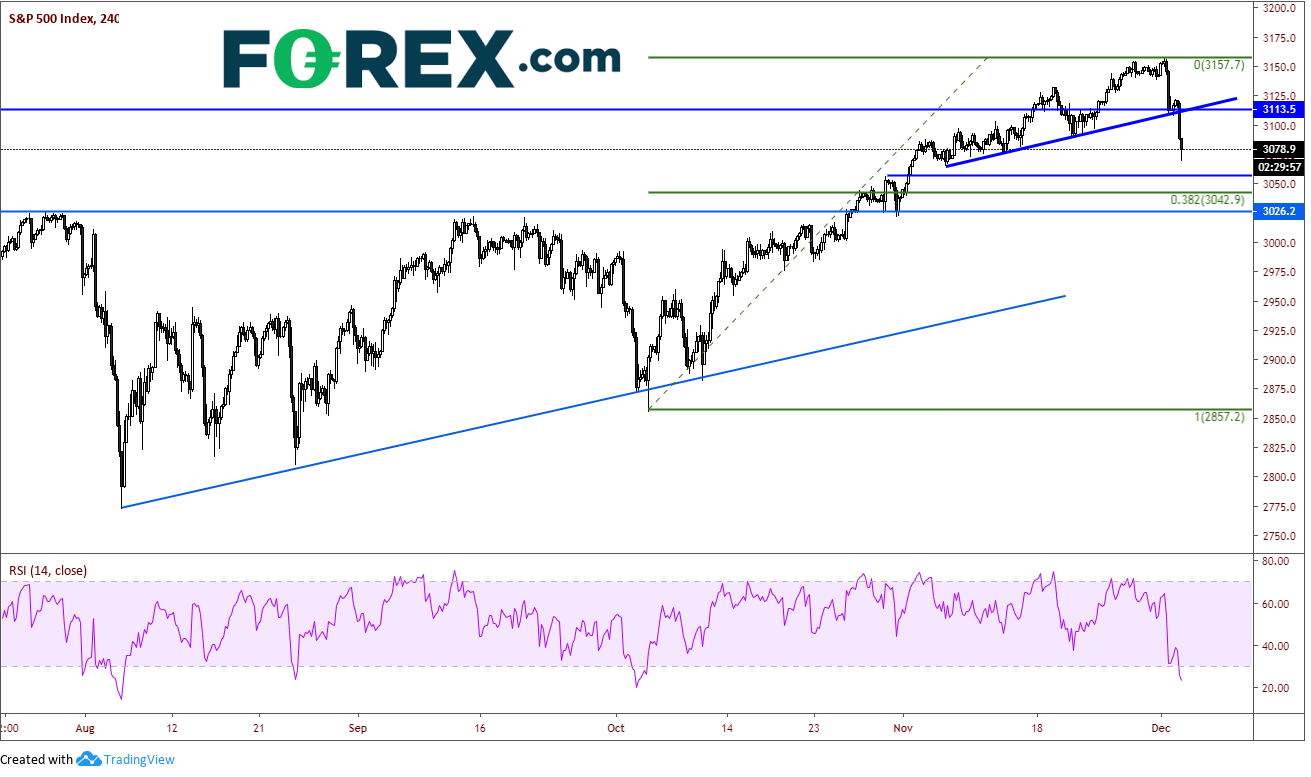
Although the S&P 500 is down nearly 80 handles in two days, price still has room to run down towards 3065, which is the upward sloping trendline dating back to September 2018. There is also horizontal support just below that level near 3060. Psychological resistance now comes across back at 3100, and then horizontal and trendline resistance on the 240-minute timeframe near 3113.
Source: Tradingview, FOREX.com
However, there is one big difference between yesterday and today in terms of market action. Yesterday the DXY participated and sold off. The bond market was relatively muted. Today, the bond market is rallying and the DXY is close to unchanged. Bond prices and yields are inversely related, so as bond prices go bid, yields move lower. US 10 Year Yields are down nearly -5.7% at 1.72. This is the third time yields have tested this level, as it is the 50% retracement level from the lows on October 8th to the highs on November 7th. If bonds continue to rally, yields will continue to fall. The next level of support for yields is the 61.8% Fibonacci retracement level of the previously mentioned timeframe at 1.684.
Source: Tradingview, FOREX.com
As the markets are currently in risk off mode, watch for comments and headlines to try and soften the blow of the tariffs and the possible US-China trade deal delay. With the markets down about 2% in two days, support levels may hold as the market takes a breather ahead of ADP payrolls tomorrow and NFP on Friday.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
AUD/USD Q4 Outlook: RBA and Fed Hikes Set the Tone
AUD/USD enters Q4 with RBA and Fed hikes in focus as sticky inflation, rising unemployment and US dollar strength shape the Australian dollar.

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.


Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.