



US dollar awaits explanation for the Fed's hawkish pivot
Fed pricing is softening. Inflation expectations have fallen sharply. Yet almost half the FOMC still projected at least one rate hike this year in June. This week's Fed communication may finally explain the disconnect and determine where the US dollar heads next.
Share this:
- Fed minutes take centre stage this week
- Waller remains key Fed voice to watch
- Inflation expectations continue moving lower
- Technical signals point to two-way directional risk
Markets rethink Fed outlook
The US dollar enters the week with a slightly different feel. Yes, the broader uptrend remains intact, but softer Fed pricing and fading momentum suggest the next directional move may hinge on what we learn from the Fed over the coming days.
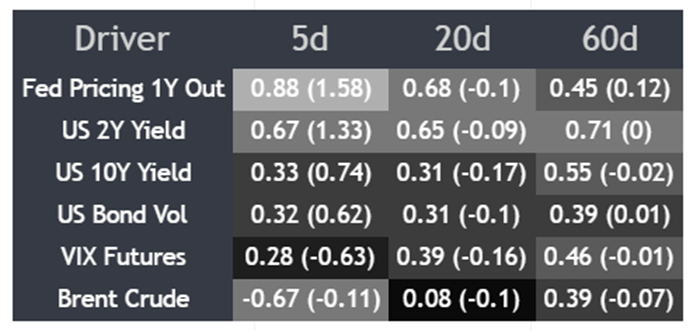
What's noticeable looking at the correlation matrix below is just how strong the relationship has become between the US dollar index and Fed rate expectations, particularly over the past week where the correlation coefficient has risen to 0.88. While not as strong over longer timeframes, the relationship has remained consistently positive. The same can also be seen with US two-year Treasury yields, albeit with slightly lower correlation scores.
It reinforces that expectations for what the Fed may or may not do with interest rates are driving the broader dollar right now.
Source: TradingView
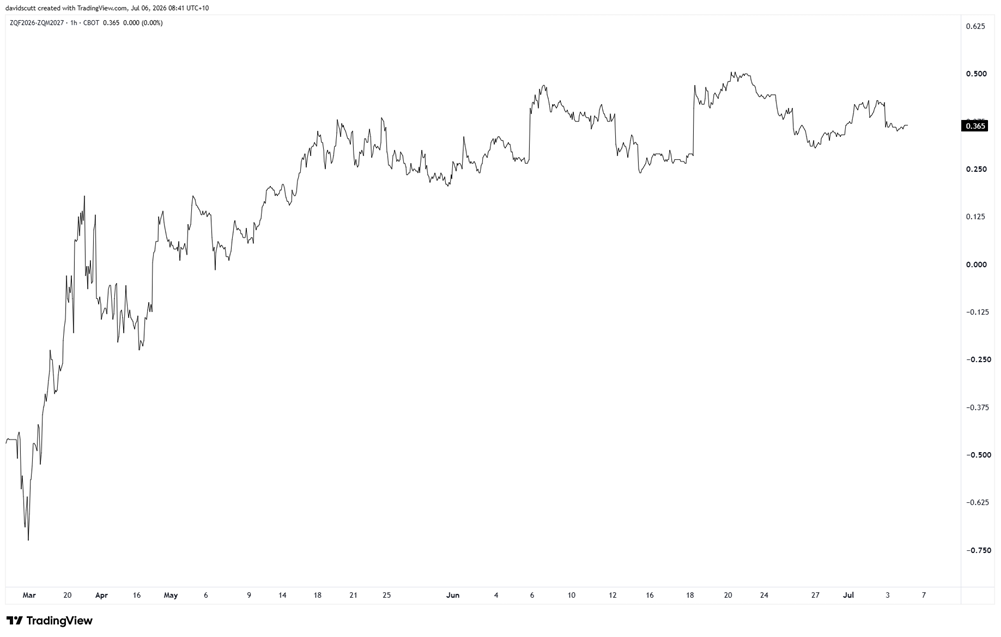
Fed funds futures have steadily pared back the hawkish shift that followed June's FOMC meeting, with markets now pricing around 36.5 basis points of tightening by the June 2027 meeting, down from more than 50 basis points in late June.
The move began after Fed Chair Kevin Warsh's appearance at the ECB Forum in Sintra last week. While reiterating that anyone expecting the Fed to settle for inflation above 2% "will be disappointed", he acknowledged that inflation expectations and inflation risks had eased in recent weeks.
Source: TradingView
Thursday's non-farm payrolls report only reinforced that shift. While the unemployment rate unexpectedly fell to 4.2%, much of the decline reflected a sharp drop in labour force participation. Payrolls growth undershot expectations, prior months were revised lower, the household survey pointed to a sizeable increase in unemployment, and average hourly earnings showed no evidence of a reacceleration in wage pressures that would warrant concerns about second-round inflation effects from this year's energy price shock.
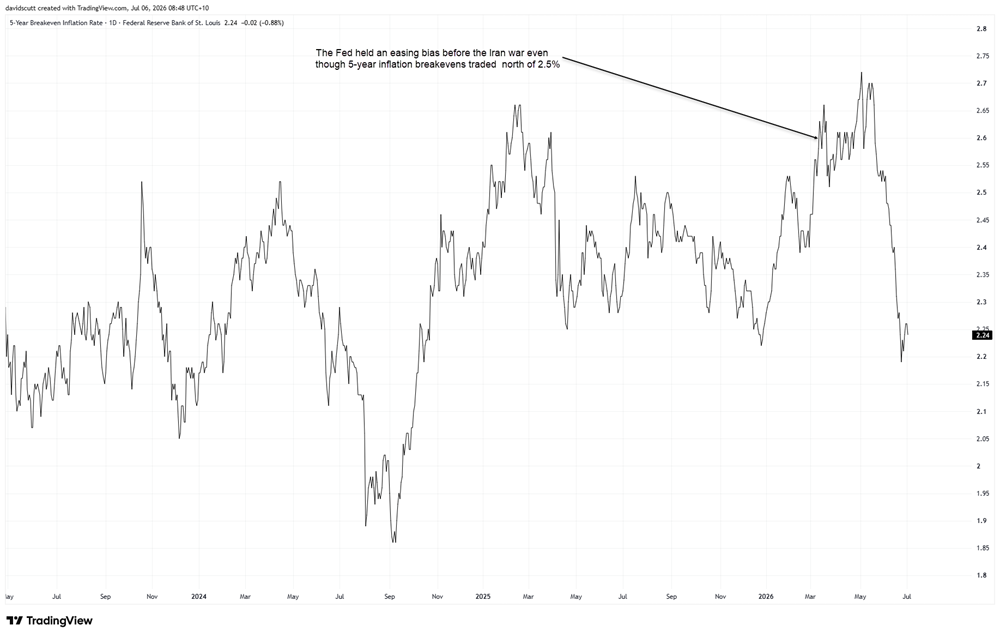
The move in market-based inflation expectations only adds to the puzzle. While the five-year breakeven inflation rate remains above the Fed's 2% target, it briefly slipped below 2.2% late last month and now sits at 2.24%, towards the lower end of the range seen over the past couple of years.
Source: TradingView
To be fair, the June FOMC's hawkish shift will itself have contributed to the decline in breakeven inflation rates. But it's still difficult to reconcile the Committee's projections with the backdrop. Nine of the 18 participants who submitted economic projections at the meeting indicated at least one rate hike before year-end, while six saw multiple increases.
That's despite energy prices retracing sharply and medium-term inflation expectations falling well back from the levels seen immediately after hostilities erupted. It leaves one obvious question: what changed in the space of six weeks?
Searching for answers
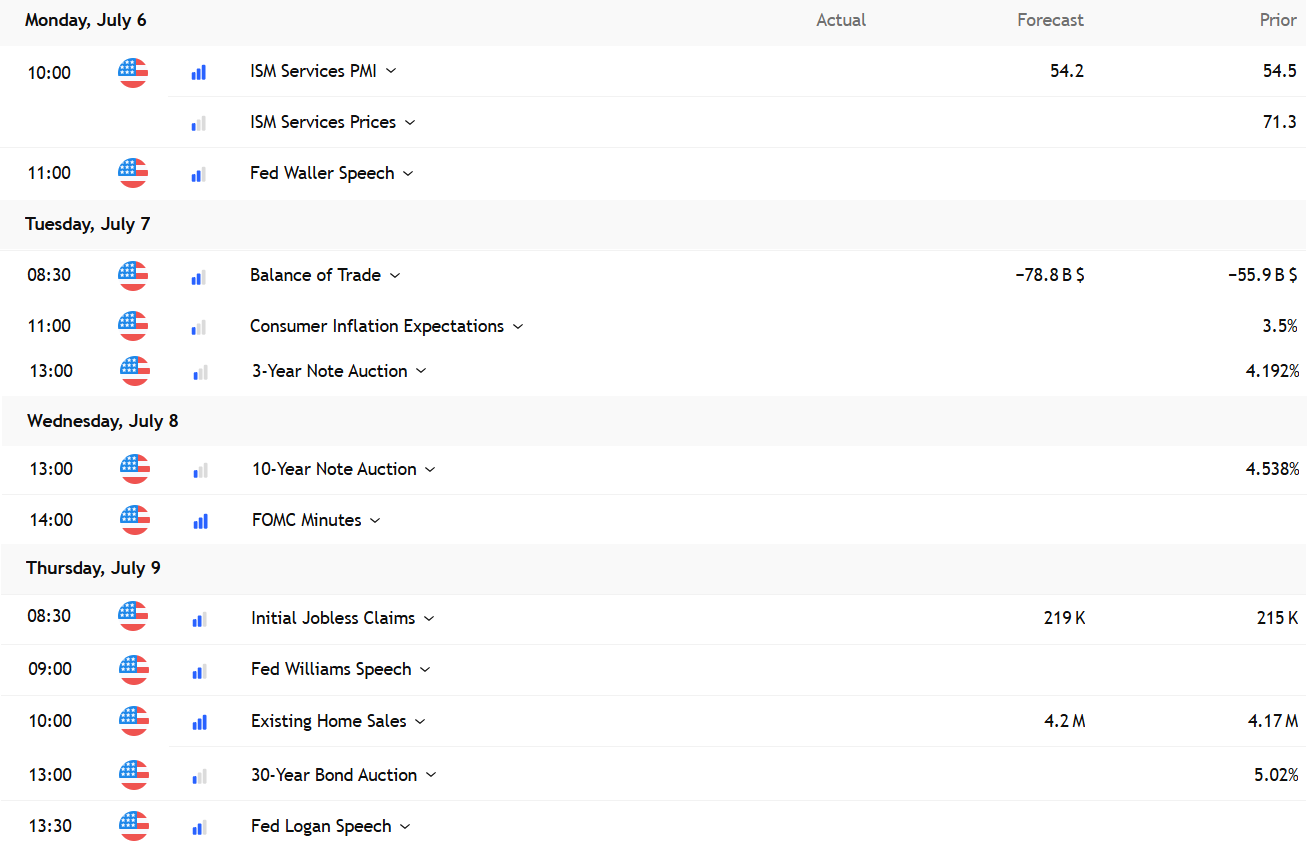
We may get the answer this week. With little in the way of top-tier US data, attention is likely to centre on Wednesday's FOMC minutes along with speeches from Fed Governor Christopher Waller and New York Fed President John Williams.
Source: TradingView (US EDT)
While the minutes may provide greater insight into June's hawkish shift, Waller and Williams are arguably the more interesting events. Both are widely regarded as sitting towards the centre of the Fed's hawk-dove spectrum, making them useful gauges of where the broader Committee is leaning. Waller, in particular, has often proven to be a lead indicator for the direction of travel on the FOMC.
Chair Kevin Warsh has already indicated he has little interest in providing explicit forward guidance, joking at the ECB Forum in Sintra that he wasn't about to "give the markets the answer sheet before the exam".
But will the rest of the committee follow suit? Waller, for example, argued only a few months ago that you'd have to be "crazy" to consider cutting rates. Will he provide another similarly definitive signal? That's what traders should be watching for.
Beyond the Fed, Monday's ISM services PMI is the only data release likely to carry much weight. But don't get too caught up in the headline, though. It's the underlying components that matter most.
After the sharp moderation in the manufacturing prices paid measure last week, traders will be looking to see whether the services equivalent follows suit. A similar outcome would reinforce the recent easing in market-based inflation expectations.
The employment index may also be influential. Payrolls have generally painted a far more resilient picture of the labour market than other indicators this year. The separate household survey has consistently pointed to a much softer backdrop, as have other measures like the Conference Board's labour market differential. If the employment subindex also remains weak, it would reinforce the view that payrolls are increasingly the outlier when it comes to assessing the health of the US labour market.
Elsewhere, the new orders index is another component to look out for. Any further moderation would suggest demand is continuing to cool heading into the second half of the year.
Bullish trend faces a test
Source: TradingView
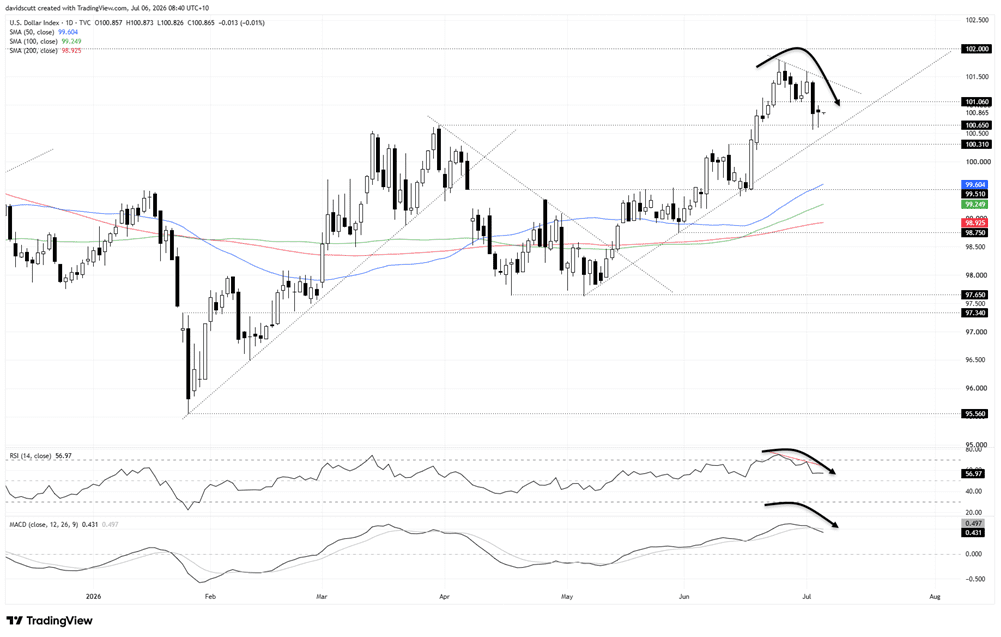
The technical picture for the DXY has deteriorated modestly over the past week, even though it remains in a well-defined uptrend from the May lows and trades above its 50, 100 and 200-day moving averages, all of which remain positively sloped.
However, there are signs the trend is beginning to lose momentum. The index has carved out a short-term downtrend from the June 24 high of 101.80. RSI (14) has also rolled over, setting a lower high, while MACD has crossed over despite remaining in positive territory. None of that is an outright bearish signal, but it is a warning that the strong upside momentum seen over recent months may be starting to shift.
On the downside, 100.65 is the first level to watch. It attracted buyers on two separate occasions late last week and also lines up with the late March high. Along with the uptrend from the May lows, that's the first support zone to keep an eye on. Below there, 100.31 marks the post-FOMC breakout level. A break of both would shift the focus to 99.51, an area that's repeatedly acted as both support and resistance with the 50, 100 and 200-day moving averages also in close proximity.
Overhead, 101.06 is the immediate level to watch, having repeatedly been tagged from below and above over the past fortnight. Above, traders should watch the downtrend from the June high, the recent swing high of 101.80, along with 102.00.
While the dollar’s technical picture has shifted, it’s still difficult to build a convincing bearish case while the broader uptrend remains intact. But the bearish engulfing candle that printed following last week's payrolls report, coupled with fading momentum, suggests the risk-reward is no longer as one-sided as it was only a week ago. As such, for the first time in several months, I'm moving to a more neutral stance on DXY. Respect what price is telling you. Right now, it says the next move is no longer a one-way bet.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Australian Dollar Forecast: AUD/USD Four-Week Slide Nears Critical Uptrend Support 9 29 2026
Aussie momentum has deteriorated sharply into quarter-end, with inflation, Core PCE and NFP on tap as AUD/USD closes in on a pivotal technical threshold.
Canadian Dollar Technical Outlook: USD/CAD Seven-Day Rally Tests Major Resistance 9 29 2026
USD/CAD is pressing into a major technical barrier after an extended advance, raising the risk for price inflection as momentum stretches.

RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.