





US dollar index, USD/CHF look squeezy if traders pare aggressive Fed rate cut bets
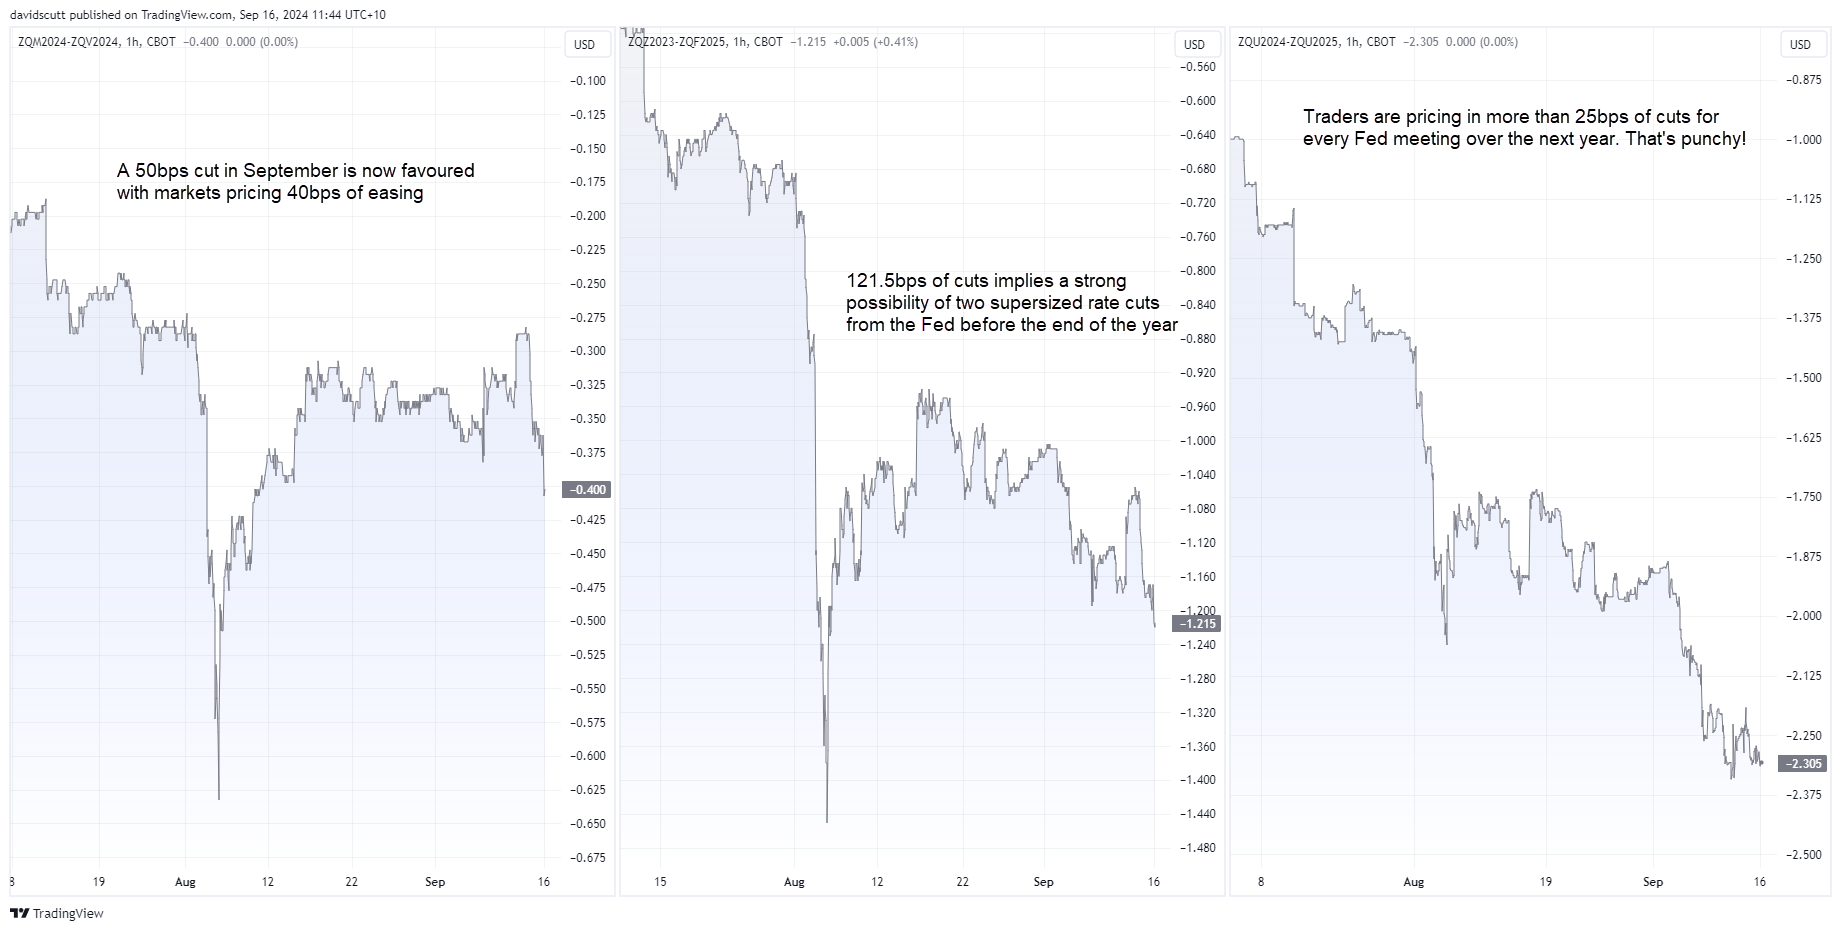
Everyone seems to want to dunk on the US dollar, largely because markets are pricing over 120 basis points of cuts from the Fed by the end of the year. Given how much it’s on the nose, I’m looking for potential squeeze candidates in the FX universe should the Fed disappoint. USD/CHF and US dollar index (DXY) are two that should be on the radar for traders.
Share this:

- Markets price over 120 basis points of rate cuts from the Fed this year
- Fed unlikely to signal rate cuts of this magnitude this week
- DXY, USD/CHF no longer being heavily influenced by US rates markets
- US dollar may strengthen if Fed rate cut bets are pared
Overview
Everyone seems to want to dunk on the US dollar, largely because markets are pricing over 120 basis points of rate cuts from the Fed by the end of the year. Given how much it’s on the nose, I’m looking for potential squeeze candidates in the FX universe should the Fed disappoint on increasingly dovish expectations. USD/CHF and US dollar index (DXY) are two that should be on the radar for traders.
Fed pricing looks too aggressive
As covered in an earlier note, market pricing for Fed rate cuts over the next few meetings has ballooned in recent days thanks to a string of dovish messages from suspected Fed mouthpieces working in the media. A 50 basis point rate cut is now favoured in September with a strong probability of two supersized rate cuts arriving before the end of the year.
Each to their own, but I just don’t see the Fed going down that path unless there’s evidence the US is entering recession, pointing to the potential its revised rate cut profile may not be anywhere near as aggressive as markets expect. If that is the case, we could see a violent upward adjustment at the front of the US yield curve, potentially dragging the US dollar along for the ride.
DXY, USD/CHF stop following US yields lower
The next chart looks at the rolling 20-day correlation between a variety of US interest rate markets with USD/JPY in the left-hand pane, the DXY in the middle pane, along with USD/CHF in the right pane.
From to bottom, the variables presented are 2024 Fed rate cut pricing, year ahead Fed rate cut pricing, US two year yields, US five-year yields, US 10-year yields and US 30-year yields.
Based on strength of correlations, USD/JPY is a prime squeeze candidate with score of around 0.9 or higher across all variables. If you want to read up specifically about USD/JPY, I’d encourage you to look at the note I put out earlier detailing key events and levels.
However, while USD/JPY remains heavily influenced by US interest rate markets, the DXY and USD/CHF are not, a big departure from what was seen over much of July and August. What were very strong positive correlations have turned to mush.
Now, this could mean if we see rate cut bets pared this week, neither DXY nor USD/CHF will care. However, my reading of the abrupt weakening is that rates markets may have gone too far in what’s been priced, with FX traders unwilling to add to dollar shorts after what’s already been a significant move.
I suspect that if and when rates markets strip out some of the Fed easing that's been priced, DXY and USD/CHF could squeeze higher, potentially aggressively.
DXY not threatening cyclical lows
DXY has yet to print fresh lows despite the dovish tilt in Fed pricing, remaining in the relative narrow range between 101.768 and 100.52 it’s been stuck in since the middle of August. With RSI (14) trending higher and MACD doing the same, bearish momentum is waning, pointing to shifting directional risks for price.
If we were to see a clean break above 101.768, it could likely bring a retest of the downtrend running from early July. And if that level were breached, the 50-day moving average and resistance at 103.65 may come into play. On the downside, a break and close below 100.52 may see DXY retest 99.60, the double bottom hit in July last year.
USD/CHF: momentum turning?
Turning to USD/CHF, the rejection at the intersection of downtrend and horizontal resistance last week has seen the pair move back to the centre of its recent range between .85414 and .8402. However, with bullish divergence between RSI (14) and price, and with MACD continuing to trend higher, bearish momentum continues to weaken, pointing to an increased risk that price may soon follow. The long downside wicks on the daily candles over the past week further strengthen this view.
If the price were able to break the downtrend, .85414, .86171, the 50-day moving average and .87287 are topside levels of note. If the price were to decline and close below .8402, .8333 would be eyed by bears.
-- Written by David Scutt
Follow David on Twitter @scutty
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.

Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.

EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.