



US open: Stocks slide ahead of big tech earnings
US stocks are heading lower after 2 days of strong gains. Earnings ramp up and all eyes turn to big tech ahead of the Microsoft & Alphabets's earnings after the close.
Share this:

US futures
Dow futures -0.62% at 31313
S&P futures -0.26% at 3777
Nasdaq futures -0.23% at 11400
In Europe
FTSE -1% at 6950
Dax -1.2% at 12782
US consumer confidence data due
After two days of solid gains, US stocks are heading lower on Tuesday as investors digest the latest batch of earnings and as they look ahead to big tech earnings which kick off after the close today.
Stocks rose yesterday after a fourth straight monthly decline in business activity, which fueled hopes that the Fed’s aggressive hikes to cool the economy was taking effect. This, in turn raised hopes that the Fed could soon start to ease back on the pace of rate hikes.
Looking ahead, US consumer confidence data is due later and is expected to show that morale fell again in October to 106.5, down from 108 in September.
All eyes will then turn to the start of big tech earnings, with Microsoft and Alphabet set to be under the spotlight. Big tech is often looking at for clues surrounding the broader economy, such as the health of the consumer.
If SNAP was the canary in the coal mine, investors may be worried about the impact that inflation is having on advertising revenue growth. Advertising spending is usually one of the first areas to see cuts when recession fears rise.
Meanwhile, Microsoft is expected to post the slowest revenue growth in over five years.
Corporate news:
UPS is rising 3.5% pre-market after reporting a rise in Q3 adjusted profit. Higher delivery prices helped to offset weakening e-commerce demand.
General Motors rallied 4.7% pre-market after the automaker reported a stronger-than-expected quarterly profit and reiterated its full-year outlook.
Where next for the S&P500?
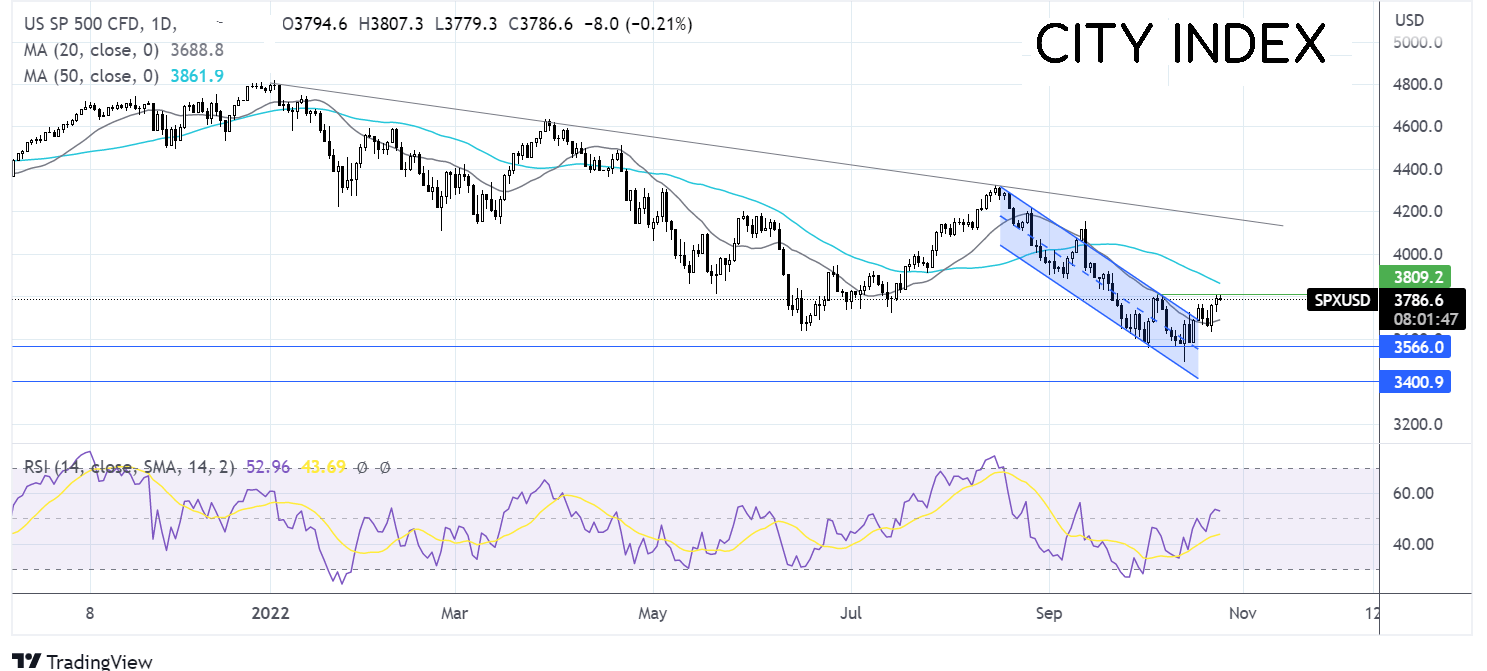
The S&P has extended its recovery from the 2022 low, out of the multi-week falling channel and above the 20 sma, but has stalled around the 3800 level. The RSI above 50 keeps buyers hopeful of further upside. A rise over 3800 exposes the 50 sma at 3860, before brining 3900 round number into play. Should sellers successfully defend 3800, the price could fall to 369 the 20 sma, before re-entering the falling channel.

FX markets – USD rises, GBP rises
The USD is rising after three days of declines amid softening expectations for Fed rate hikes. Following the report in the WSJ, plus comments from San Francisco Fed President Mary Daly, which fuelled bets of a dovish pivot, investors sold out of the greenback. Today yields on the 10-year treasury are edging lower again but remain over 4%.
EUR/USD is falling after German IFO business sentiment remained gloomy in October, dipping to 84.3, down from 84.4. The IFO President said that the German economy facing a difficult winter. The data painted a similar picture to that of the PMI yesterday.
GBPUSD is rising as Rishi Sunak becomes next Prime Minister. The former Chancellor has a mammoth task ahead of him as he tackles the mounting economic crisis facing the UK and his warring political party. In his first speech he said that economic stability and confidence is at the heart of his agenda. So far the markets have stabilised, trusting in the fiscally prudent leaders. Gilt yields have fallen.
GBP/USD +0.4% at 1.1320
EUR/USD -0.14% at 0.9860
Oil falls ahead of inventory data
Oil prices are falling for a second straight day as fears over slowing economic growth hurt the demand outlook. Disappointing PMI data across the board raised concerns of a recession.
With supply and demand fundamentals holding steady for now, economic sentiment is the driving force. Much of the deteriorating economic outlook has likely been priced in so prices could find a floor around these levels.
Looking ahead, oil inventory data is due later and is expected to rise by 200,000 barrels in the week to 21st October. High levels of inventory could drag the price lower.
WTI crude trades +1.4% at $83.90
Brent trades +1.03% at $90.70
Looking ahead
21:30 API oil stockpile data
US futures
Dow futures -0.62% at 31313
S&P futures -0.26% at 3777
Nasdaq futures -0.23% at 11400
In Europe
FTSE -1% at 6950
Dax -1.2% at 12782
Learn more about trading indices
US consumer confidence data due
After two days of solid gains, US stocks are heading lower on Tuesday as investors digest the latest batch of earnings and as they look ahead to big tech earnings which kick off after the close today.
Stocks rose yesterday after a fourth straight monthly decline in business activity, which fueled hopes that the Fed’s aggressive hikes to cool the economy was taking effect. This, in turn raised hopes that the Fed could soon start to ease back on the pace of rate hikes.
Looking ahead, US consumer confidence data is due later and is expected to show that morale fell again in October to 106.5, down from 108 in September.
All eyes will then turn to the start of big tech earnings, with Microsoft and Alphabet set to be under the spotlight. Big tech is often looking at for clues surrounding the broader economy, such as the health of the consumer.
If SNAP was the canary in the coal mine, investors may be worried about the impact that inflation is having on advertising revenue growth. Advertising spending is usually one of the first areas to see cuts when recession fears rise.
Meanwhile, Microsoft is expected to post the slowest revenue growth in over five years.
Corporate news:
UPS is rising 3.5% pre-market after reporting a rise in Q3 adjusted profit. Higher delivery prices helped to offset weakening e-commerce demand.
General Motors rallied 4.7% pre-market after the automaker reported a stronger-than-expected quarterly profit and reiterated its full-year outlook.
Where next for the S&P500?
The S&P has extended its recovery from the 2022 low, out of the multi-week falling channel and above the 20 sma, but has stalled around the 3800 level. The RSI above 50 keeps buyers hopeful of further upside. A rise over 3800 exposes the 50 sma at 3860, before brining 3900 round number into play. Should sellers successfully defend 3800, the price could fall to 369 the 20 sma, before re-entering the falling channel.
FX markets – USD rises, GBP rises
The USD is rising after three days of declines amid softening expectations for Fed rate hikes. Following the report in the WSJ, plus comments from San Francisco Fed President Mary Daly, which fuelled bets of a dovish pivot, investors sold out of the greenback. Today yields on the 10-year treasury are edging lower again but remain over 4%.
EUR/USD is falling after German IFO business sentiment remained gloomy in October, dipping to 84.3, down from 84.4. The IFO President said that the German economy facing a difficult winter. The data painted a similar picture to that of the PMI yesterday.
GBPUSD is rising as Rishi Sunak becomes next Prime Minister. The former Chancellor has a mammoth task ahead of him as he tackles the mounting economic crisis facing the UK and his warring political party. In his first speech he said that economic stability and confidence is at the heart of his agenda. So far the markets have stabilised, trusting in the fiscally prudent leaders. Gilt yields have fallen.
GBP/USD +0.4% at 1.1320
EUR/USD -0.14% at 0.9860
Oil falls ahead of inventory data
Oil prices are falling for a second straight day as fears over slowing economic growth hurt the demand outlook. Disappointing PMI data across the board raised concerns of a recession.
With supply and demand fundamentals holding steady for now, economic sentiment is the driving force. Much of the deteriorating economic outlook has likely been priced in so prices could find a floor around these levels.
Looking ahead, oil inventory data is due later and is expected to rise by 200,000 barrels in the week to 21st October. High levels of inventory could drag the price lower.
WTI crude trades +1.4% at $83.90
Brent trades +1.03% at $90.70
Learn more about trading oil here.
Looking ahead
21:30 API oil stockpile data
Related tags:




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

AUD/USD outlook: Aussie slips despite hawkish RBA ahead of key data
The AUD/USD was unable to benefit from the Reserve Bank of Australia’s 25-basis-point rate hike overnight. The RBA lifted the cash rate to 4.60%, in line with expectations. However, the Australian dollar weakened following the decision, with much of the Bank’s hawkish stance seemingly priced in ahead of the announcement. The US dollar has also remained largely supported following the recent turmoil in the bond markets.


RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.

Gold outlook: XAU/USD hammered, stretched and vulnerable to a sharp rebound
Gold is getting hammered for solid fundamental reasons, but history suggests extreme four-hourly oversold conditions can produce violent countertrend rallies.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.