



US open: Stocks tumble as inflation unexpectedly rises
Stocks are set for a steeply lower start after the keenly awaited CPI data showed that inflation unexpectedly rose in May to 8.6% YoY a fresh 40 year high.
Share this:

US futures
Dow futures -0.8% at 32000
S&P futures -1% at 3979
Nasdaq futures -1.23% at 12113
In Europe
FTSE -1.736% at 7385
Dax -1.1% at 14036
Euro Stoxx -1.4% at 3640
CPI rises, core CPI falls less than expected
After steep losses in yesterday, stocks are in freefall today after inflation unexpectedly rose in May. CPI came in at 8.6% YoY, up from 8.3% in April and defying expectations of 8.3%. Core inflation fell to 6% from 6.2% but was still above forecasts of 5.9%.
Following the data, stocks, particularly tech stocks tanked lower and the USD moved higher. The market movements suggest that investors expect the Fed to act more aggressively to bring inflation down.
This was not the result that the market was looking for and the idea of passing peak inflation remains elusive for another month. It is looking like inflation will remain steady around these elevated levels before we start to see any significant fall. Given the high that commodity prices, particularly in the energy complex, continue to rise, perhaps this isn’t that unsurprising.
The data comes after indices sold off sharply yesterday after the ECB signaled that it will start hiking interest rates next month with 25 basis points but could raise rates by 50 basis points in September. The RBA surprised the market with a 50-basis point hike earlier in the week. Central banks are prepared to act aggressively to rein in inflation.
The Michigan consumer confidence data is also scheduled for later today and will provide insight into how the consumer is holding up as inflation remains stubbornly high. Signs that the consumer is struggling could unnerve the markets.
In corporate news:
DocuSign falls 25% pre-market to a 32-month low after missing quarterly earnings expectations and lowering its outlook. The firm had previously warned that the return to pre-COVID working conditions could cut its business.
Where next for the S&P?
The S&P 500 has broken out of its recent range. The price broke below support at 4070, the weekly low and the 20 sma, which combined with the RSI heading lower suggest that there could be more downside to come. A break-through support at 4000 the psychological level could lead to a deeper selloff towards 3865 the May 12 low and 3810 the 2022 low. It would take a move over 4190/4200 the June high 50 sma to create a higher high and rise towards 4300 the May high.

FX markets – USD rises, EUR falls
USD is climbing higher following the hotter than expected inflation data. The data fueled bets that the Fed could go harder and faster on raising rates.
EUR/USD is extending losses after yesterday’s ECB rate announcement. The central bank slashed the bloc’s growth outlook and raised its inflation forecast. Today the Bundesbank cut Germany’s GDP outlook and raised its inflation forecast. There are growing concerns over fragmentation within the region.
GBP/USD is falling for a third straight session amid growing concerns of rising inflation and slowing growth. The BoE/Ipsos latest quarterly survey revealed that the public sees inflation rising to 4.6% over the next 12 months, up from 4.3% expected in February’s survey. The pound was unimpressed by PM Boris Johnson’s comments that he will cut taxes sooner rather than later to help households struggling in the cost of living crisis.
GBP/USD -0.4% at 1.2440
EUR/USD -0.27% at 1.0595
Oil set for 7th weekly gain
Oil prices are on the rise, with Brent looking at a fourth straight week of gain whilst WTI crude oil is set for the seventh straight week of gains. The black stuff has rallied over 20% since mid-April, taking the price to three-month highs on tight supply and rising US demand, which is overshadowing COVID concerns ion China.
The peak summer driving season in the UK has seen gasoline stockpiles fall by more than expected and petrol prices reach $5 a gallon.
In addition to the usual Russia, tight supply story, concerns of reduced supply in Norway were also lifting the price. Workers at Norwegian Oil & Gas Association were threatening to go on strike in pay negotiations fail.
Oil prices had started the day around $1 lower after fresh lockdown restrictions in Shanghai owing to more COVID. China’s crude oil imports were up some 12% yoy, but this was when they were already low.
WTI crude trades +0.7% at $120.34
Brent trades +0.7% at $122.9
Looking ahead
18:00 Baker Hughes rig count
US futures
Dow futures -0.8% at 32000
S&P futures -1% at 3979
Nasdaq futures -1.23% at 12113
In Europe
FTSE -1.736% at 7385
Dax -1.1% at 14036
Euro Stoxx -1.4% at 3640
Learn more about trading indices
CPI rises, core CPI falls less than expected
After steep losses in yesterday, stocks are in freefall today after inflation unexpectedly rose in May. CPI came in at 8.6% YoY, up from 8.3% in April and defying expectations of 8.3%. Core inflation fell to 6% from 6.2% but was still above forecasts of 5.9%.
Following the data, stocks, particularly tech stocks tanked lower and the USD moved higher. The market movements suggest that investors expect the Fed to act more aggressively to bring inflation down.
This was not the result that the market was looking for and the idea of passing peak inflation remains elusive for another month. It is looking like inflation will remain steady around these elevated levels before we start to see any significant fall. Given the high that commodity prices, particularly in the energy complex, continue to rise, perhaps this isn’t that unsurprising.
The data comes after indices sold off sharply yesterday after the ECB signaled that it will start hiking interest rates next month with 25 basis points but could raise rates by 50 basis points in September. The RBA surprised the market with a 50-basis point hike earlier in the week. Central banks are prepared to act aggressively to rein in inflation.
The Michigan consumer confidence data is also scheduled for later today and will provide insight into how the consumer is holding up as inflation remains stubbornly high. Signs that the consumer is struggling could unnerve the markets.
In corporate news:
DocuSign falls 25% pre-market to a 32-month low after missing quarterly earnings expectations and lowering its outlook. The firm had previously warned that the return to pre-COVID working conditions could cut its business.
Read more about stocks to watch
Where next for the S&P?
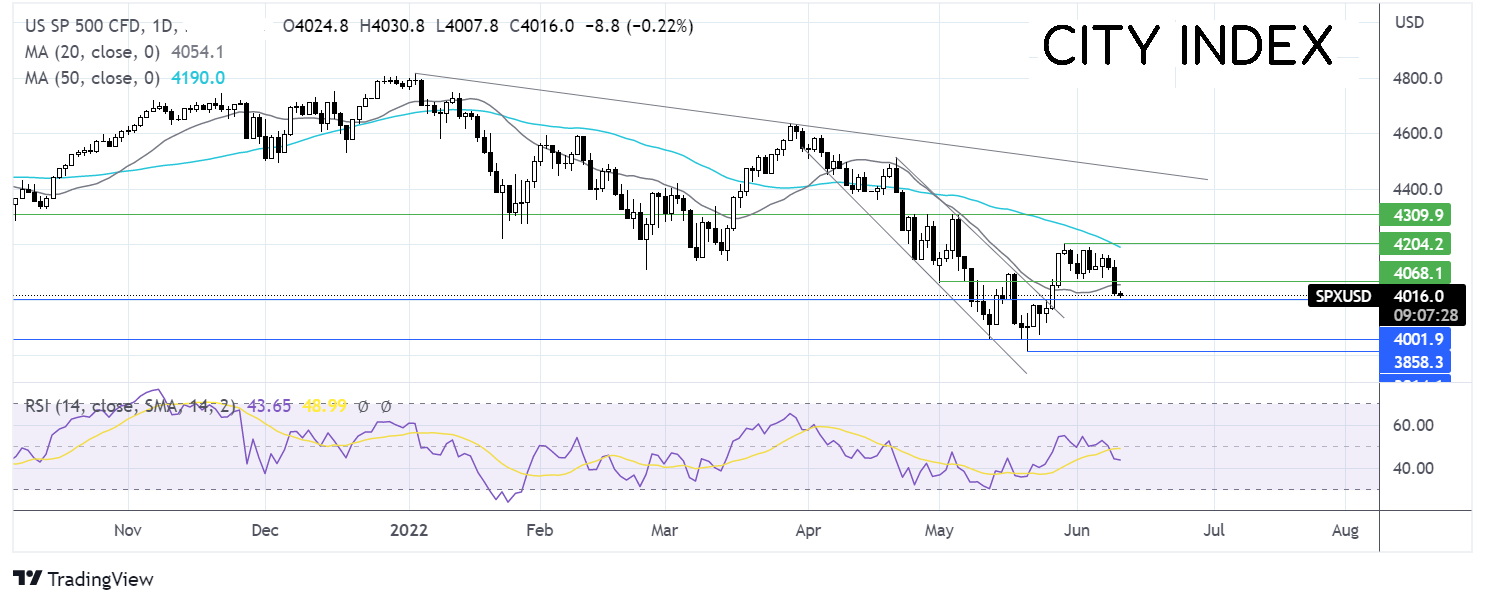
The S&P 500 has broken out of its recent range. The price broke below support at 4070, the weekly low and the 20 sma, which combined with the RSI heading lower suggest that there could be more downside to come. A break-through support at 4000 the psychological level could lead to a deeper selloff towards 3865 the May 12 low and 3810 the 2022 low. It would take a move over 4190/4200 the June high 50 sma to create a higher high and rise towards 4300 the May high.
FX markets – USD rises, EUR falls
USD is climbing higher following the hotter than expected inflation data. The data fueled bets that the Fed could go harder and faster on raising rates.
EUR/USD is extending losses after yesterday’s ECB rate announcement. The central bank slashed the bloc’s growth outlook and raised its inflation forecast. Today the Bundesbank cut Germany’s GDP outlook and raised its inflation forecast. There are growing concerns over fragmentation within the region.
GBP/USD is falling for a third straight session amid growing concerns of rising inflation and slowing growth. The BoE/Ipsos latest quarterly survey revealed that the public sees inflation rising to 4.6% over the next 12 months, up from 4.3% expected in February’s survey. The pound was unimpressed by PM Boris Johnson’s comments that he will cut taxes sooner rather than later to help households struggling in the cost of living crisis.
GBP/USD -0.4% at 1.2440
EUR/USD -0.27% at 1.0595
Oil set for 7th weekly gain
Oil prices are on the rise, with Brent looking at a fourth straight week of gain whilst WTI crude oil is set for the seventh straight week of gains. The black stuff has rallied over 20% since mid-April, taking the price to three-month highs on tight supply and rising US demand, which is overshadowing COVID concerns ion China.
The peak summer driving season in the UK has seen gasoline stockpiles fall by more than expected and petrol prices reach $5 a gallon.
In addition to the usual Russia, tight supply story, concerns of reduced supply in Norway were also lifting the price. Workers at Norwegian Oil & Gas Association were threatening to go on strike in pay negotiations fail.
Oil prices had started the day around $1 lower after fresh lockdown restrictions in Shanghai owing to more COVID. China’s crude oil imports were up some 12% yoy, but this was when they were already low.
WTI crude trades +0.7% at $120.34
Brent trades +0.7% at $122.9
Learn more about trading oil here.
Looking ahead
18:00 Baker Hughes rig count
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Wall Street Split Widens Into Month-End 9 26 2026
Nasdaq strength contrasts with mounting Dow pressure as rising Treasury yields raise the stakes for stocks heading into the monthly close.
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.

Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.