




US open tech slips after yesterdays gains
The tech heavy Nasdaq is easing lower after recording 1% gains on Thursday. Rising bond yields are adding pressure to high growth tech stocks, whilst lifting the Dow Jones.
Share this:

US futures
Dow futures +0.2% at 33450
S&P futures +0.02% at 4090
Nasdaq futures -0.3% at 13721
In Europe
FTSE -0.2% at 6922
Dax +0.1% at 15208
Euro Stoxx +0.03% at 3981
Learn more about trading indices
Tech stocks ease lower as yields pick up
US futures are heading for a mixed open on Friday, with tech heavy Nasdaq set to under-perform after booking 1% gains in the previous session.
All three major indices closed higher in the previous session supported by a dovish US central bank. Fed Chair Powell echoed the accommodative tone of the FOMC minutes, released on Wednesday, lifting the S&P to a fresh record high.
Today treasury yields are once again climbing higher, with the benchmark 10 year treasury yield +2.3% at 1.67, which is slightly impacting demand for tech growth stocks.
Despite today's rise, the Nasdaq has outperformed its peers across the week after disappointing jobless claims, and dovish calls from the Fed's nest. The Fed has been clear that it needs to see a prolonged period of strong data to tighten policy. The recovery will be uneven and data this week has coincided with that.
S&P chart
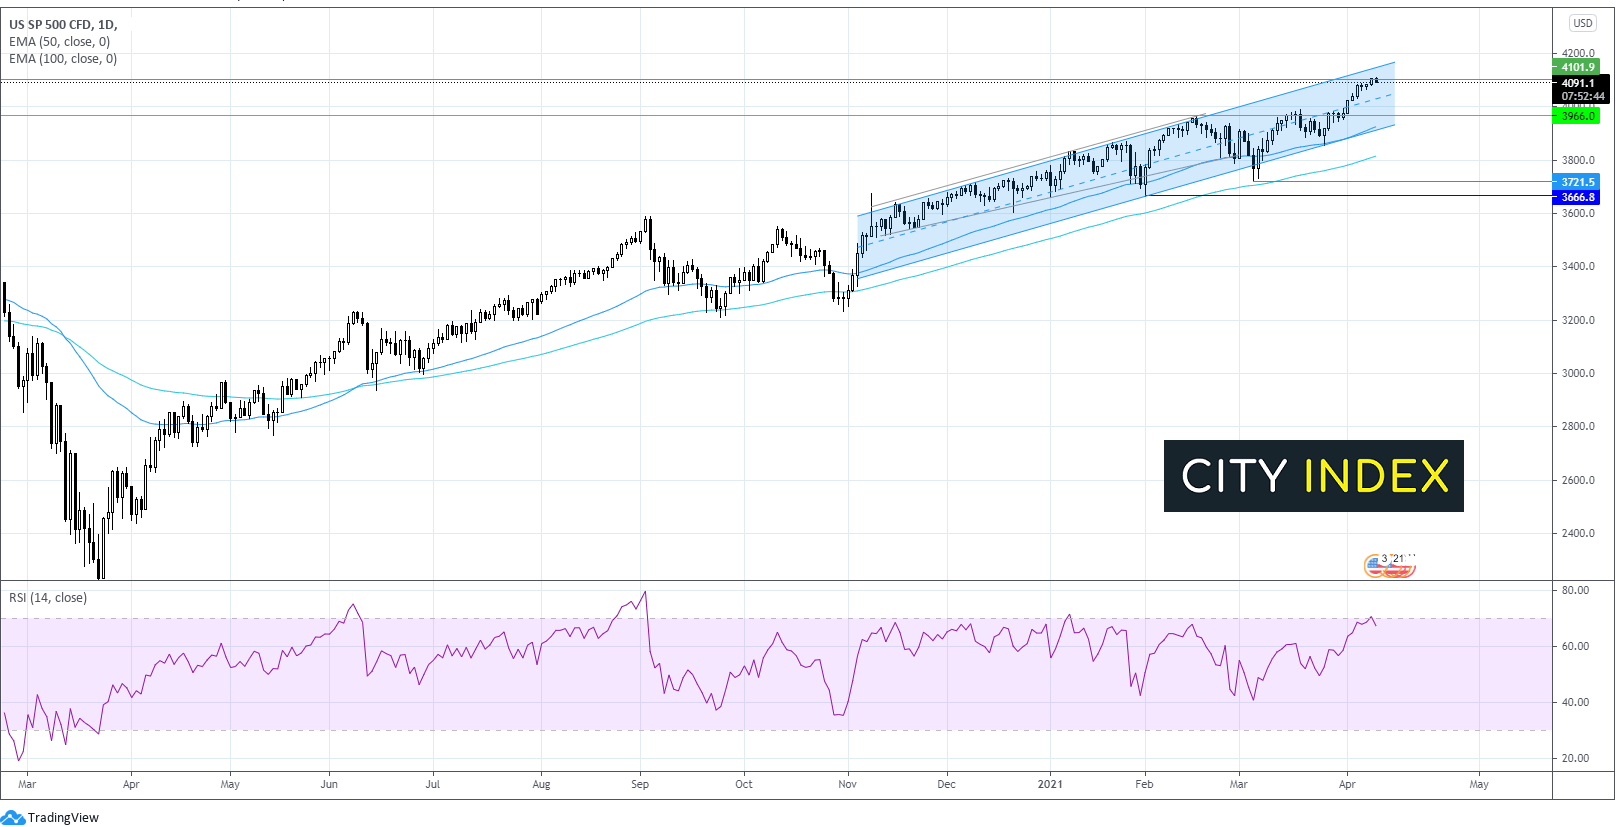
The S&P is easing back after hitting an all time high of 4111 in the previous session. The index remains at the top end of the ascending channel. However with the RSI reaching into over bought territory a pull back or at least some consolidation was on the cards. The trend remains bullish. It would take a move below support at 3980 to negate the current bull trend.
Inflation data
US PPI data is due shortly and is expected to show 0.5% MoM in-line with last month. On an annual basis PPI is forecast to increase 3.8% in March up from 2.8%.
The Fed has repeatedly said that it is willing to look through a rise in inflation, which it expects to be temporary.
Chinese PPI rose 4.4% YoY in the fastest increase since July 2018 and significantly ahead of February’s 1.7%. Expectations had been for 3.5% increase.
FX – EUR outperforms, GBP has worst week this year
The US Dollar on the rise tracing US treasury yields higher. However, the DXY is on track for its worst weekly performance since mid-December.
GBP/USD – The Pound has under-performed despite strong fundamentals. After particularly impressive gains in the first quarter investors are taking profits off the table. GBP/USD trades -0.8% this week.
Meanwhile the Euro has outperformed across the week, up 1% since Monday, on expectations that the sluggish vaccine rollout in the region will start to pick up quickly. The major economies in Europe such as Germany, Spain, France and Italy expect to vaccinate 70% of the population by the end of June.
GBP/USD -0.1% at 1.3715
EUR/USD trades -0.2% at 1.1881
Oil trades sideways with output compliance in focus
Crude oil prices continue to trade sideways after a steep drop at the start of the week as investors continue to weigh up the prospect of additional supply from OPEC as from next month against a weaker demand outlook as covid cases rise.
Concerns over compliance with OPEC output curbs are also surfacing after an S&P report pointed to oversupply by OPEC+ members to the tune of 450,000 barrels per day in March with Russia and Iraq the worst offenders.
US crude trades -0.4% at $59.45
Brent trades -0.5% at $62.71
Learn more about trading oil here.
The complete guide to trading oil markets
Looking ahead
13:30 US PPI
13:30 Canadian jobs report
18:00 Baker Hughes oil rig count
US futures
Dow futures +0.2% at 33450
S&P futures +0.02% at 4090
Nasdaq futures -0.3% at 13721
In Europe
FTSE -0.2% at 6922
Dax +0.1% at 15208
Euro Stoxx +0.03% at 3981
Learn more about trading indices
Tech stocks ease lower as yields pick up
US futures are heading for a mixed open on Friday, with tech heavy Nasdaq set to under-perform after booking 1% gains in the previous session.
All three major indices closed higher in the previous session supported by a dovish US central bank. Fed Chair Powell echoed the accommodative tone of the FOMC minutes, released on Wednesday, lifting the S&P to a fresh record high.
Today treasury yields are once again climbing higher, with the benchmark 10 year treasury yield +2.3% at 1.67, which is slightly impacting demand for tech growth stocks.
Despite today's rise, the Nasdaq has outperformed its peers across the week after disappointing jobless claims, and dovish calls from the Fed's nest. The Fed has been clear that it needs to see a prolonged period of strong data to tighten policy. The recovery will be uneven and data this week has coincided with that.
S&P 500 Chart
The S&P is easing back after hitting an all time high of 4111 in the previous session. The index remains at the top end of the ascending channel. However with the RSI reaching into over bought territory a pull back or at least some consolidation was on the cards. S&P trades -0.2% at the time of writing. The trend remains bullish. It would take a move below support at 3980 to negate the current up trend trend.
Inflation data
US PPI data is due shortly and is expected to show 0.5% MoM in-line with last month. On an annual basis PPI is forecast to increase 3.8% in March up from 2.8%.
The Fed has repeatedly said that it is willing to look through a rise in inflation, which it expects to be temporary.
Chinese PPI rose 4.4% YoY in the fastest increase since July 2018 and significantly ahead of February’s 1.7%. Expectations had been for 3.5% increase.
FX – EUR outperforms, GBP has worst week this year
The US Dollar on the rise tracing US treasury yields higher. However, the DXY is on track for its worst weekly performance since mid-December.
GBP/USD – The Pound has under-performed despite strong fundamentals. After particularly impressive gains in the first quarter investors are taking profits off the table. GBPUSD trades -0.8% this week.
Meanwhile the Euro has outperformed across the week, up 1% since Monday, on expectations that the sluggish vaccine rollout in the region will start to pick up quickly. The major economies in Europe such as Germany, Spain, France and Italy expect to vaccinate 70% of the population by the end of June.
GBP/USD -0.1% at 1.3715
EUR/USD trades -0.2% at 1.1881
Oil trades sideways with output compliance in focus
Crude oil prices continue to trade sideways after a steep drop at the start of the week as investors continue to weigh up the prospect of additional supply from OPEC as from next month against a weaker demand outlook as covid cases rise.
Concerns over compliance with OPEC output curbs are also surfacing after an S&P report pointed to oversupply by OPEC+ members to the tune of 450,000 barels per day in March with Russia and Iraq the worst offenders.
US crude trades -0.4% at $59.45
Brent trades -0.5% at $62.71
Learn more about trading oil here.
The complete guide to trading oil markets
Looking ahead
13:30 US PPI
13:30 Canadian jobs report
18:00 Baker Hughes oil rig count
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.
Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.