




Week Ahead FOMC ECB and UK election
After a quiet start today, volatility should pick up from mid-week ahead of three major events.
Share this:

After a quiet start today, volatility should pick up from mid-week ahead of three major events. Interest rate decisions from the Fed and ECB on due on Wednesday and Thursday, respectively. Then, it is all about the snap election in the UK which is also happening on Thursday with the outcome likely to be announced late in the evening or in the early hours of Friday. Meanwhile, the US-China trade situation remains uncertain. Another round of US tariffs on $156 billion of Chinese goods is due next Sunday. That’s unless the two sides manage to strike a phase one deal in time, in which case the new and some of the existing tariffs may be cancelled. However, there was no sign of that happening at the start of this week.
FOMC likely to maintain status quo
The dollar will be in focus on Wednesday given the fact we will have the latest US CPI reading (see below) and FOMC’s last meeting for the year to look forward to. With Friday’s monthly employment report surprising even the most optimistic of forecasts, and other US macro pointers not being too bad, the Fed may well provide a more upbeat outlook on the economy than expected. If so, this could see the markets reduce expectations for a rate cut in 2020, which should help provide some support to the dollar. However, trade uncertainty will be discussed in detail - make no mistake about it. For as long as there is a risk that the trade talks collapse, the risks to the economic outlook would be skewed to the downside. Meanwhile, policymaker may also take note of the somewhat alarming slowdown in US manufacturing activity as we have seen over the past few months. Although this may be due to temporary factors, prolonged weakness in the sector could potentially lead to job losses and impact other sectors of the economy. The Fed may therefore monitor factory activity closely going forward. All told, we think the FOMC’s policy statement or press conference will contain few surprises.
Lagarde’s first ECB policy decision
The European Central Bank’s last policy decision and press conference for 2019 will be on Thursday. However, this will be Christine Lagarde’s first policy decision as the ECB head. Judging by her few speeches since she took over, it is unlikely the ECB will alter monetary policy. However, Lagarde may announce some changes in the way the central bank has been doing things under her Italian predecessor Mario Draghi – this will unlikely cause too much of a reaction in the euro. Meanwhile, economic data in the Eurozone has been poor for much of 2019, although we have seen some positive surprises here and there of late. The improvement has been nothing too significant, however. We therefore think the ECB will maintain is dovish view. The single currency could come under some pressure, before the focus shifts to the UK election and Brexit…
PM Boris Johnson’s Tories expected to win majority in UK election
The UK’s eagerly anticipated general election is on Thursday with the outcome set to be announced late on the day or in the early hours of Friday. The means that the pound – and by extension, the FTSE – will be among the most important markets to watch for volatility towards the end of the week. Here is what my colleague Fiona Cincotta wrote earlier today on the pound and election:
- Boris Johnson maintains a healthy lead in the polls in the last few days heading towards the elections. The latest data showing voters intentions puts Boris Johnson with a double-digit lead of 11.9 points ahead of Labour’s Jeremy Corbyn.
- Traders are looking for the Tories to win by an overall majority. This is being seen to pave the way for Boris Johnson’s Brexit bill to pass quickly through Parliament, enabling the UK to leave the EU early next year with a deal in place.
- Conservative market friendly policies are also playing a part in boosting sterling. These are favoured over Jeremy Corbyn’s left leaning policies and the uncertainty that he brings to Brexit.
Other important macro events this week
- A handful of European data on Tuesday (e.g. German ZEW and UK GDP, construction and manufacturing output) are likely to be just a distraction ahead of the more important events later in the week.
- US CPI will provide some volatility for the dollar before Wednesday’s more important Fed decision takes centre stage (see above). Economists are predicting consumer prices to have risen to 2.0% on year-over-year basis, up from 1.8% previously. On a month-over-month basis, CPI is seen rising 0.2%. Meanwhile, core CPI is expected to have remained unchanged at 2.3% y/y with the m/m reading seen at +0.2%.
- Swiss National Bank’s monetary policy decision is on Thursday – this is unlikely to cause too much of volatility given that the SNB has not altered its policy in years and are unlikely to do so again this time.
- US retail sales on Friday will provide some distraction to what we think would be a volatile day for the pound. Still, the dollar could move meaningfully against other currencies, should retail sales surprise to the upside. Both headline and core sales are expected to print +0.4% respectively.
Featured chart: GBP/USD
Source: Trading View and City Index.
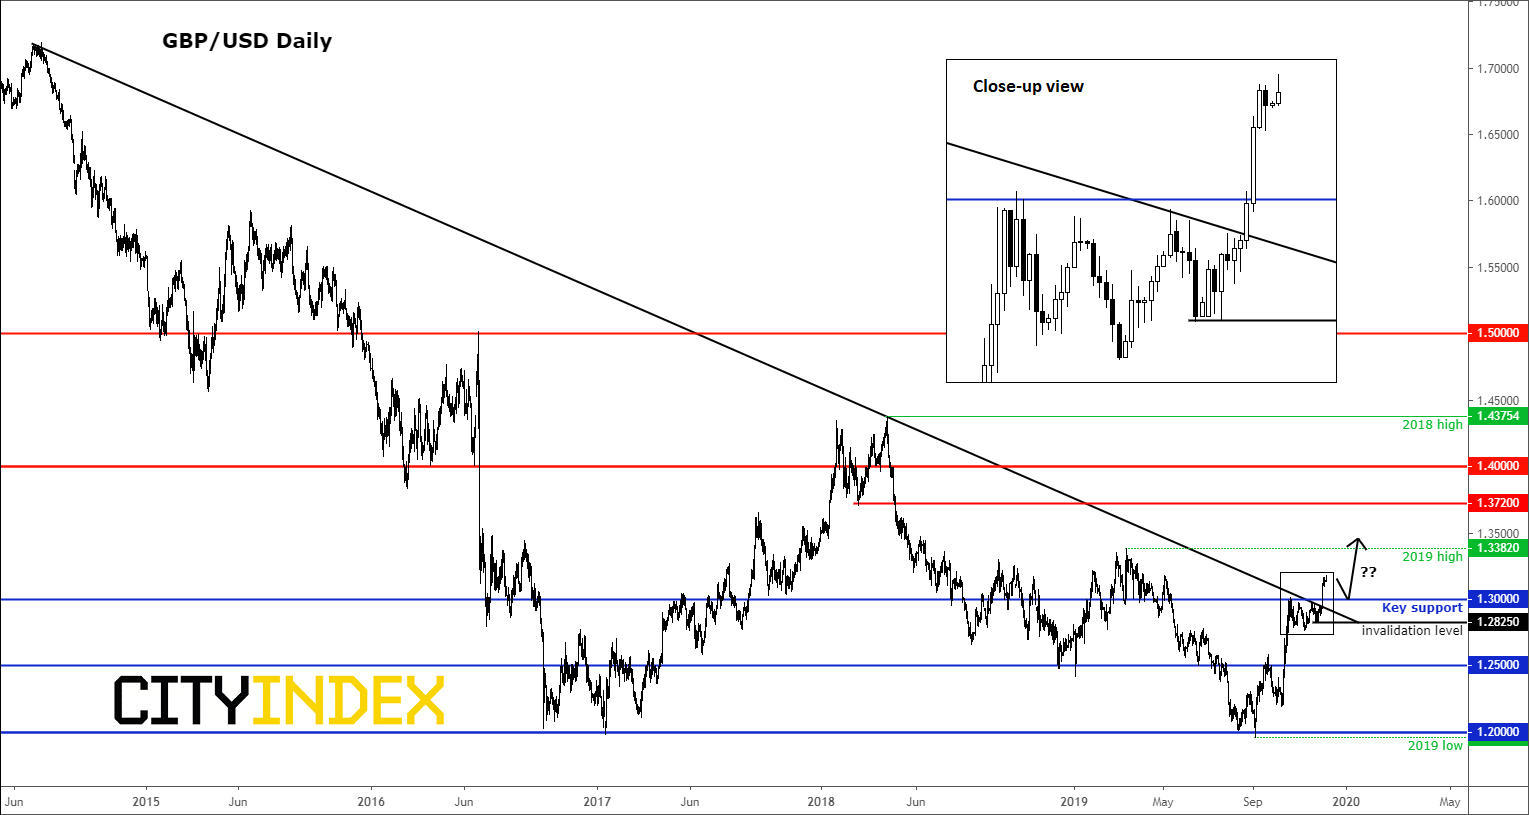
Given the importance of the UK election, which could shape the direction of Brexit, the pound is going to be the most important currency to focus on this week, we think. Like other pound crosses, the main GBP/USD pair has been making higher highs and higher lows in anticipation of a Conservatives majority win. If the polls were to tighten ahead of the elections, then the cable may pull back to the 1.30 handle before potentially resuming higher. As well as being a psychologically-important level, this was formerly resistance meaning it could turn into support upon a potential re-test. If the upward trend continues, as we think it might, then the liquidity above this year’s earlier high at 1.3380ish is the bulls’ main objective. The bears, meanwhile, will want to see a break down well below the 1.30 handle, and some bearish news too in so far as the election is concerned. A potential move below the most recent low circa 1.2825 would be the ideal outcome for them. However, at the time of writing, the bulls were in full control…
After a quiet start today, volatility should pick up from mid-week ahead of three major events. Interest rate decisions from the Fed and ECB on due on Wednesday and Thursday, respectively. Then, it is all about the snap election in the UK which is also happening on Thursday with the outcome likely to be announced late in the evening or in the early hours of Friday. Meanwhile, the US-China trade situation remains uncertain. Another round of US tariffs on $156 billion of Chinese goods is due next Sunday. That’s unless the two sides manage to strike a phase one deal in time, in which case the new and some of the existing tariffs may be cancelled. However, there was no sign of that happening at the start of this week.
FOMC likely to maintain status quo
The dollar will be in focus on Wednesday given the fact we will have the latest US CPI reading (see below) and FOMC’s last meeting for the year to look forward to. With Friday’s monthly employment report surprising even the most optimistic of forecasts, and other US macro pointers not being too bad, the Fed may well provide a more upbeat outlook on the economy than expected. If so, this could see the markets reduce expectations for a rate cut in 2020, which should help provide some support to the dollar. However, trade uncertainty will be discussed in detail - make no mistake about it. For as long as there is a risk that the trade talks collapse, the risks to the economic outlook would be skewed to the downside. Meanwhile, policymaker may also take note of the somewhat alarming slowdown in US manufacturing activity as we have seen over the past few months. Although this may be due to temporary factors, prolonged weakness in the sector could potentially lead to job losses and impact other sectors of the economy. The Fed may therefore monitor factory activity closely going forward. All told, we think the FOMC’s policy statement or press conference will contain few surprises.
Lagarde’s first ECB policy decision
The European Central Bank’s last policy decision and press conference for 2019 will be on Thursday. However, this will be Christine Lagarde’s first policy decision as the ECB head. Judging by her few speeches since she took over, it is unlikely the ECB will alter monetary policy. However, Lagarde may announce some changes in the way the central bank has been doing things under her Italian predecessor Mario Draghi – this will unlikely cause too much of a reaction in the euro. Meanwhile, economic data in the Eurozone has been poor for much of 2019, although we have seen some positive surprises here and there of late. The improvement has been nothing too significant, however. We therefore think the ECB will maintain is dovish view. The single currency could come under some pressure, before the focus shifts to the UK election and Brexit…
PM Boris Johnson’s Tories expected to win majority in UK election
The UK’s eagerly anticipated general election is on Thursday with the outcome set to be announced late on the day or in the early hours of Friday. The means that the pound – and by extension, the FTSE – will be among the most important markets to watch for volatility towards the end of the week. Here is what my colleague Fiona Cincotta wrote earlier today on the pound and election:
- Boris Johnson maintains a healthy lead in the polls in the last few days heading towards the elections. The latest data showing voters intentions puts Boris Johnson with a double-digit lead of 11.9 points ahead of Labour’s Jeremy Corbyn.
- Traders are looking for the Tories to win by an overall majority. This is being seen to pave the way for Boris Johnson’s Brexit bill to pass quickly through Parliament, enabling the UK to leave the EU early next year with a deal in place.
- Conservative market friendly policies are also playing a part in boosting sterling. These are favoured over Jeremy Corbyn’s left leaning policies and the uncertainty that he brings to Brexit.
Other important macro events this week
- A handful of European data on Tuesday (e.g. German ZEW and UK GDP, construction and manufacturing output) are likely to be just a distraction ahead of the more important events later in the week.
- US CPI will provide some volatility for the dollar before Wednesday’s more important Fed decision takes centre stage (see above). Economists are predicting consumer prices to have risen to 2.0% on year-over-year basis, up from 1.8% previously. On a month-over-month basis, CPI is seen rising 0.2%. Meanwhile, core CPI is expected to have remained unchanged at 2.3% y/y with the m/m reading seen at +0.2%.
- Swiss National Bank’s monetary policy decision is on Thursday – this is unlikely to cause too much of volatility given that the SNB has not altered its policy in years and are unlikely to do so again this time.
- US retail sales on Friday will provide some distraction to what we think would be a volatile day for the pound. Still, the dollar could move meaningfully against other currencies, should retail sales surprise to the upside. Both headline and core sales are expected to print +0.4% respectively.
Featured chart: GBP/USD
Source: Trading View and FOREX.com.
Given the importance of the UK election, which could shape the direction of Brexit, the pound is going to be the most important currency to focus on this week, we think. Like other pound crosses, the main GBP/USD pair has been making higher highs and higher lows in anticipation of a Conservatives majority win. If the polls were to tighten ahead of the elections, then the cable may pull back to the 1.30 handle before potentially resuming higher. As well as being a psychologically-important level, this was formerly resistance meaning it could turn into support upon a potential re-test. If the upward trend continues, as we think it might, then the liquidity above this year’s earlier high at 1.3380ish is the bulls’ main objective. The bears, meanwhile, will want to see a break down well below the 1.30 handle, and some bearish news too in so far as the election is concerned. A potential move below the most recent low circa 1.2825 would be the ideal outcome for them. However, at the time of writing, the bulls were in full control…
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD, USD/JPY Outlook: Oil, yields and an FX identity crisis
Crude oil is setting the tone across rates and FX, leaving EUR/USD vulnerable and USD/JPY caught between higher Treasury yields and the growing threat of intervention
AUD/USD Analysis: What's Next for the Australian Dollar After the RBA Decision?
Recent trading sessions have reflected a more neutral tone around the Australian dollar. This can be seen in AUD/USD price action, which has posted moves of roughly 0.2% over the last two sessions without establishing a clear direction. Much of this lack of momentum is linked to expectations surrounding the next policy moves from both the Reserve Bank of Australia (RBA) and the Federal Reserve.

USD into a Massive Week as Yields Fly and Gold Breaks
It’s a huge week with PCE and NFP, but it’s what’s happening off of the calendar that demands attention with US yields flying to fresh multi-decade highs.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.